


Lam Research Corp Stock (LRCX) Moved Down by 6.91% on Sep 14: What Signal Does It Send?



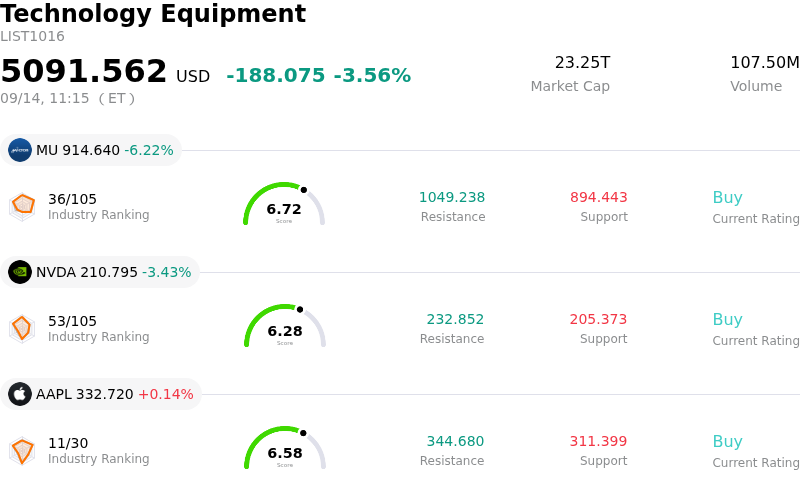
Lam Research Corp (LRCX) moved down by 6.91%. The Technology Equipment sector is down by 3.56%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 6.30%; NVIDIA Corp (NVDA) down 3.47%; Apple Inc (AAPL) up 0.13%.
What is driving Lam Research Corp (LRCX)’s stock price down today?
Lam Research experienced a sharp downward movement as a broad sell-off swept through semiconductor equipment stocks. Investors engaged in widespread profit-taking across chip toolmakers, driven by an emerging market debate over the pacing of artificial intelligence infrastructure investments. Recent industry commentary from technology leaders regarding potential moderation in the speed of AI model scaling rattled sentiment, prompting market participants to re-evaluate whether the aggressive expansion in wafer fabrication equipment orders can be maintained without interruption. Because equipment suppliers occupy the front end of the supply chain, their order visibility is acutely sensitive to any potential recalibration in capital expenditure plans from key memory and foundry customers.
Geopolitical risks and regulatory anxieties also contributed to the selling pressure. Lam Research maintains a sizable revenue concentration in China, leaving its long-term top line vulnerable to potential escalations in trade restrictions and export controls on advanced chipmaking machinery. At the same time, reports of state-backed international competitors advancing their domestic tool manufacturing capabilities have rekindled concerns regarding long-term competitive dynamics and potential market-share erosion in non-domestic markets.
A broader retreat across high-growth technology shares and macro pressure from elevated bond yields further weighed on the stock. Following an extended rally fueled by high-bandwidth memory adoption and complex vertical scaling requirements in advanced chip architecture, the company was trading at an elevated valuation multiple relative to historical benchmarks. This premium valuation made the stock particularly susceptible to profit-taking during periods of tech-heavy index weakness and sector-wide portfolio rebalancing. Despite management's positive structural commentary on long-term equipment demand at recent investment conferences, short-term market dynamics were dictated by valuation discipline and broader semiconductor sector rotation.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of -3.132, indicating a sell signal. The RSI at 38.286 suggests neutral condition and the Williams %R at 92.060 suggests oversold condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
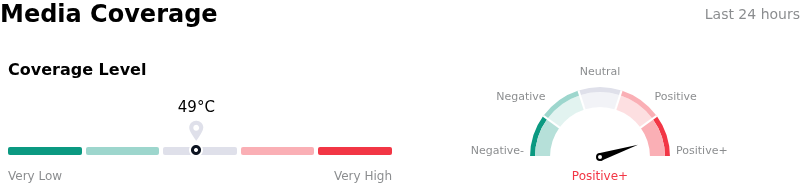
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Lam Research Corp (LRCX)
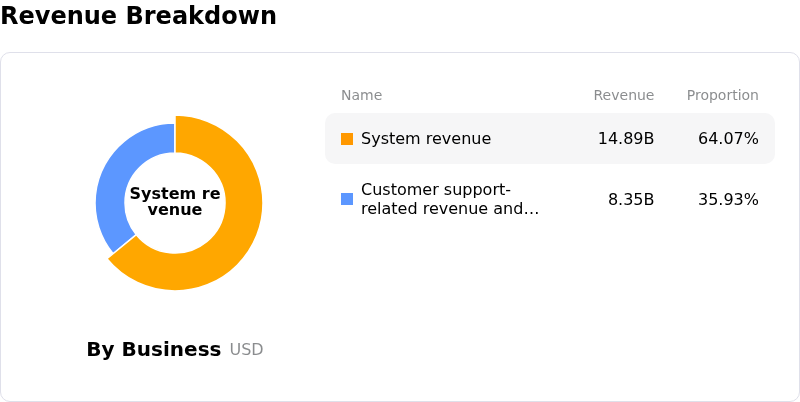
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $368.22, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- China Concentration and Export Control Restrictions: With a significant portion of total sales derived from Chinese chipmakers, Lam Research faces elevated exposure to expanding U.S. export control policies and Commerce Department restrictions that limit shipments to Chinese fabs, creating direct headwinds for equipment order volumes.
- Memory Sector Cyclicality and Capex Sensitivity: Because Lam's etch and deposition tools heavily depend on capital expenditure cycles from memory producers, cautious market commentary regarding potential tops in NAND and DRAM pricing creates risk that memory customers will delay equipment purchases or cut capital budgets.
- Elevated Valuation Multiple Vulnerability: Trading at a substantial premium to its historical price-to-earnings median and peer group averages, the stock is acutely susceptible to sharp intraday selloffs and sector-wide profit-taking during broader technology sector rotations or rising bond yield environments.
- Rising Competition from Domestic Chinese Suppliers: Increasing technological capabilities among Chinese state-backed equipment vendors, reinforced by government directives mandating local chipmakers to prioritize domestic sourcing, threatens long-term market share erosion for Lam's core deposition and etch platforms in China.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.