


Intel Shares Approach Three-Month Low Ahead of Earnings, Risking $85 Support as 18A Mass Production Faces Key Validation



AI Podcast


Intel will report Q3 2026 financial results after the market close on October 29 Eastern Time, amid technical consolidation near three-month lows. The company previously guided Q3 revenue between $15.8 billion and $16.8 billion, with an adjusted gross margin of 42% and adjusted EPS of $0.38. Beyond earnings, market focus centers on Intel 18A mass production progress, manufacturing costs, and foundry transformation effectiveness, particularly concerning Panther Lake and Xeon 6+ adoption. Technically, $85 serves as critical support, while the $100–$103 region acts as major resistance. Disappointing 18A metrics present downside risks toward $80.

TradingKey - Intel (INTC) will report its third-quarter 2026 financial results after the market close on October 29 Eastern Time. As its stock price has pulled back to near three-month lows, this earnings report is not only crucial to whether short-term growth can continue, but will also serve as an important indicator for the market to gauge Intel 18A mass production progress, manufacturing costs, and foundry transformation effectiveness.
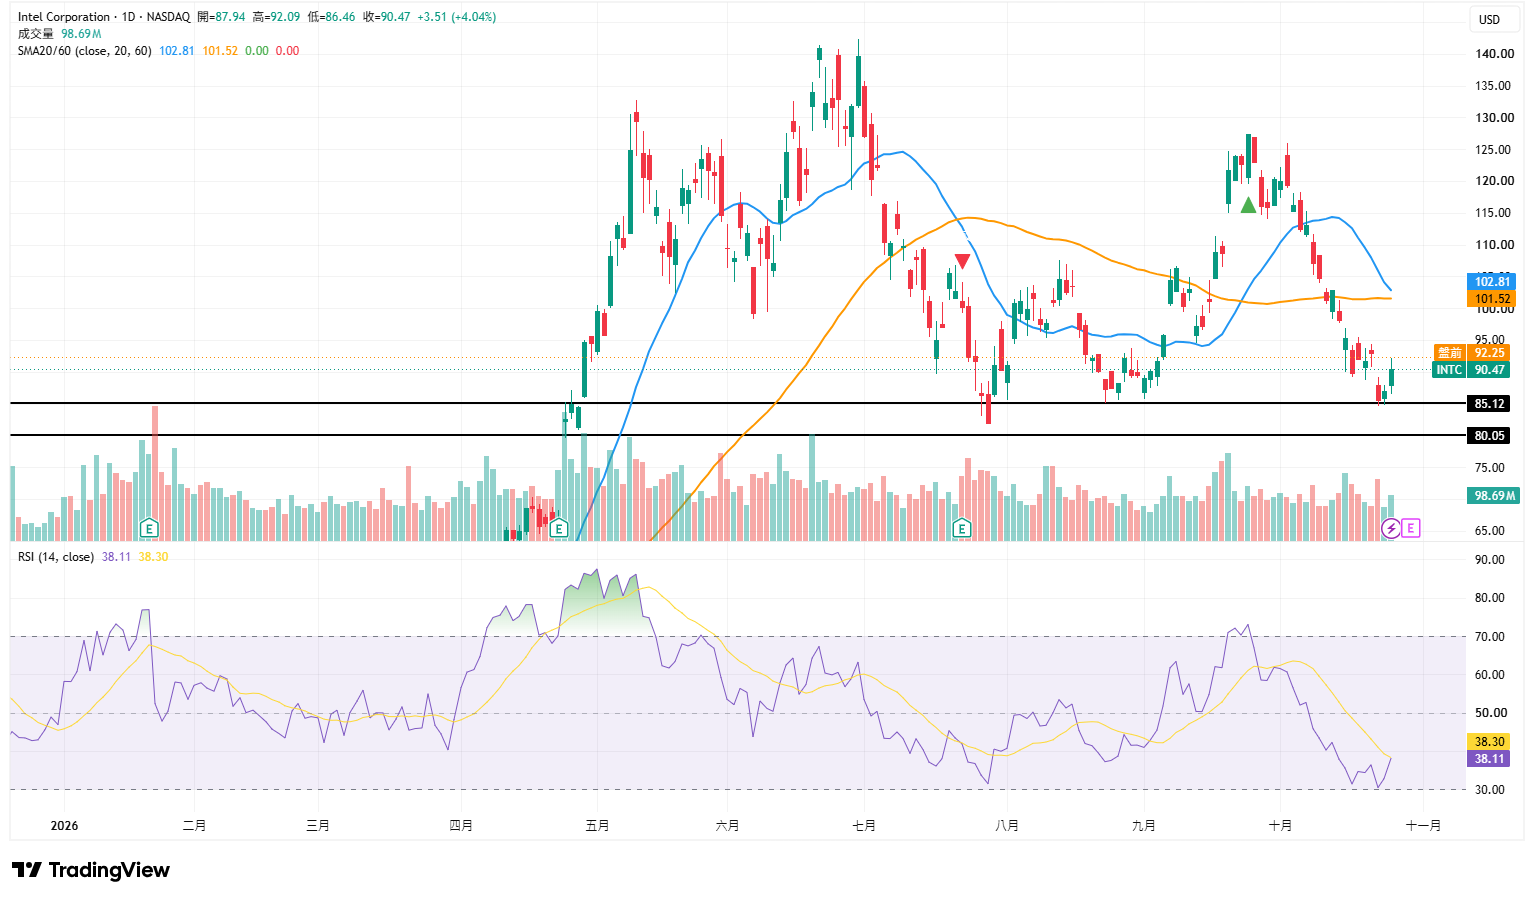
As of October 26, Intel's stock price stood at $90.47, rebounding by about 4% on the day. However, this rally has not changed the previously established weak structure, with the stock price remaining significantly below its 20-day moving average of $102.81 and 60-day moving average of $101.52, indicating that the $100 to $103 region has shifted from support to major resistance. Recent lows are concentrated around $85 to $86, making this area the most critical technical line of defense ahead of the earnings release.
In the previous quarter, Intel achieved $16.1 billion in revenue, up 25% year-over-year, marking one of its strongest quarterly revenue growth rates in 15 years, with adjusted EPS of $0.42. The company previously projected third-quarter revenue to range between $15.8 billion and $16.8 billion, with an adjusted gross margin of approximately 42% and adjusted EPS of $0.38.
Because the market has already priced in expectations for a partial business recovery, merely meeting guidance this quarter may not be sufficient to drive a significant stock price rally; investors will pay closer attention to whether the gross margin can continue to recover, as well as management's outlook on demand and costs for the upcoming quarter.
Compared with single-quarter revenue, the mass production performance of Intel 18A may be even more decisive. Intel has already pushed 18A-P into risk production and is using the 18A process for high-volume manufacturing of select Core Ultra Series 3 processors codenamed Panther Lake. The company also introduced Xeon 6+, its first server-grade product utilizing the 18A process, signaling that 18A is gradually transitioning from technical validation to commercialization.
Panther Lake serves as Intel's first touchstone to prove the stability of 18A. The node introduces RibbonFET gate-all-around transistors and PowerVia backside power delivery technology, which in theory can improve performance, power consumption, and transistor density. Intel previously stated that compared to Intel 3, 18A can boost performance per watt by up to 15% and increase chip density by about 30%.
Source: TradingView
From a technical perspective, Intel remains in a phase of consolidation. The RSI is currently around 38.11, having recovered from near oversold territory to approach its signal line at 38.30, indicating that selling momentum has weakened but has not yet formed a strong reversal. To the upside, focus first on resistance at $92–$95, with core resistance concentrated in the dual moving average area of $100–$103. Only a volume-backed hold above $103 would give the stock price a chance to rebound further toward $110–$115.
To the downside, $85 is the low of the past three months and the most critical support level ahead of earnings. If 18A mass production progress or customer adoption falls short of expectations, causing the stock price to break below $85 on heavy volume with daily closing confirmation, the next support level will be at $80, representing approximately 11% downside risk from the current price.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.