


SK Hynix Q3 Earnings Preview: Focus on HBM4 Ramp-Up and $12.1 Billion Special Dividend, Wall Street Highest Price Target at $320



AI Podcast


SK Hynix is expected to report robust third-quarter fiscal 2026 financial results on October 28, driven by surging AI memory demand, higher DRAM and NAND prices, and strong shipments of HBM4 and server DDR5. Despite recent stock volatility and investor concerns over the cyclical sustainability of the memory boom, short-term supply and demand remain tight. Additionally, potential plans for a substantial special dividend funded by Kioxia stake sales could significantly enhance shareholder returns. WallStreet analysts maintain a broadly optimistic outlook, citing the company's leading competitive edge in high-bandwidth memory and high-profit margins.

TradingKey - SK Hynix (SKHY) will report its third-quarter fiscal 2026 financial results on October 28. Amid continued growth in AI memory demand and rising DRAM and NAND prices, the company's profitability remains a market focus; however, its stock price has pulled back noticeably recently, as investors begin to worry whether the memory industry's strong boom can be sustained.
According to FactSet data, SK Hynix's third-quarter revenue is expected to reach $71.05 billion, up about 316% year-over-year, while adjusted earnings per share are projected at $6.15, representing a year-over-year increase of about 392%.
Meanwhile, the market is awaiting SK Hynix's announcement of its latest shareholder return plan. Previous reports indicated that the company might pay a special dividend of up to 16 trillion Korean won (approximately $12.1 billion), funded primarily by investment returns from selling shares of Japanese memory chipmaker Kioxia.
SK Hynix has responded that it is reviewing various shareholder return measures, but has not yet confirmed the specific amount of the special dividend. If finalized, the plan could become a major highlight of this earnings report and will also shape market expectations regarding the company's cash allocation and shareholder return policy.
Market Focuses on How Far Memory Cycle Can Go Amid Stock Pullback
Since listing on the Nasdaq in mid-July, SK Hynix's stock price has experienced significant volatility, trading between approximately $124.80 and $199.87 over the past three months. Following the release of the company's second-quarter results, driven by strong profitability in HBM and server DRAM, the stock price surged by about 57% in less than two months. However, as market concerns resurfaced over AI capital expenditures, memory prices peaking, and expansion by Chinese manufacturers, SKHY has pulled back by about 28% from its historical peak.
This pullback reflects a shift in investor focus. Previously, the market was primarily betting that AI demand would drive memory chip supply shortages, higher product prices, and continuous margin improvement. Now, as memory stocks undergo a broad retreat, investors have begun to question how long high prices can be sustained, whether cloud providers' AI capital expenditures can continue to support demand, and whether current stock prices have fully priced in future earnings growth.
From an industry supply-and-demand perspective, the memory market remains well-supported in the short term. TrendForce forecasts that DRAM contract prices will rise by 13% to 18% quarter-on-quarter in the third quarter of 2026, while NAND flash contract prices will increase by 10% to 15%. The research firm also projects that the DRAM contract price increase could further expand to 20% in the fourth quarter. If this trend continues, SK Hynix will have the opportunity to keep benefiting from rising prices and an improved product mix.
However, the memory industry is inherently cyclical, and rising prices alone cannot guarantee a long-lasting boom. Once supply expansion outpaces demand, or if cloud providers slow down their investments in AI infrastructure, both memory prices and corporate earnings could come under pressure. Therefore, a key area to monitor in this earnings release is whether management can confirm that supply and demand remain tight in the fourth quarter, and whether demand for high-end memory products is strong enough to support further price increases.
HBM4 and High Profit Margins Determine the Quality of Earnings Growth
SK Hynix's core advantage remains in high-bandwidth memory (HBM) and high-value-added DRAM products. As requirements for memory bandwidth and capacity in AI model training and inference continue to rise, HBM has become a major driver of the company's profit growth. Compared to relying solely on memory price increases, a higher share of high-end product shipments is more conducive to maintaining strong pricing power and profit margins for the company.
According to the provided second-quarter data, SK Hynix recorded quarterly revenue of approximately $54.55 billion and operating profit of about $45.2 billion, achieving an operating margin of 76.3%, higher than TSMC's 60.3% operating margin for the same period and Micron's 67.6% margin for its corresponding quarter. Meanwhile, benefiting from increased shipments of server DDR5 and high-capacity HBM3E products, the company's DRAM blended average selling price rose by about 30% quarter-on-quarter in the second quarter, while the average selling price of NAND flash memory increased by over 50%.
Growth momentum in the third quarter mainly stems from HBM4, HBM3E, and server DDR5. SK Hynix previously stated that 12-layer HBM4 has already entered mass production and shipment to core customers, with its yield and quality approaching those of the relatively mature HBM3E products. If the scrap rate stays low in the early stages of mass production, unit manufacturing costs are expected to decline as shipment volume expands, providing support for gross margins.
The company expects DRAM bit shipments to grow by approximately 10% quarter-on-quarter in the third quarter and projects that product mix improvements in the second half of the year will outpace those of the first half. Increased contributions from HBM4 and 1c-nanometer DRAM will not only help boost shipment volumes, but may also continue to push up the blended average selling price.
Special Dividends May Become Another Major Highlight
Beyond operating data, shareholder returns could be the biggest additional highlight of this earnings report. According to reports, SK Hynix may pay out a special dividend of approximately 16 trillion won, or roughly $12.1 billion, from the proceeds of selling its Kioxia stake.
SK Hynix initially invested in Kioxia through a special purpose vehicle, committing a cumulative total of around 4 trillion won. As the relevant shares and convertible bonds are sold, the market estimates the company's net proceeds could reach 20 trillion won. If the special dividend eventually approaches 16 trillion won, equivalent to returning about 80% of the investment gains, it will significantly boost SKHY's short-term shareholder return appeal.
The company previously announced a large-scale share repurchase and cancellation plan, and pledged to allocate at least 50% of its free cash flow from 2025 to 2027 to shareholder returns. Pausing Solidigm's IPO plan has also alleviated some market concerns over asset carve-outs and capital allocation.
Wall Street overall remains optimistic about SK Hynix. According to TipRanks, the 12-month average price target among 11 analysts covering the stock is $254.70, with a high target of $320 and a low target of $200.
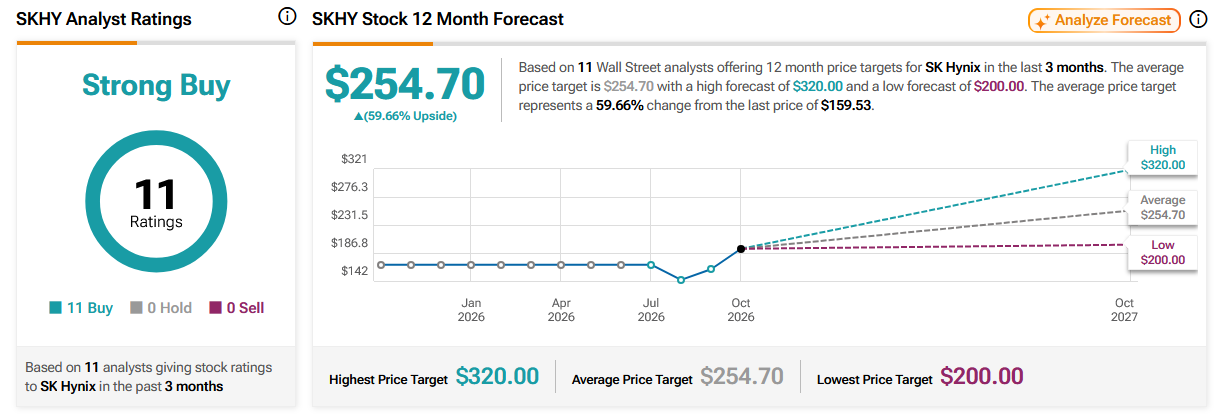
Source: TipRanks
Bullish views hold that tight memory supply and demand could persist through 2028, and SK Hynix's competitive edge in HBM along with its high profit margins are expected to support continued earnings growth. Based on this, some analysts believe the market has not yet fully reflected the company's medium-term earnings potential.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.