


Tesla Q3 Earnings Preview: Can Auto Margins Stabilize? Wall Street’s Highest Price Target at $550



AI Podcast


Tesla will report its third-quarter 2026 financial results on October 21, Eastern Time. Consensus estimates project revenue of $27.9 billion to $28.1 billion and adjusted EPS of $0.44 to $0.45, reflecting a lag in profitability recovery despite better-than-expected deliveries of 486,532 vehicles. Key metrics include automotive gross margins, projected near 17%, and free cash flow under pressure from rising capital expenditures. Long-term valuation increasingly depends on the commercialization progress of Robotaxi, FSD, and Optimus, alongside potential updates regarding capital allocation and emerging AI-driven business models amid divergent Wall Street sentiment.

TradingKey - Tesla (TSLA) will report its third-quarter 2026 financial results after the U.S. stock market close on October 21, Eastern Time, and host an earnings conference call at 17:30 that day. The market is focusing on the commercialization progress of Robotaxi, FSD, and Optimus, as well as expanding capital expenditures.
The market expects Tesla's third-quarter revenue to be approximately $27.9 billion to $28.1 billion, roughly flat compared with the same period last year. Adjusted earnings per share are expected to be $0.44 to $0.45, down from $0.50 in the prior-year period. In other words, the recovery in deliveries has not yet fully translated into improved profitability, and pricing strategy, product mix, and cost control will continue to determine the true quality of this quarter's performance.
Deliveries Beat Expectations: Can Auto Margins Improve?
Tesla delivered a total of 486,532 vehicles in the third quarter, beating the company-compiled market consensus of 461,974 vehicles; vehicle production for the period was 464,391 units, and energy storage deployments reached 13.7 GWh. Although delivery volume rebounded sequentially and beat expectations, it was still down about 2% year-on-year, indicating that the automotive business has not yet re-entered a stable growth trajectory.
Beyond sales volume, automotive gross margin is likely the most critical metric in this earnings report. In the second quarter, Tesla's automotive gross margin excluding regulatory credits was approximately 16.3%, while free cash flow stood at negative $1.1 billion. The market expects the third-quarter automotive gross margin to recover to around 17%, but price cuts and promotions, tariffs, warranty costs, and expenses for ramping up new products could limit the extent of the improvement.
If delivery growth relies primarily on price incentives while per-vehicle profitability fails to rebound in tandem, the support provided by better-than-expected sales volume to valuation will be relatively limited. Conversely, if automotive gross margin improves noticeably while inventory and operating expenses remain stable, the market may view it as a signal that the traditional automotive business is nearing a bottom.
Robotaxi and Optimus: Key Variables Determining Long-Term Valuation
Compared with single-quarter vehicle sales, Robotaxi, FSD, and Optimus are exerting a greater influence on Tesla's long-term valuation. Investors are already willing to pay a higher premium for its autonomous driving and robotics businesses, but the market's patience for conceptual showcases is wearing thin.
On autonomous driving, the market is eager to learn about the expansion pace and operational scope of the Robotaxi fleet, paid FSD subscription performance, and progress in unsupervised driving technology. Tesla previously launched Robotaxi operations in select U.S. cities, but fleet scale, regulatory requirements, and unit economics remain the primary challenges to commercialization.
Morgan Stanley previously emphasized that Tesla's ability to expand FSD mileage and advance unsupervised autonomous driving will directly impact the market's assessment of its long-term valuation. If autonomous driving technology can be gradually converted into scalable operational services, it is expected to create new revenue streams in the future.
Optimus is also at a critical development stage. Tesla is pushing forward with robot production facilities and related technology R&D, but dexterous hands, component supply, mass-production costs, and practical application scenarios still require further verification. Therefore, management's latest updates on Optimus's mass-production timeline, production targets, and commercial applications during this earnings report and conference call could serve as key drivers of market sentiment.
In addition, Tesla recently showcased the next-generation Roadster featuring SpaceX technology, with production scheduled to start in 2028. While this model helps demonstrate engineering synergies between the two, mass production remains some time away, and its short-term financial contribution is expected to be limited. For investors, the Roadster's greater significance lies in technology demonstration and brand equity, rather than an immediate boost to quarterly profits.
Market Focuses on Capex and SpaceX Merger Rumors
Tesla is stepping up investments in AI, autonomous driving, robotics, and related manufacturing facilities, making capital expenditures and free cash flow crucial components of this earnings report.
According to consensus sell-side estimates compiled by Tesla, third-quarter capital expenditures are expected to be approximately $7.77 billion, operating cash flow around $3.27 billion, and free cash flow projected at negative $4.51 billion.
If actual capital expenditures exceed expectations while operating cash flow falls short of covering new investments, Tesla's free cash flow pressure could intensify further. Conversely, if the company can control costs while maintaining R&D spending and gradually boost revenue contributions from new businesses, market concerns over its capital allocation efficiency are likely to ease.
Meanwhile, rumors of a potential merger between Tesla and SpaceX (SPCX) have also drawn attention. Barclays analysts previously noted that the two sides might announce a deal before Tesla's annual shareholder meeting on December 3, but as of now, neither company has officially confirmed any merger plans. Tesla's latest proxy statement addresses topics such as director re-elections and executive compensation, and does not list a merger as an explicit voting item.
Wall Street remains sharply divided on Tesla. Bullish institutions believe that Robotaxi, FSD, and Optimus could transform Tesla from an automaker into an artificial intelligence and robotics platform. Cautious views argue that these businesses still face a long road toward scalable profitability, and current valuations have already priced in a significant portion of long-term growth.
According to TipRanks statistics, a total of 27 analysts have provided 12-month price targets for Tesla over the past three months, with an average target of $402.47, a high forecast of $550, and a low of just $24.86. Such a wide range underscores that the market has yet to reach a consensus on valuation methodologies for Tesla's traditional automotive business versus its artificial intelligence business.
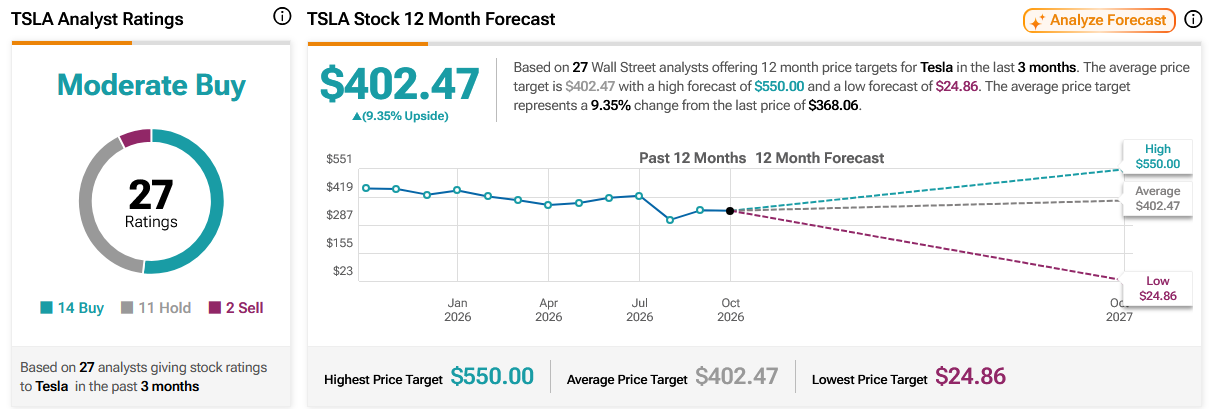
Source: TipRanks
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.