


Apple Stock Forecast: HomeView Broadens AI as iPhone 18 Faces a Cost Test



AI Podcast


Apple maintains a cautiously bullish outlook ahead of its November 2 earnings, driven by resilient market share, the new HomeView smart display, and regulatory approval for Apple Intelligence in China. However, rising component costs, reduced iPhone 18 Pro order reports, regulatory pressures on Services, and a contested $5.7 billion patent verdict present notable risks. While strong fiscal Q3 results and recurring Services revenue support the uptrend, investors should monitor gross margins, China sales, and key technical levels. A confirmed close above the $348.15 resistance is favored before entering new positions, with downside support near $328.65.
TradingKey - Apple (NASDAQ:AAPL) closed at $342.96 on October 14, up 0.50% for the day, outperforming the Nasdaq during the session. While Apple’s news around Siri makes HomeView a more tangible product, there are reports of orders for the iPhone 18 Pro components being reduced.
My outlook remains cautiously bullish. Apple will have to show that they can sustain devices margins and Services growth in the face of memory shortages, increasing prices, and an overall difficult market condition heading into their November 2nd earnings.
HomeView Extends Siri AI Into the Home
Announced on October 13, Apple HomeView is a video smart display and the company’s new smart-home hardware product. It integrates with HomeKit to control several functions in the house, and with Siri to recognize up to 6 users. The device goes for a suggested retail price of $299 and will be available starting November 13.
HomeView gives Apple Intelligence another hardware platform rather than leaving AI to the iPhone Software. Like the iPhone, HomeView uses the A18 chip for local processing, although Siri requests may also use Private Cloud Compute. Actual adoption and Services spending will ultimately return the investment.
iPhone 18 Pro Orders Face a Demand Test
Reuters reported Apple reportedly asked suppliers to reduce component orders for the iPhone 18 Pro and Pro Max by at least 15% for October, citing Nikkei Asia. Apple reportedly raised prices by $100 due to higher memory costs. Apple did not comment on the production change.
According to Counterpoint, global smartphone shipments declined by 20% in Q3, the weakest third quarter since 2012. Apple captured a record 22% global smartphone market share, despite a decline in its shipments. The absence of the lower-priced iPhone 18 in September’s lineup also improved volume comparisons.
China Offers an AI Catalyst Despite Weaker Sales
IDC estimated that Chinese smartphone shipments declined by 15.4% to 57.9 million in Q3. Apple came in second place with 17.8% market share, behind Huawei at 21%; Apple shipments declined by 4.3%. The limited iPhone lineup impacted volumes, but new model sales outperformed expectations.
On October 15, Reuters said Apple CEO Tim Cook said Apple Intelligence received regulatory approval in China, and expects testing in October. Regulatory approval in China does not mean the local launch of Apple Intelligence or material revenue.
Q3 Earnings Were Strong, Partly Helped by Refunds
Apple’s fiscal Q3 revenue grew 16% to $109.4 billion, and diluted EPS rose 29% to $2.02. Revenue from iPhones rose 21.7% to $54.25 billion and Mac sales rose 28.8%. Gross margin was 50.1%.
Refunds of prior year’s tariffs positively impacted EPS by $0.11 and gross margin by roughly two percentage points. Management projected revenue growth of 9%-11% for fiscal Q4. In July, analysts projected revenue growth of roughly 12% for fiscal Q4. Thus, the quality of reported iPhone sales and underlying margin will be critical.
Services Remain the Recurring Growth Engine
Apple reported FQ3 services revenue of $30.74 billion, up 12.1% from last year and missing Wall Street expectations. Continuous regulatory pressure on in-app purchases and payment rules affected Apple’s mobile gaming, but subscription services and Apple’s large user base offer recurring revenue stream.
Alongside other personnel changes in Apple Services, Adrian Perica will also take on a wider role to include iCloud and Fitness+. With higher costs associated with components in the new devices and expected even higher costs for next year’s upgrades, I will be interested to see how Apple Services maintain double digit growth.
$5.7 Billion Patent Verdict Is Still Contested
On October 14, Apple filed a motion asking a federal judge to overturn a September verdict whereby a jury awarded $5.7 billion to Taction Technology. The jury sided with Taction and found that Apple infringed on patents relating to haptic feedback used in iPhones and Apple Watches. The amount is large, but the verdict is not a cash outflow and is still contested.
November 2 Results Are the Next Major Catalyst
Apple's Q4 earnings will be on November 2 . I’ll pay attention to the gross margins, China sales and Services, iPhone 18 demand, and the overall guidance.
I expect component and memory cost increases, but I’m also expecting gross margin increases as well. Weakness in China or increasing component costs, combined with lack of pricing power, would create an extremely challenging environment to meet expectations.
Apple Technical Analysis: $348 Breakout Is the Next Test
AAPL closed at $342.96 on October 14 after trading within the range of $341.72 and $347.09. The supplied chart shows a rising channel with higher lows and a breakout above the former $328.65 supply zone. The ascending EMA and the lower channel boundary converge within the $327-329 area and support the uptrend.
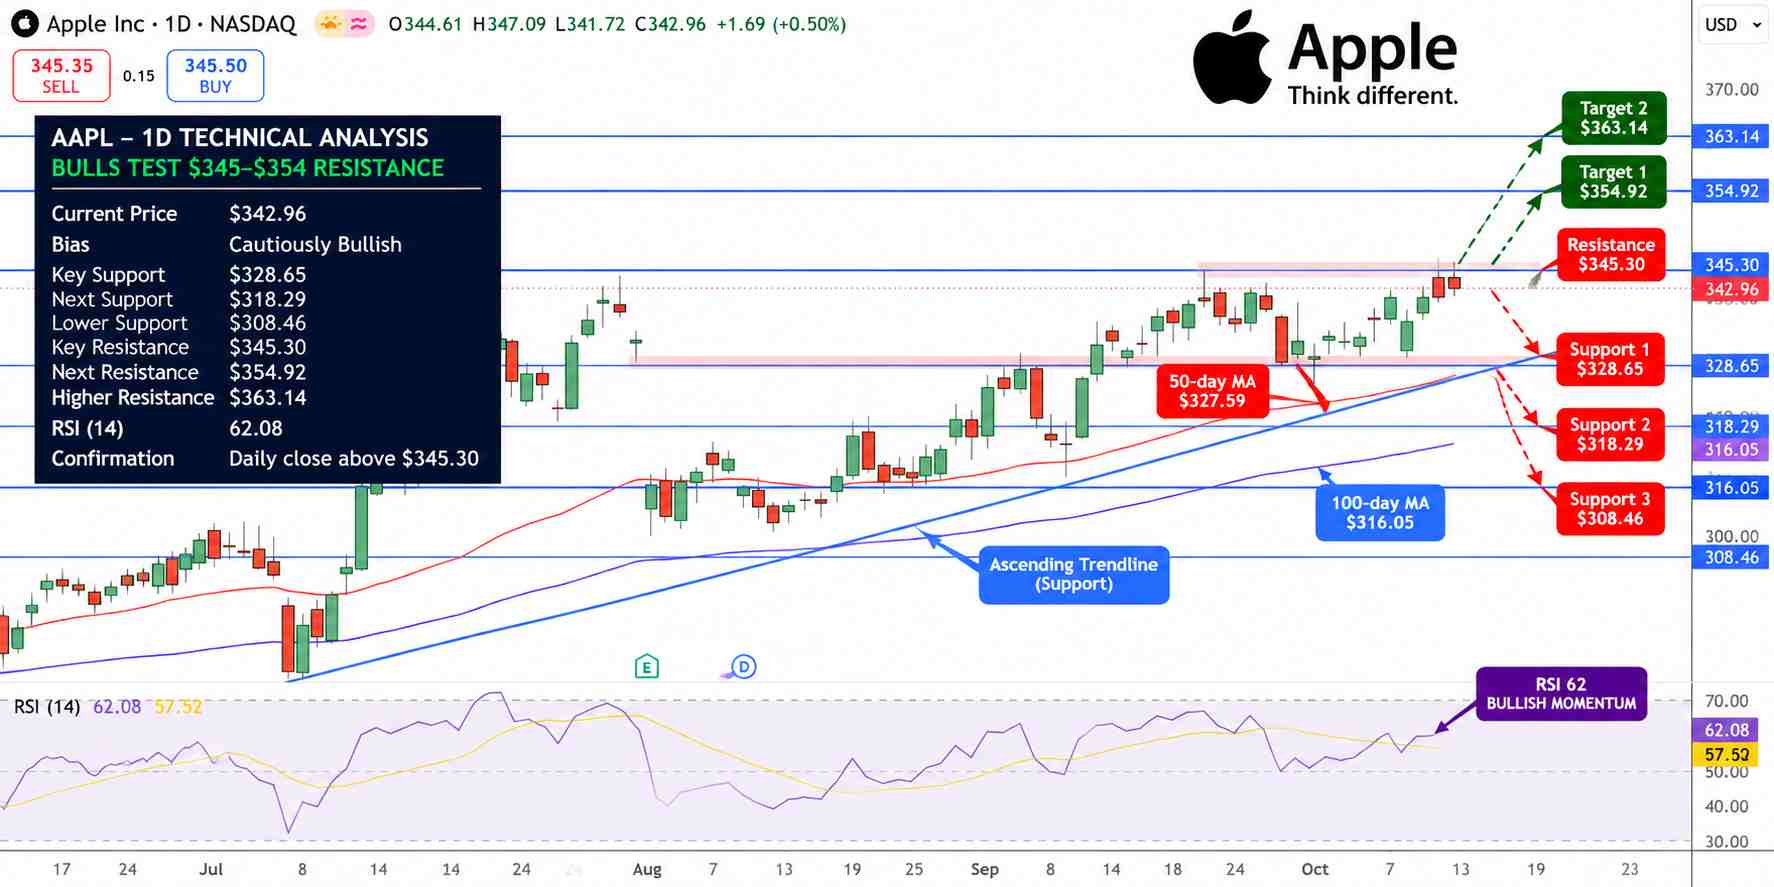
APPLE Price Chart - Source: Tradingview
Rising trendlines and indicators within the channel have not been verified. The verified October 13 high at $348.15 adds nearby resistance. The chart-derived targets are at $354.92 and $363.14.
I am bullish as long as AAPL remains above $328.65. A close above $348.15 would support the break towards $354.92 and then $363.14. Losing the $328.65 and then the $327.59 support would invalidate the rising channel. The potential entry at $342.96, stop at $327.59, and target at $354.92 has more downside risk (15.37)thanupsidepotential(11.96). Until I see a better entry or a breakout/breakdown, I will not be trading this.
Key Levels
- Latest Close: $342.96 on October 14, up 0.50%
- Support: $341.72; then $328.65 and $327.59
- Resistance: $347.09 - $348.15; then $354.92 and $363.14
- RSI: near 62 on supplied chart; not independently verified
- Breakout trigger: close above $348.15
- Breakdown trigger: close below $327.59
Why Does HomeView Matter for Apple?
It provides Siri with AI functionality for controlling various smart home gadgets. This may enhance customer loyalty and demand for Apple Services. HomeView’s commercial success is still to be determined.
What Is AAPL’s Immediate Breakout Level?
The high of October 13 at $348.15 is confirmed resistance. A close above this level would put $354.92 in view.
Bottom Line
HomeView and China's AI approval are potential catalysts. Higher component costs, handset demand, and lawsuits are risks. I see upside potential above $328.65, but prefer a breakout be confirmed first.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.