


Qualcomm Stock Forecast: Arm Verdict and Amazon AI Deal Test $176 Support



AI Podcast


Qualcomm closed at $176.86 on October 13, supported by a strategic legal win against Arm and AI expansion efforts, including a potential $60 billion Amazon partnership for data center chips. While automotive and IoT sectors show robust growth, smartphone market risks and shrinking margins remain concerns. Management projects significant non-handset revenue scaling by fiscal 2029. Ahead of the November 4 fiscal fourth quarter earnings report, technical indicators show mixed momentum, with immediate support at $176.04–$176.64 and resistance at $178.46. Overall, the outlook is cautiously bullish, contingent on firm purchase orders and margin stability.

TradingKey - Qualcomm (NASDAQ: QCOM) closed at $176.86 on October 13, up 1.39%, after reaching $180.78 in intraday trading. A Delaware jury’s verdict in Qualcomm’s case against Arm recently provided some new catalysts. Qualcomm intends to expand into AI, and this verdict could help with that effort.
Can Qualcomm’s efforts in the automotive and data centers help offset the decline in the handset market? Qualcomm will report fiscal fourth quarter earnings on November 4.
Arm Verdict Brings Strategic, Not Immediate, Relief
On October 13, a Delaware jury ruled Arm breached a licensing agreement and intentionally interfered with Qualcomm’s relationship with Meta, but awarded Qualcomm only $2 in damages, and ruled for Arm on the other claims. Arm and Qualcomm focused on the elements of the verdict that helped their case.
A judge still has to decide if Arm breaching the agreement allows Qualcomm to stop paying royalties for five years. Reuters reported that the disputed royalties could amount to billions of dollars over that period, but that type of relief has never been granted. For now, this is a legal win, strategically, but not financially, for Qualcomm.
Amazon Agreement Creates a Potential $60 Billion Opportunity
In September, Qualcomm announced a deal with Amazon for custom AI chips and 1.6-terabit optical connectivity for its data centers. According to an SEC filing, Qualcomm's potential upside from this deal with Amazon is as high as $60 billion. This filing doesn't represent guaranteed purchase orders or booked revenue.
Amazon holds warrants to purchase up to 25 million shares of Qualcomm at $161.26 per share. Commercial arrangements, purchase orders and actual purchases determine the vesting of the warrants; 3.75 million shares vested upon issuance. Multiplying the share price by the share count does not reflect the true fair value of the warrant. The deal carries the risk of dilution.
Data Centers Could Transform Qualcomm's Revenue Mix
Qualcomm expects that by fiscal 2029 it will generate about $15 billion in annual data-center revenue and total non-handset revenue of about $40 billion. Management expects year-over-year non-handset revenue growth to accelerate from 24% in fiscal 2026 to more than 60% in fiscal 2027.
While the bets by Amazon, Microsoft and Meta on Qualcomm for their data center needs is a positive, I will wait to value the stock based on firm purchase orders, shipments and revenue.
Smartphone Shipments Remain the Biggest Threat
Fiscal Q3 automotive revenue jumped 61% to $1.59 billion, marking 23 consecutive quarters of double-digit growth. Demand for computing and ADAS chips is positive.
BMW selected Qualcomm for lead compute-silicon provider for next-generation cockpit and automated-driving programs. Revenues for this program will be realized in the future.
Snapdragon Builds the Edge-AI Case
Snapdragon 8 Elite Extreme Gen 6 and 8 Elite Gen 6 were shown off at the Snapdragon Summit. The key feature here was the implementation of “on-device agentic AI”. Googlebook and Linux were highlighted for Qualcomm’s PC processors.
It was hinted that Qualcomm’s focus would broaden beyond just servers and phones with the support of software and hardware to run AI locally. Formonetization to occur though, it would take changes in the adoption of the hardware by the end consumer.
Fiscal Q3 Margins and Cash Returns Need Attention
Revenue was $9.95 billion for a 4% decline YoY and non-GAAP EPS fell 20% to $2.21. QCT revenue was $8.50 billion, a 4% increase YoY. IoT revenue was up 9% to $1.83 billion. QCT earnings before tax margin dropped to 26% from 30% due to increasing costs.
Qualcomm returned $2.3 billion for the quarter, buying back $1.4 billion of stock and paying out $973 million in dividends. The cash and marketable securities balance was $8.30 billion at the end of the quarter, with $20.6 billion authorized for share repurchases. These compete for funds to invest in other business opportunities.
November 4 Earnings Are the Next Catalyst
For fiscal Q4, the outlook is between $9.7 and $10.5 billion in revenue and a non-GAAP EPS of $2.05 to $2.25. Qualcomm confirmed an earnings call for November 4 at 4:45 pm ET.
New revenue without further margin erosion will improve my outlook, while the reverse will be true if handset revenues shrink faster than new segments grow.
Qualcomm Technical Analysis: $176 Recovery Needs Confirmation
QCOM closed at $176.86 on October 13 after trading in the range of $172.29 to $180.78. The verified session low of $172.29 briefly breached the chart-derived $176.04 to $176.64 support band before shares recovered to close above it. This is a rebound attempt and not evidence that the channel held for the entire session.
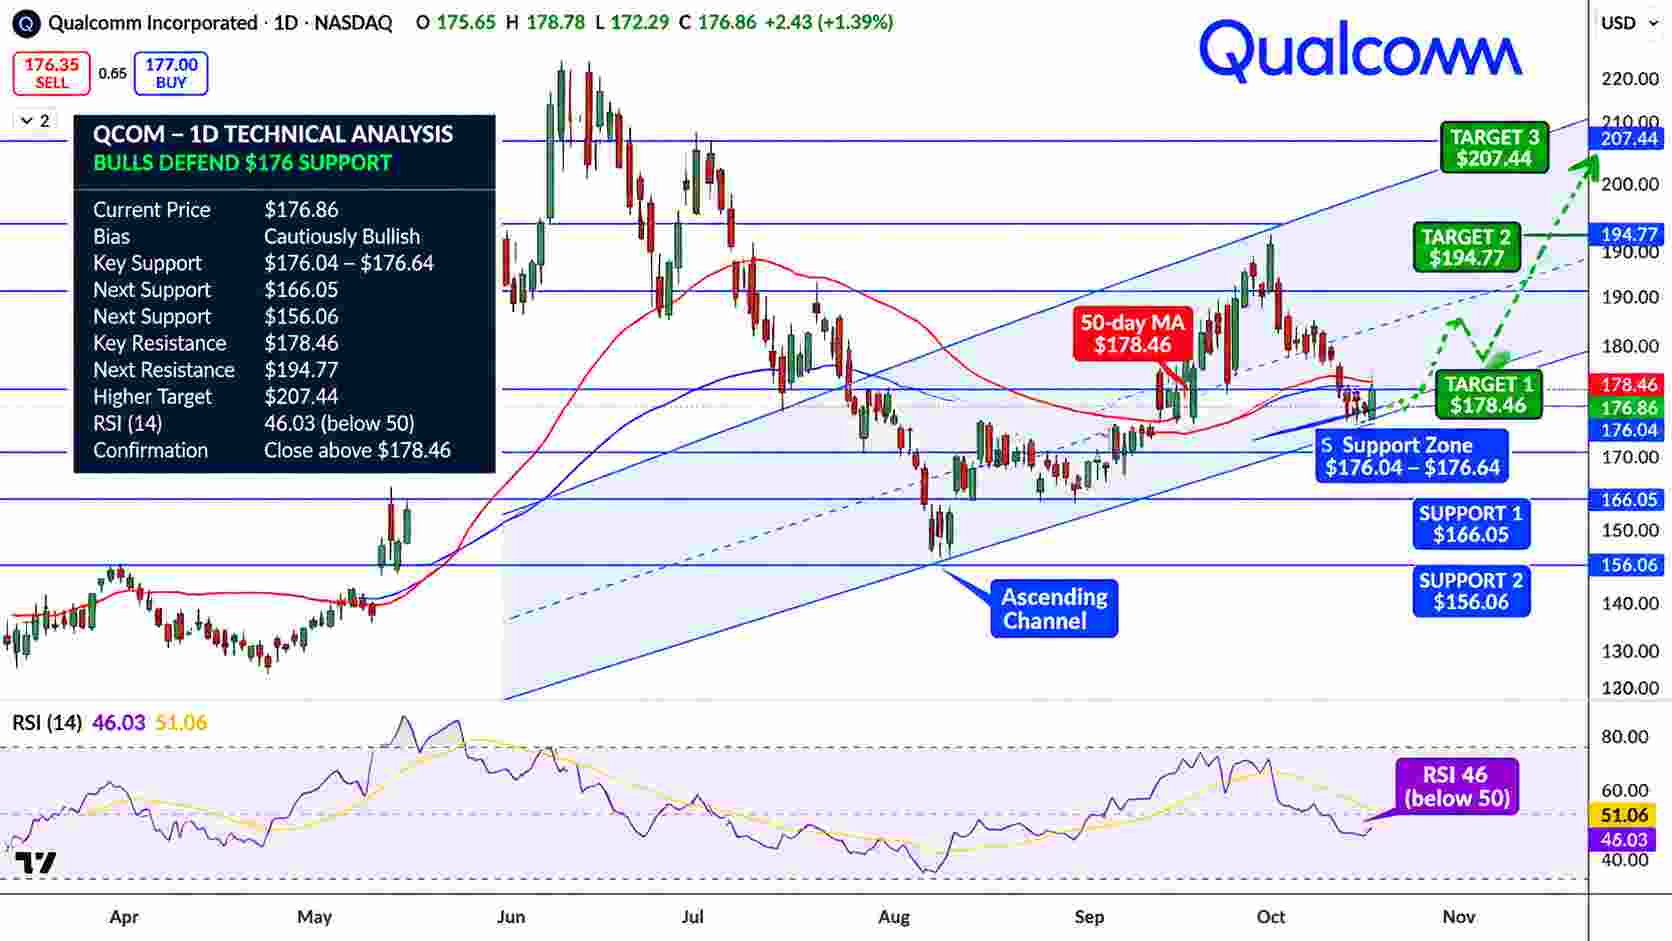
Qualcomm Stock Price Chart - Source: Tradingview
The provided chart shows the moving averages in the range of $176.64 to $178.46, and RSI in the range of 46 and an indicator line at 51. Momentum remains mixed, with selling interest near $180.78 and an attempted recovery above $176.04.
The current chart shows a tentative recovery, and I would also prefer to see a close below the range of $176.04 to $176.64 to confirm a bearish case. A confirmed close above $178.46 and the verified high of $180.78 would negate the bearish case and expose the chart-derived levels of $194.77 and later $207.44. A confirmed close below the range of $176.04 to $176.64 would support the bearish case and expose the levels of $166.05 and $156.06. Earnings reports could also result in large gaps through these levels and I prefer to see repeated closes, rather than just one intraday trade, to confirm levels.
Key Levels
Latest Close: $176.86 on 10/13, up 1.39%
Support: $176.04-$176.64; then $166.05 and $156.06
Resistance: $178.46; verified high $180.78; then $194.77
RSI: near 46 on provided chart; unverified
Breakout Target: $180.78 and then $194.77
Breakdown Target: $176.04
FAQ: Has Amazon Committed to Spend $60 Billion?
No. The $60 billion amount is a potential commercial payment/order/purchase commitment level and does not represent guaranteed revenue.
FAQ: What Level Would Confirm QCOM's Recovery?
A move and close above the chart resistance at $178.46 and the high at $180.78 from 10/13, would be constructive.
Bottom Line
Considering the mixed verdict for Arm Holdings and the announcement for Amazon and Qualcomm regarding their partnership for AI, we remain bullish for QCOM but remain mindful of the handset division and shrinking margins. I am cautiously bullish for QCOM but would like to see $176.04 hold support on a daily close.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.