


Tesla Stock Forecast: China Rebound and AI Chip Ambitions Put Margins in Focus



AI Podcast


Tesla enters its October 21 earnings report with stronger international sales and Q3 deliveries beating consensus at 486,532 vehicles. However, strategic expansions into autonomy and the Terafab AI semiconductor facility introduce substantial capital expenditure risks. While energy storage installations missed targets, automotive volume recovery supports near-term momentum. Technically, the stock maintains a bullish bias above $368.84, with a sustained close above the $384.59 resistance required to trigger further upside toward $399.98. Investors will closely monitor upcoming margins, free cash flow, and profitability amid rising AI investments.

TradingKey - As Elon Musk pushes the company into new, and perhaps risky, frontiers like autonomy, robotics and semiconductor manufacturing, Tesla’s vehicle business is starting to show better signs of life. TSLA closed at $382.70 on 10/9, up 2.05% from the previous session. The focus is now on the October 21 earnings report to see if the recently improved volumes result in improved margins and cash flow.
China Sales Accelerate as Europe Extends Its Rebound
Tesla’s Shanghai plant sold 95,366 Made-in-China Model 3/Y in September, including exports. That is up 5% Y/Y after August’s 3.6% gain.
Europe is also looking up. September registrations rose 61.9% in France, 38.4% in Sweden, 24.8% in Spain, and 128.3% in Portugal. What I find interesting is the momentum in multiple markets.
Q3 Deliveries Beat Consensus
Tesla recorded deliveries of 486,532 vehicles in Q3, including 478,237 Model 3/Y units and 8,295 other vehicles. The company produced 464,391 vehicles in the quarter. The deliveries results beat the company-sponsored sell side consensus of 461,974 vehicles and the 456,896 Visible Alpha estimate cited by Reuters.
Q3 deliveries were up 1.3% from the previous quarter at 480,126, but down 2.1% from the record set in the same quarter in 2025. To match the company's 2025 full-year deliveries, deliveries in Q4 need to reach 311,448.
Tesla Assisted Driving Keeps Europe as a Software Catalyst
While Tesla is pursuing broader regulatory approvals for Full Self-Driving, it is changing the name to “Tesla Assisted Driving” for several website versions across Europe.
So far, eight of the 27 EU member countries have granted some form of permission for the technology, with Slovakia expected to be the ninth. A vote on the rest of the EU has been delayed to at least December. The service would expand a higher-margin software opportunity, and while that future revenue is not assured, it would be prudent to consider it as part of the company's longer-term growth potential.
Terafab Expands the AI Thesis and Capital Burden
Tesla is expected to build and run the TeraFab AI semiconductor fabrication facility in Texas with SpaceX. Musk mentioned that TSMC may sublease part of the facility, with Intel, a current project partner, participating as well.
It aligns with Tesla’s strategy with Autonomy and AI Compute, but it adds another huge capital project. Tesla said in their Q2 filing to expect 2026 capital expenditures in excess of $25 billion.
Q2 Shows Why Margins Matter
Tesla reported Q2 revenue of $28.24 billion with $20.52 billion of automotive revenue. Tesla’s GAAP operating income decreased to $398 million from $923 million a year earlier. Automotive gross margin excluding regulatory credits was approx. 16.3% based on automotive revenue and cost disclosures.
Tesla reported $8.28 billion of capital expenditures in the first half of 2026 and ended the quarter with $43.52 billion of cash, cash equivalents and short-term investments.
Energy Storage Adds Growth, but Misses Consensus
Tesla installed 13.7 GWh of energy storage in Q3, up from 13.5 GWh in Q2. While the upgrade is positive, consensus within the sell side of the company was 15.9 GWh, so the actual result fell short.
October 21 Earnings Put Profitability at Center Stage
Tesla is expected to release Q3 results after the market close on Wednesday, October 21. The results will be followed by a management discussion. Results for deliveries have already been released, so the focus is on automotive margins, free cash flow, profitability of energy storage and spending on AI as well as guidance for Q4.
What would strengthen my view is evidence that the recovery in vehicle shipments is helping to finance the AI investments, without a further significant negative impact on profitability.
Tesla Technical Analysis: $384.59 Breakout Could Open $399.98
Tesla closed at $382.70, rebounds from $355.04 and reclaimed the 61.8% Fibonacci retracement level of $368.94. The daily structure remains constructive in the upper boundary of the ascending channel. What catches my attention is that Tesla returned to the $384.59 resistance.
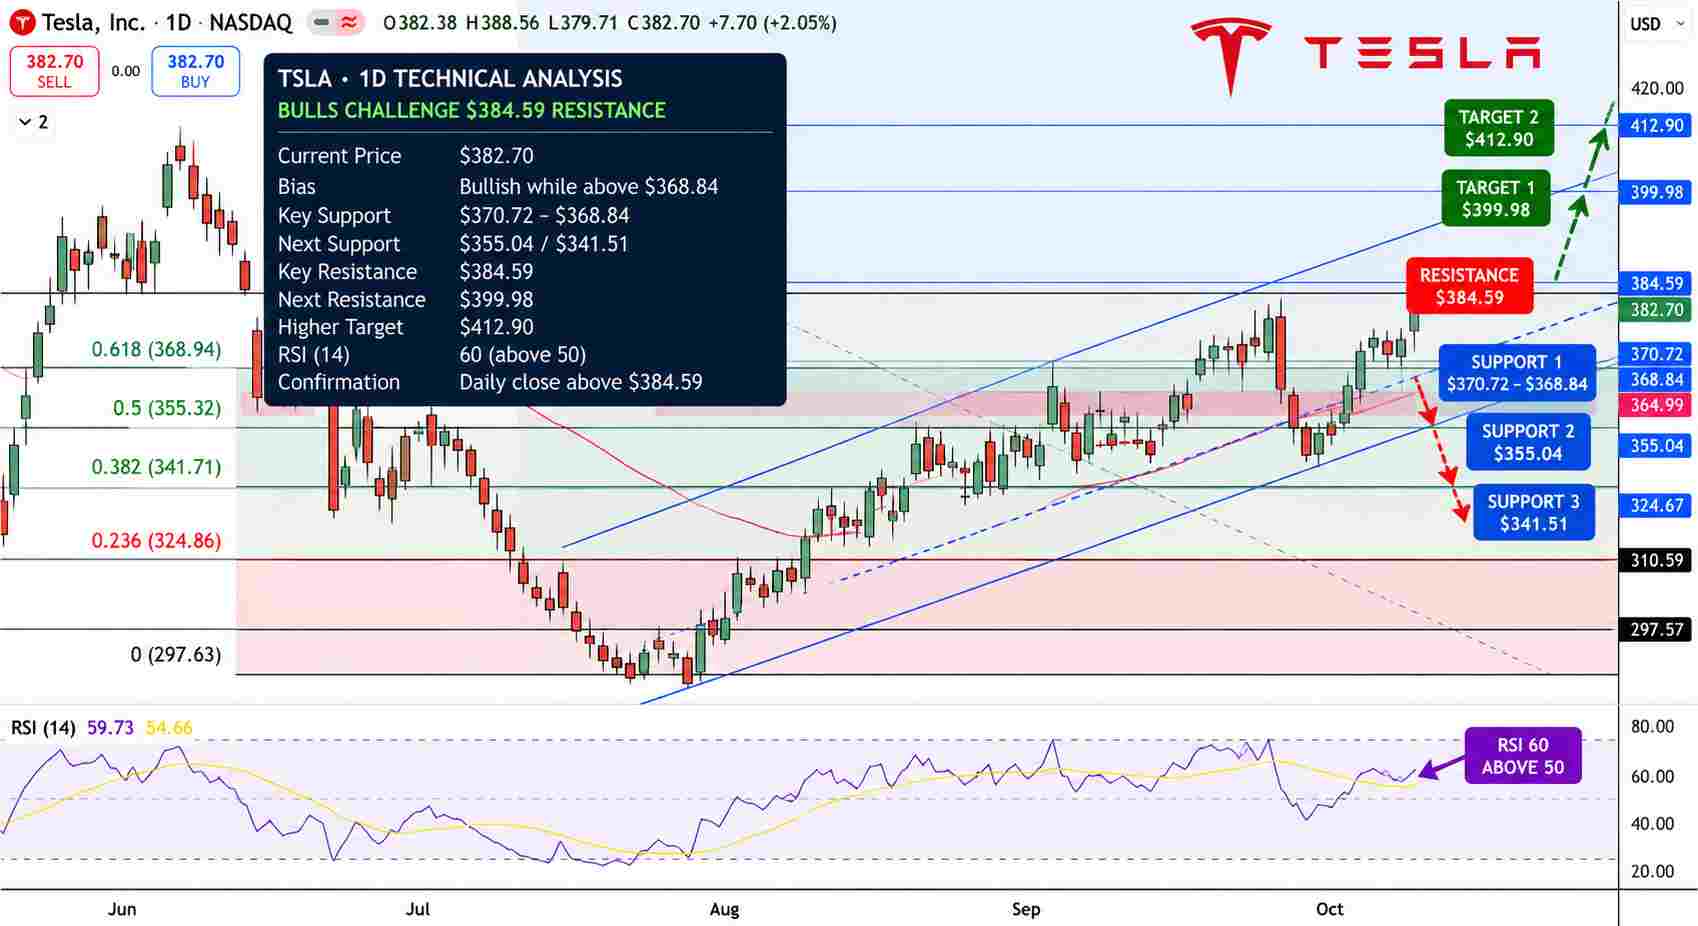
Tesla Stock Price Chart - Source: Tradingview
Rising RSI near 60 above the signal line near 55, suggests improving momentum without reaching overbought levels. A sustained daily close above the $384.59 resistance will build the bullish structure and will expose the $399.98 and $412.90 levels. The support levels are located at $370.72 to $368.84, followed by the 50-day moving average at $364.99.
My bias will remain bullish as long Tesla stays above $368.84 to $370.72. A close below these levels will place the $355.04 and $341.51 levels in focus.
Key Levels
Latest completed close: $382.70
Major Support Levels: $370.72 to $368.84, $364.99, $355.04, $341.51
Major Resistance Levels: $384.59, $399.98, $412.90
RSI: around 60
Recovery/Breakout Trigger: Sustained daily close above $384.59
Breakdown Trigger: Break below $368.84
FAQs
Why is Tesla stock in focus now?
Tesla is in focus for a few reasons. Q3 deliveries beat estimates. China and some Europe markets are improving. Earnings on Oct. 21st will show how margins and cash flow look as AI spending increases.
What technical level would confirm a stronger Tesla recovery?
A close above $384.59 would confirm a stronger recovery in the short term. In the long term, the recovery would be confirmed by closes above $399.98, and then $412.90. The short term recovery would be invalidated by a close below $368.84.
Bottom Line
Tesla is headed into the Oct. 21st earnings with several things going in its favor including positive vehicle deliveries and improving international sales. Rising competition in AI is pushing the focus from demand to economic questions. Long term, options like Tesla Assisted Driving and Terafab are positive but carry regulatory and capital risks. The chart is positive as long as it stays above $368.84 and $370.72. The key level to breakout and confirm a longer term recovery is $384.59.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.