


SanDisk Stock Forecast: Rosenblatt $2,400 Call Meets $1,949 Breakout Target



AI Podcast


SanDisk Corporation closed at $1,887.04 following Rosenblatt Securities' initiation with a $2,400 price target. Driven by artificial intelligence and soaring data center demand, SanDisk reported strong Q4 results, with revenue surging to $8.97 billion and gross margins expanding to 84.6%. Fiscal first-quarter 2027 guidance anticipates continued sequential growth. Long-term customer agreements improve bit demand visibility and reduce cyclicality risks. Despite low forward valuation multiples, primary risks include potential industry oversupply from Asia and China, alongside slowing AI storage demand. Technically, the stock remains bullish above $1,830 support, targeting resistance at $1,949.
TradingKey - SanDisk Corporation (NASDAQ: SNDK) closed at $1,887.04 on Tuesday, a 6.82% gain, after Rosenblatt Securities initiated coverage with a price target of $2,400 and a buy rating. Investors have bid up SanDisk’s stock this year on the trend of artificial intelligence (AI) and the need for higher density non-volatile memory (NAND) flash storage, which SanDisk has a substantial amount of exposure to. The concern is where SanDisk will be in two to three years when we expect the memory industry to be significantly less profitable.
Rosenblatt Says AI Is Changing NAND Economics
Rosenblatt's Cassidy says the industry is beginning to view NAND as more of a system-on-a-chip component as opposed to a simple commodity, due to increasing needs for performance, endurance, and reliability.
Rosenblatt expects SanDisk’s data center revenues to increase over the next two years.
While I do not expect the $2,400 price target to be realized, I believe the assessment of NAND as AI infrastructure is spot on, and it could create a more profitable cycle for the memory manufacturers.
Q4 Shows How Powerful the Current Cycle Has Become
SanDisk reported Q4 revenue of $8.97 billion, up 51% from the prior quarter. Management noted that roughly two-thirds of the increase was due to higher average selling prices and one-third was due to increased volume.
SanDisk’s Q4 gross margins improved to 84.6% from 78.4% in Q3 and 26.2% in Q4 of last year. For the full year, SanDisk reported revenue of $20.25 billion, up 175% from last year.
Data Center Is the Core AI Growth Engine
In Fiscal 2026, SanDisk’s Data Center segment revenues grew by 437% and became an important growth engine for the company.
There are several factors contributing to growing demands of data centers and AI. AI systems retrieve model weights and embeddings multiple times and datasets become large over time. SanDisk expects the demand for data center flash memory to reach about 1.2 zettabytes by 2030.
SanDisk has exposure to AI without competing with large moat players in the space and it is one of the reasons why industry participants believe NAND memory will transition to a primary infrastructure of the data center.
Q1 Guidance Points to Another Step Higher
Given SanDisk’s exposure to AI and strength in data center flash memory, the company remains well positioned to benefit from increasing demand from data centers and AI.
SanDisk expects revenue between $10.3 billion and $10.8 billion and non-GAAP EPS between $44 and $46 for fiscal first quarter of 2027.
At the mid-point of the guidance, SanDisk expects revenue to grow by ~18% from the previous quarter. The next quarterly report is currently estimated around November 5th, 2026, but SanDisk has not formally announced the date. I suggest investors focus on potential upside for revenues and gross margins for the quarter. Continued growth in the data center business and strong business conditions to support the results should be positive for SanDisk.
Long-Term Agreements Could Reduce Cyclicality
During their recent investor day, SanDisk announced New Business Model (NBM) agreements with 8 customers covering approximately 50% of anticipated bit shipments for FY2027, and roughly two-thirds for FY2028.
These agreements establish contracted bit volume, provide SanDisk with financial assurance, and establish pricing mechanisms.
While these agreements do not eliminate the memory cycle, they improve SanDisk’s visibility on bit demand, and reduce the risk the company sells bit volume at uncompetitive prices during a memory bit cycle downside.
QLC and HBF Add More AI Optionality
SanDisk and Kioxia recently announced a ninth-generation 2Tb QLC 3D NAND technology in August 2026; no sampling date was published with the announcement. The ninth-generation 2Tb QLC reaches a 4.8 Gb/s interface speed, about 33% faster than the eighth-generation 2Tb QLC technology.
SanDisk and SK Hynix are also jointly developing High Bandwidth Flash (HBF), with SanDisk’s latest Investor Day roadmap pointing to first HBF inference product samples in 2027. Like HBM, HBF has the potential to place large capacities of flash memory next to compute units, and significantly reduce the use of DRAM for some AI inferencing workloads.
Until HBF or High Bandwidth Memory (HBM) are more broadly adopted, I’ll consider the risk of investment in SanDisk largely offset by optionality.
Valuation Looks Cheap Only if Earnings Hold
Following their addition to the S&P 100 on September 21st, SanDisk trades for just over $1,887.04, giving it a market cap of $276 billion.
Currenlty, StockAnalysis shows SanDisk at a trailing P/E multiple of about 25.6 and a forward multiple of about 8.8.
The forward multiple is very low considering the recent rally in SanDisk's share price. Investors should be mindful that the forward multiple could expand should SanDisk's memory cycle expectations remain aligned.
Oversupply Is Still the Main Fundamental Risk
Gross margins of over 80% for NAND manufacturers are nearly unheard of and are aggressively enticing for new capacity expansion.
The main threats are the introduction of additional memory supplies from Asia, additionalmemory production from China, and sagging demand for storage from AI applications.
These would change my perspective. In the absence of these threats, I will look for other reasons to change my perspective, specifically, increased supply and slower demand for data center storage. Increased supply from various players and new demand for data storage would sustain my outlook.
SanDisk Technical Analysis: SNDK Breaks $1,830 as Bulls Target $1,949
SanDisk Corporation (SNDK) broke above the key level of $1,830 and bulls are looking for a move towards the next resistance at $1,949.
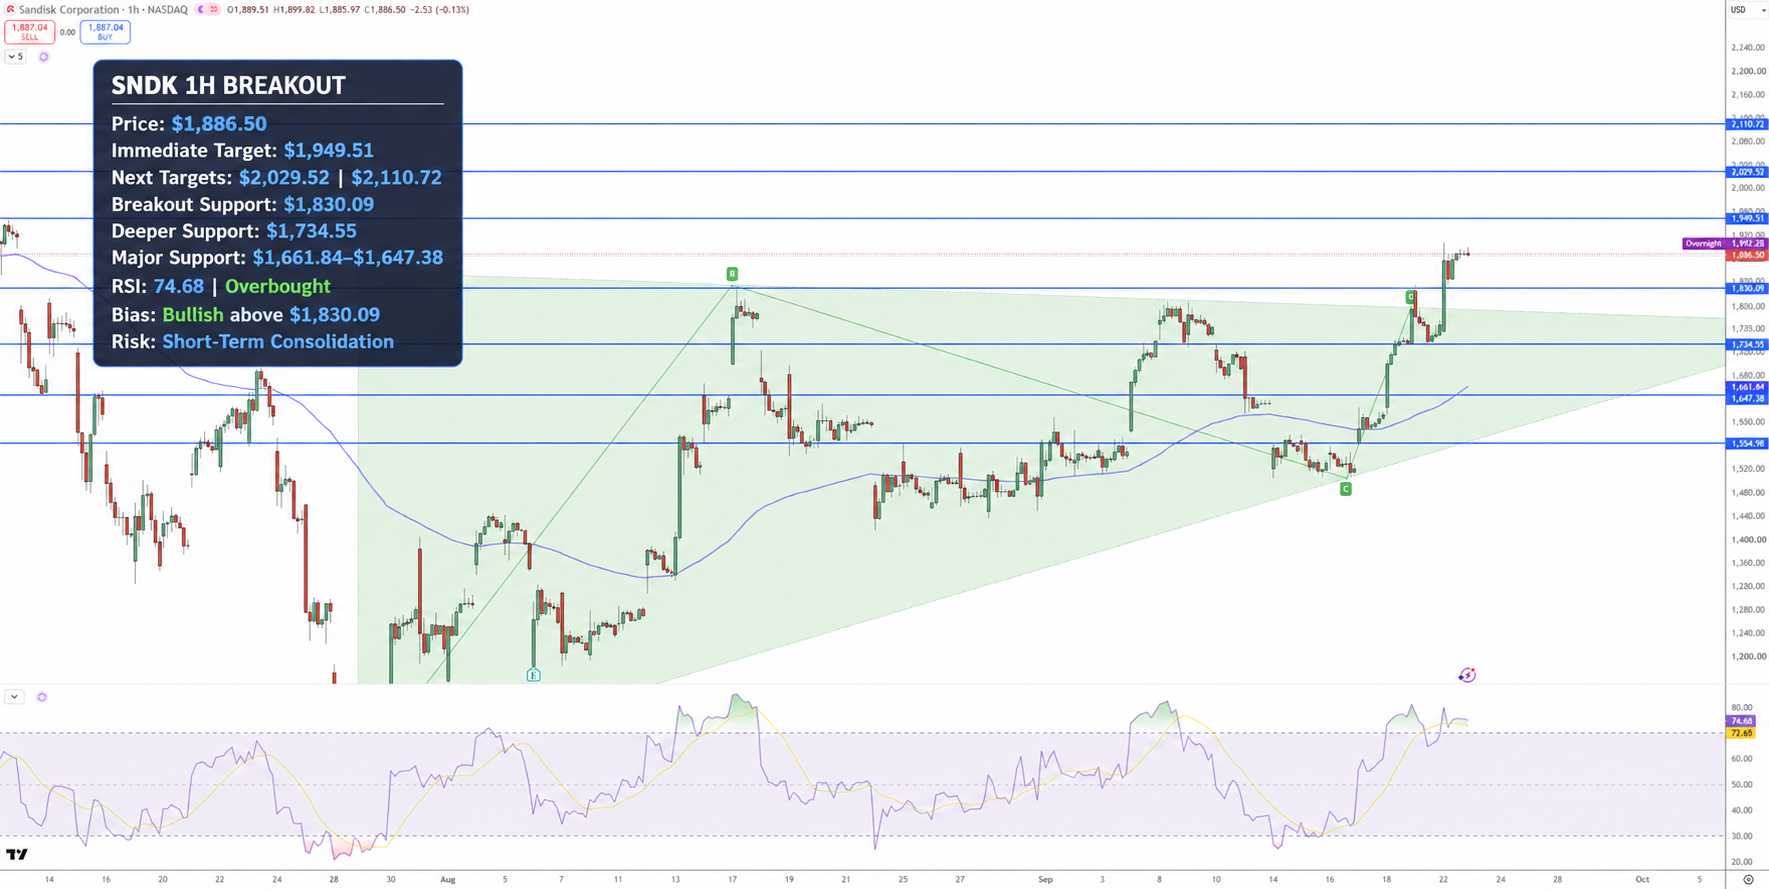
SanDisk Stock Price Chart - Source: Tradingview
As of the writing of this analysis, the latest closing price of SanDisk was $1,887, just above its chart reference at $1,886.50. The one hour chart of SanDisk is bullish with the 50 SMA and 100 SMA in a bullish crossover. The one hour 200 SMA is also above the other moving averages.
The relative strength index (RSI) is at 75. 73 is the signal line and 30 is the oversold line. With RSI being above 70, it indicates an overbought condition and a potential pullback.
The bullish target is $1,949.51. A move above $1,949 would open the way for a move towards $2,029 and $2,110. $1,830 is the support and a break below that would lead to a pullback towards $1,734 and then lower towards $1,662 and $1,647.
I am bullish as long as the price is above $1,830. A break and close above $1,949 would open the way for a move towards $2,029.
Key Levels
• Key Resistance Levels: $1,949, $2,029, $2,110
• Key Support Levels: $1,830, $1,734, $1,662 and $1,647.
• RSI: 75 - overbought
Why is SanDisk stock in focus now?
SanDisk is getting attention because Rosenblatt initiated coverage with a $2,400 target price, and because of the strength of artificial intelligence (AI) and machine learning (ML) in improving data center workloads and driving stronger than expected earnings.
What level confirms a stronger SNDK breakout?
SNDK broke out on September 22, 2026, when the stock closed above the resistance area of $1,830.09. A clear, hourly, above average close, above the resistance area of $1,949.51, would indicate the next major area of resistance at $2,029.52, would come into play. If the stock were to fall and close below the $1,830.09 breakout level, it would indicate the breakout is no longer valid.
Bottom Line
SanDisk Corporation (NASDAQ: SNDK) remains one of the better named-stocks positions in the NAND and AI data-center storage space. Given SanDisk’s lengthy client contracts, exceptionally high gross margins, and the continued rapid growth of the Data Center space and Artificial Intelligence, the bull case is supported.
SNDK remains bullish as long as it is trading above the $1,830.09 level. We would consider the $2,029.52 level to be the next major upside target should a breakout above the $1,949.51 level play out.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.