


 Discount


Spotify Technology SA Stock (SPOT) Closed Down by 3.63% on Nov 19: What Signal Does It Send?


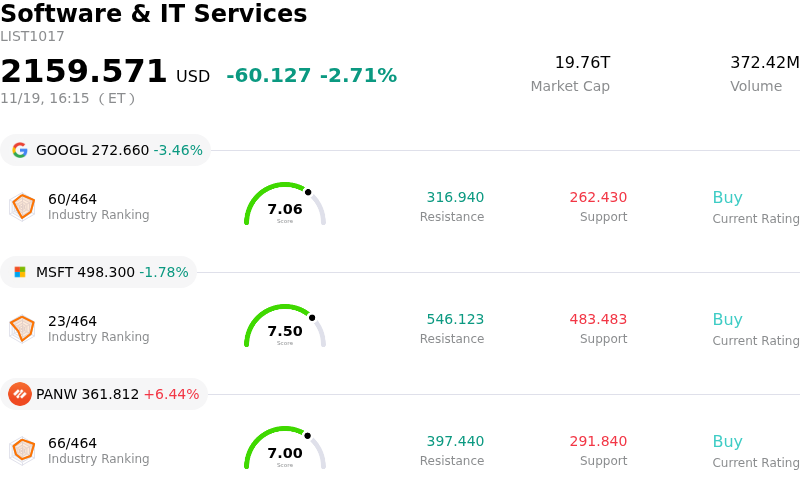
Spotify Technology SA (SPOT) closed down by 3.63%. The Software & IT Services sector is down by 2.71%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) down 3.46%; Microsoft Corp (MSFT) down 1.78%; Palo Alto Networks Inc (PANW) up 6.44%.
What is driving Spotify Technology SA (SPOT)’s stock price down today?
Spotify Technology experienced downward pressure during the trading session, primarily driven by institutional profit-taking, valuation multiple compression following an extended multi-month rally, and broader weakness across high-multiple digital media and communications equities. After testing elevated price territories, the stock faced heightened sensitivity to market-wide de-risking, prompting portfolio managers to lock in gains and adjust risk exposures.
Valuation friction remains a central catalyst behind the recent pullback. Following sustained operational outperformance, cost restructuring, and margin expansion, Spotify’s valuation multiples expanded to levels that leave little room for operational missteps or macro-induced demand softness. At current multiples, institutional investors often reassess the risk-reward profile, particularly when evaluating whether long-term earnings growth can keep pace with multiple expansion. In the absence of an immediate fundamental catalyst, tactical selling and systematic rebalancing frequently trigger retracements toward support levels.
At the industry and operational level, ongoing market scrutiny surrounding content licensing and long-term gross margin ceilings continues to create underlying friction. Although Spotify has demonstrated commendable discipline by curtailing podcasting overhead and streamlining operating expenses, the market remains acutely sensitive to the structural leverage of major music labels and publishers. Questions regarding royalty rate structures, the sustainability of recurring price hikes across mature developed markets, and the pace of advertising revenue expansion amid broader digital ad volatility continue to generate debate among institutional allocators.
Macroeconomic conditions and sector rotation dynamics also played a contributory role. Shifts in broader market sentiment, driven by evolving interest rate expectations and volatility across the tech complex, disproportionately impacted consumer-facing growth platforms. In risk-off or consolidating macro environments, investors typically rotate capital away from richly valued subscription services toward more defensive sectors or value-oriented equities with higher dividend yields and lower price-to-earnings ratios.
From an institutional perspective, the current retreat reflects a healthy valuation consolidation rather than a deterioration in Spotify’s core operational moat. The platform continues to maintain leading audio streaming market share and robust free cash flow generation. However, in the near term, shares are likely to remain range-bound and sensitive to broader market liquidity and sector sentiment until management provides further evidence of sustained average revenue per user growth, operating margin durability, and new revenue stream ramp-up.
Technical Analysis of Spotify Technology SA (SPOT)
Technically, Spotify Technology SA (SPOT) shows a MACD (12,26,9) value of -6.971, indicating a neutral signal. The RSI at 50.900 suggests neutral condition and the Williams %R at 88.525 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Spotify Technology SA (SPOT)
Spotify Technology SA (SPOT) is in the Software & IT Services industry. Its latest annual revenue is $20.44B, ranking 22 in the industry. The net profit is $2.63B, ranking 22 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $648.23, a high of $784.98, and a low of $460.00.
More details about Spotify Technology SA (SPOT)
Company Specific Risks:
- Stretched Valuation Multiples and Margin Growth Headwinds: Recent institutional downgrades highlight that Spotify is trading at overextended valuation multiples well exceeding 40 times forward earnings, leaving the stock vulnerable to sharp drawdowns given that heavy, fixed revenue-sharing obligations with major record labels place a structural ceiling on gross margin expansion.
- Publishing Royalty Disputes and Bundling Litigation: The company faces ongoing legal risk and potential margin compression stemming from its audiobook bundling strategy, which triggered lawsuits from music licensing bodies alleging improper reclassification of subscription tiers to reduce statutory songwriting and mechanical royalty payouts.
- Constrained Pricing Power Against Big-Tech Streaming Rivals: Sustained competitive pressure from well-capitalized tech ecosystems—such as Apple Music, Amazon Music, and YouTube—limits Spotify's runway for further price hikes in key developed markets, increasing the risk of subscriber churn if subscription fees outpace bundled competitor offerings.
- Ad-Supported Segment Volatility and ARPU Dilution: Spotify continues to experience erratic monetization and soft performance across its free ad-supported tier, exposing the business to digital advertising market fluctuations and threatening blended average revenue per user (ARPU) growth.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.