


 Discount


Deere & Co Stock (DE) Closed Down by 3.08% on Nov 19: What Investors Need To Know


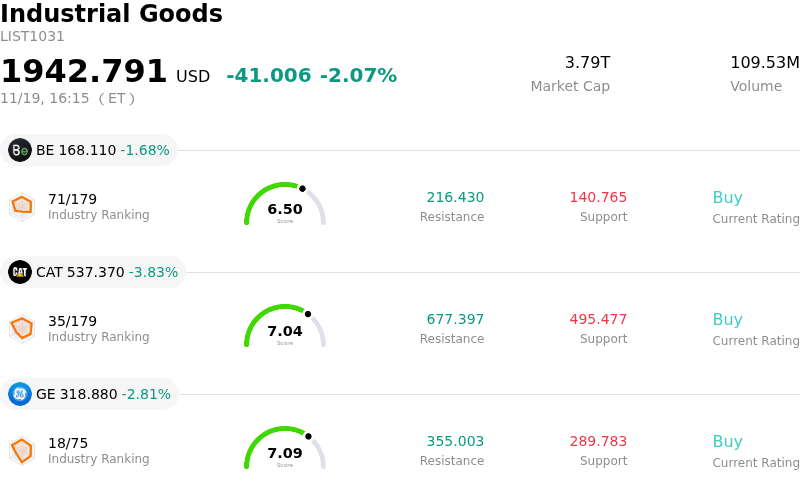
Deere & Co (DE) closed down by 3.08%. The Industrial Goods sector is down by 2.07%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Bloom Energy Corp (BE) down 1.68%; Caterpillar Inc (CAT) down 3.83%; General Electric Co (GE) down 2.81%.
What is driving Deere & Co (DE)’s stock price down today?
Deere and Company faced notable selling pressure as investor sentiment turned defensive ahead of the company's upcoming fiscal fourth-quarter earnings release and annual guidance rollout. With market participants actively de-risking ahead of the critical event, broader concerns surrounding the sustainability of equipment operating margins and demand across agricultural and construction end markets weighed on the stock. Institutional investors appear to be recalibrating expectations, particularly around whether management can provide an optimistic baseline for the coming fiscal year amid ongoing macroeconomic and sector-specific crosswinds.
A central catalyst for the downward movement stems from apprehensions regarding the broader agricultural cycle. Persistently suppressed crop prices and elevated input costs have constrained farm income, dampening replacement demand for large machinery. Compounding these dynamics, high financing costs have continued to discourage farmers from taking on debt for major capital expenditures. Channel checks and peer performance across the agricultural machinery ecosystem have highlighted ongoing dealer inventory discipline and cautious order pacing, raising fears that wholesale tractor and combine shipments will face prolonged headwinds before a cyclical bottom is established.
Margin expectations for the final fiscal quarter also contributed to the pullback. Wall Street analysts and market commentary increasingly noted that sequential profitability could encounter pressure due to the typical fourth-quarter ramp in research, development, and administrative expenditures, combined with the expiration of previous tariff relief and unfavorable product mix. Furthermore, cyclical softness in the construction and forestry segment, driven by broader private non-residential construction moderation, has limited the degree to which non-agricultural divisions can offset weaknesses in precision agriculture.
Finally, broader market sentiment within cyclical industrials turned cautious, prompting institutional portfolio trimming. As volatility expectations rose into the scheduled earnings report, traders adjusted positions to hedge against the potential for conservative forward net income guidance. Until Deere management provides greater visibility into dealer inventory normalization and clear inflection signals for farmer sentiment, the stock remains vulnerable to short-term cyclical skepticism and volatility.
Technical Analysis of Deere & Co (DE)
Technically, Deere & Co (DE) shows a MACD (12,26,9) value of -9.349, indicating a neutral signal. The RSI at 35.998 suggests neutral condition and the Williams %R at 95.264 suggests oversold condition. Please monitor closely.
Media Coverage of Deere & Co (DE)
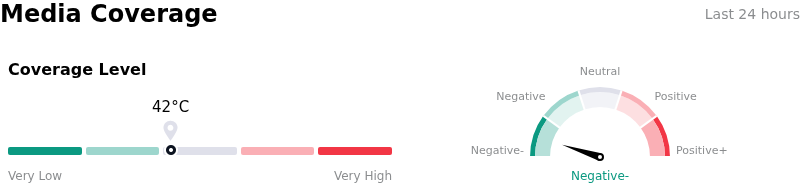
In terms of media coverage, Deere & Co (DE) shows a coverage score of 42, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Deere & Co (DE)
Deere & Co (DE) is in the Industrial Goods industry. Its latest annual revenue is $45.67B, ranking 2 in the industry. The net profit is $5.03B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $681.82, a high of $813.00, and a low of $471.00.
More details about Deere & Co (DE)
Company Specific Risks:
- Sub-Consensus Fiscal 2025 Earnings Guidance: Deere projected full-year fiscal 2025 net income between $5.0 billion and $5.5 billion, falling well short of Wall Street consensus expectations of approximately $5.8 billion and representing an anticipated 23% to 30% drop from fiscal 2024 net income of $7.1 billion.
- Accelerating Revenue and Shipment Volume Declines: Worldwide net sales and revenues contracted 28% year-over-year in the fourth quarter to $11.14 billion, led by a 38% drop in Production & Precision Ag sales due to severe order reductions in large farm machinery like planters and sprayers amid falling crop prices.
- Deteriorating Credit Quality in Financial Services: Financial Services reported reduced earnings driven by an increased provision for credit losses and a valuation allowance on assets held for sale at Banco John Deere S.A., highlighting rising credit default risks and financing stress among farm operators.
- Margin Headwinds from Factory Under-Production: The company's ongoing strategy to aggressively under-produce end-market demand to drain swollen dealer inventories continues to weigh heavily on fixed-cost absorption, suppressing operational leverage and equipment margins across manufacturing facilities.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.