


 Discount


PDD Holdings Inc Stock (PDD) Moved Up by 11.27% on Nov 19: A Full Analysis


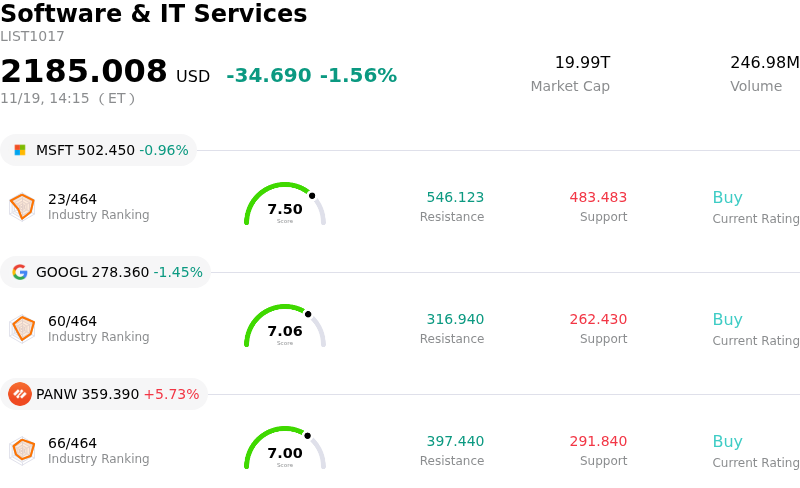
PDD Holdings Inc (PDD) moved up by 11.27%. The Software & IT Services sector is down by 1.56%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 0.87%; Alphabet Inc Class A (GOOGL) down 1.45%; Palo Alto Networks Inc (PANW) up 5.73%.
What is driving PDD Holdings Inc (PDD)’s stock price up today?
PDD Holdings experienced strong upward momentum, largely propelled by robust core marketplace execution and accelerating operational efficiency across its platforms. Investor enthusiasm was revitalized as sustained consumer preference for value-driven retail continues to reinforce Pinduoduo's domestic market share, even amidst an intensely competitive domestic retail landscape. Concurrently, the strategic evolution of its cross-border platform, Temu, toward semi-consignment and local-to-local merchant models has provided tangible evidence of stabilizing fulfillment expenses and mitigating exposure to cross-border regulatory and tariff uncertainties. This operational transition has alleviated market concerns over unconstrained margin compression, proving that international expansion can progress alongside disciplined cost controls and steady take-rate improvements.
Macroeconomic and sector-specific sentiment also provided substantial tailwinds for the shares. Broader optimism surrounding Chinese consumer-facing equities strengthened in response to targeted policy initiatives designed to stimulate domestic retail spending and household demand. Because scalable e-commerce platforms represent the most direct transmission channel for consumer-led recovery, market liquidity rotated aggressively back into digital retail leaders featuring healthy balance sheets and superior free cash flow generation. Against this backdrop, institutional allocators favored PDD as a premier vehicle for playing retail resilience without taking on excessive balance sheet risk.
The upward trajectory was further amplified by institutional portfolio rebalancing and technical short-covering dynamics. Prior to the rally, market sentiment had been heavily weighed down by geopolitical frictions, potential cross-border trade restrictions, and management’s historically cautious commentary regarding near-term profitability. As underlying operational indicators dispelled these worst-case scenarios, a compressed valuation relative to the company's growth rate created an asymmetric risk-reward profile. The resulting wave of institutional accumulation and covering of bearish positioning triggered a sharp valuation re-rating, sustaining intense buying pressure throughout the session.
Technical Analysis of PDD Holdings Inc (PDD)
Technically, PDD Holdings Inc (PDD) shows a MACD (12,26,9) value of 0.414, indicating a neutral signal. The RSI at 64.358 suggests neutral condition and the Williams %R at 9.463 suggests overbought condition. Please monitor closely.
Fundamental Analysis of PDD Holdings Inc (PDD)
PDD Holdings Inc (PDD) is in the Software & IT Services industry. Its latest annual revenue is $62.58B, ranking 9 in the industry. The net profit is $14.18B, ranking 9 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $113.66, a high of $150.00, and a low of $17.56.
More details about PDD Holdings Inc (PDD)
Company Specific Risks:
- Top-Line Stagnation and Substantial Revenue Miss: PDD reported flat year-over-year Q3 revenue of RMB 108.34 billion, missing consensus estimates of roughly RMB 115.2 billion to RMB 116.2 billion by nearly 7%, validating market fears of a structural deceleration from past hyper-growth amid intense domestic e-commerce price wars.
- Cross-Border Tariff Headwinds and Transaction Revenue Contraction: Transaction services revenue, which reflects international marketplace Temu, dropped 12% year-over-year to RMB 48.52 billion (substantially missing analyst forecasts of RMB 58.86 billion), pressured by escalating cross-border regulatory scrutiny and import duties on low-value parcels, such as the European Union's €3 customs surcharge.
- Earnings Quality Compromised by Marketing Retrenchment: Quarterly operating profit growth was predominantly engineered by an unsustainable RMB 5.0 billion reduction in sales and marketing expenditures rather than organic demand expansion, raising red flags that transaction volume and user retention will degrade if customer acquisition subsidies are curtailed.
- Prolonged Margin Compression from Merchant Subsidies: Management reaffirmed that the platform remains in an aggressive "strategic investment phase" focused on funding merchant support programs and absorbing supply chain costs, cementing institutional analyst concerns over forward margin dilution and reduced earnings visibility against aggressive competitive counter-measures from Alibaba and JD.com.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.