


 Discount


Intuitive Surgical Inc Stock (ISRG) Moved Down by 3.15% on Nov 19: Drivers Behind the Movement


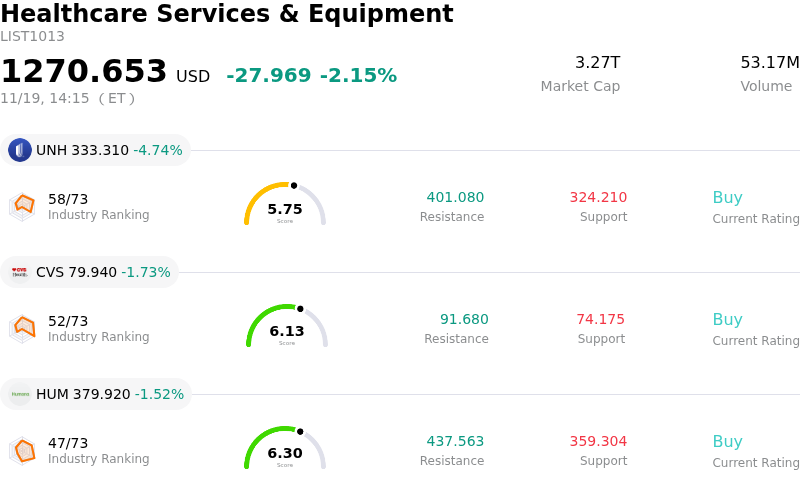
Intuitive Surgical Inc (ISRG) moved down by 3.15%. The Healthcare Services & Equipment sector is down by 2.15%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Unitedhealth Group Inc (UNH) down 4.74%; CVS Health Corp (CVS) down 1.73%; Humana Inc (HUM) down 1.52%.
What is driving Intuitive Surgical Inc (ISRG)’s stock price down today?
Intuitive Surgical encountered notable selling pressure during the session, driven primarily by a confluence of valuation-driven multiple compression, heightened scrutiny over hospital capital expenditure, and institutional portfolio adjustments across the broader medical technology space. As a market leader trading at an elevated premium relative to the wider healthcare sector, the stock remains particularly sensitive to shifting macroeconomic sentiment and broader sector rotations away from high-multiple growth equities.
At the industry and operational level, investor attention has centered on the cadence of hospital capital equipment spending. Healthcare systems continue to navigate budgetary constraints and financing considerations, leading some market participants to question the near-term pace of system placements and upgrade cycles for next-generation robotic platforms, notably the da Vinci 5. While baseline procedural utilization remains solid, any perceived friction in hospital capital approval timelines or extended sales cycles tends to weigh on near-term investor enthusiasm. Additionally, market sentiment continues to monitor procedure mix dynamics, particularly across elective general surgery categories, alongside international market exposure where centralized procurement and tender pacing can introduce revenue timing variability.
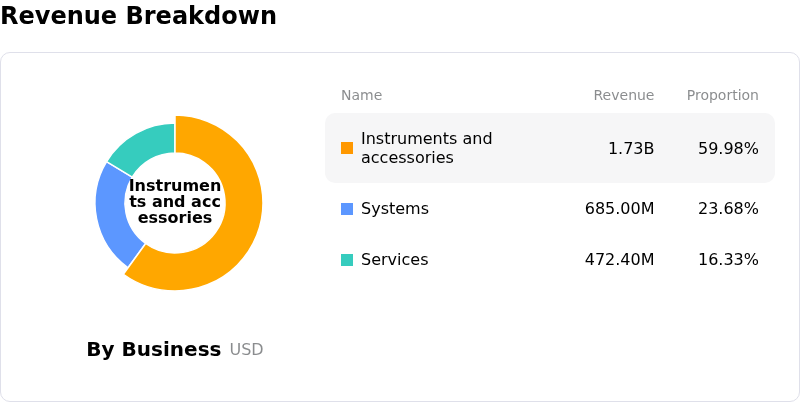
From an institutional positioning perspective, the intraday weakness reflects tactical profit-taking following prior stretches of outperformance. Portfolio managers frequently trim exposure in premium-valuation names during risk-off or sector-rotation phases to reallocate toward more defensive or value-oriented segments of the market. Despite these short-term headwinds, Intuitive Surgical maintains an industry-leading competitive moat supported by its expansive global installed base, a high proportion of recurring revenue generated from instruments and accessories, and significant clinical switching costs. Moving forward, institutional focus will remain on hospital capital budget commitments, procedure volume trajectories across core surgical indications, and customer adoption rates for the latest platform iterations to assess when sentiment will stabilize.
Technical Analysis of Intuitive Surgical Inc (ISRG)
Technically, Intuitive Surgical Inc (ISRG) shows a MACD (12,26,9) value of -12.662, indicating a neutral signal. The RSI at 38.014 suggests neutral condition and the Williams %R at 99.693 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Intuitive Surgical Inc (ISRG)
Intuitive Surgical Inc (ISRG) is in the Healthcare Services & Equipment industry. Its latest annual revenue is $10.06B, ranking 15 in the industry. The net profit is $2.86B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $486.97, a high of $685.00, and a low of $324.00.
More details about Intuitive Surgical Inc (ISRG)
Company Specific Risks:
- Instrument Pricing Reductions and Margin Compression: Management's implementation of planned pricing concessions, spearheaded by mandatory regional price cuts in China and extended-use instrument programs, is projected to erode da Vinci Instrument & Accessories revenue per procedure by 3% to 5% through 2027, while escalating competition from third-party device remanufacturers threatens recurring cash flows.
- Deceleration in Core U.S. Procedure Trajectory: Wall Street firms have lowered price targets following signals of a procedure volume slowdown in the United States toward approximately 10%, which prompted conservative full-year guidance maintenance alongside emerging reimbursement headwinds tied to shifting Affordable Care Act exchange coverage.
- Antitrust Settlement Overhang and GAAP Earnings Drag: The company remains exposed to execution risk following a massive $450 million pre-tax antitrust litigation settlement charge that suppressed GAAP diluted EPS by $0.99, leaving legal uncertainty intact until the agreement receives formal court approval.
- Technical Breakdown and Heightened Insider Selling: Intraday downside pressure accelerated after the stock breached its 200-day moving average ($428.75), triggering algorithmic liquidations that were compounded by ongoing executive and director share disposals executed under pre-arranged Rule 10b5-1 trading plans.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.