


 Discount


Booking Holdings Inc Stock (BKNG) Moved Down by 3.34% on Nov 19: Facts Behind the Movement


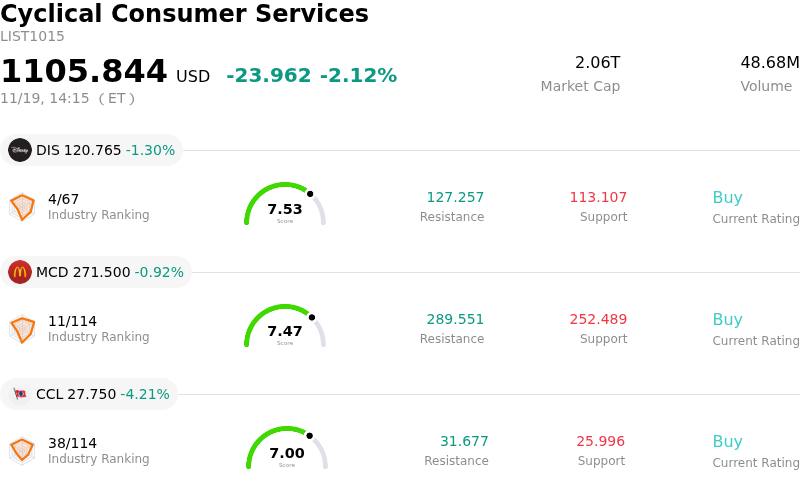
Booking Holdings Inc (BKNG) moved down by 3.34%. The Cyclical Consumer Services sector is down by 2.12%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Walt Disney Co (DIS) down 1.29%; McDonald's Corp (MCD) down 0.92%; Carnival Corp (CCL) down 4.21%.
What is driving Booking Holdings Inc (BKNG)’s stock price down today?
Booking Holdings experienced downward pressure during the trading session as a confluence of macroeconomic concerns, consumer discretionary softening, and industry-specific headwinds weighed on investor sentiment across the online travel sector.
A primary driver behind the pullback is escalating concern over the durability of global consumer travel spending. Following several quarters of robust post-pandemic leisure demand, broader macroeconomic data points toward an increasingly stretched consumer base, particularly in key European and North American markets. Higher cumulative inflation, lingering interest rate pressures, and broader economic uncertainty have led travelers to moderate discretionary outlays, shorten trip durations, or trade down to lower-tier accommodations. Because Booking Holdings generates a significant majority of its gross bookings from international markets, particularly across Europe, any signs of consumer caution in these regions disproportionately dampen expectations for room-night growth and average daily rates heading into the upcoming travel quarters.
Currency fluctuations have also introduced operational frictions. The persistent relative strength of the U.S. dollar against major European currencies poses a recurring translation headwind for multinational travel platforms. Because Booking Holdings reports its consolidated financial statements in dollars while generating substantial booking volume in euros and British pounds, foreign exchange volatility compresses reported revenue expansion and creates margin drag that investors often penalize during broader market risk-off rotations.
From an industry and competitive standpoint, market participants remain attentive to shifting unit economics and marketing efficiency. Rising digital customer acquisition costs and heightened bidding competition across paid search and metasearch channels continue to challenge performance marketing returns. Concurrently, traditional hotel chains are intensifying direct-booking loyalty campaigns, while alternative accommodation platforms sustain pressure in non-urban and vacation-rental segments. The need for sustained marketing investment to defend market share threatens to constrain operating leverage, especially if top-line gross bookings growth slows.
Regulatory overhang, particularly in the European Union under frameworks such as the Digital Markets Act, continues to present structural uncertainty regarding business practices, parity clauses, and platform distribution rules. In an environment where institutional capital is increasingly sensitive to guidance risk and cyclical exposure, these combined headwinds prompted portfolio managers to trim risk exposure in high-beta travel platforms, contributing to the stock's intraday retreat.
Technical Analysis of Booking Holdings Inc (BKNG)
Technically, Booking Holdings Inc (BKNG) shows a MACD (12,26,9) value of -1.189, indicating a sell signal. The RSI at 37.544 suggests neutral condition and the Williams %R at 98.709 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Booking Holdings Inc (BKNG)
Booking Holdings Inc (BKNG) is in the Cyclical Consumer Services industry. Its latest annual revenue is $26.92B, ranking 2 in the industry. The net profit is $5.40B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $219.73, a high of $267.00, and a low of $150.00.
More details about Booking Holdings Inc (BKNG)
Company Specific Risks:
- Uncertain Monetization of B2B and AI Restructuring: Newly unveiled enterprise initiatives, specifically the consolidated Booking Partner Division and the cross-vertical Vayo AI travel agent, entail elevated technological investments without near-term quantified financial returns, driving analyst concerns over margin dilution.
- Platform Disintermediation from Autonomous AI Ecosystems: Accelerating rollouts of competing frontier generative AI travel tools, including Meta's travel-planning agent Muse, threaten to disintermediate online travel agency search funnels, pressuring customer acquisition costs and direct user traffic.
- Sharp Deceleration in Forward Room-Night Growth: Institutional analysts have revised price targets downward as forward guidance projects room-night growth slowing significantly to 1%–3%, reflecting softer fourth-quarter travel demand, airfare inflation headwinds, and consumer spending fatigue.
- Heightened European Regulatory and Compliance Liabilities: Continued regulatory scrutiny by the European Commission targeting Booking.com's oversight of platform security and fraudulent listings threatens to trigger substantial compliance costs and administrative penalties across core European operations.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.