


 Discount


Arm Holdings PLC Stock (ARM) Moved Up by 3.26% on Nov 18: Drivers Behind the Movement


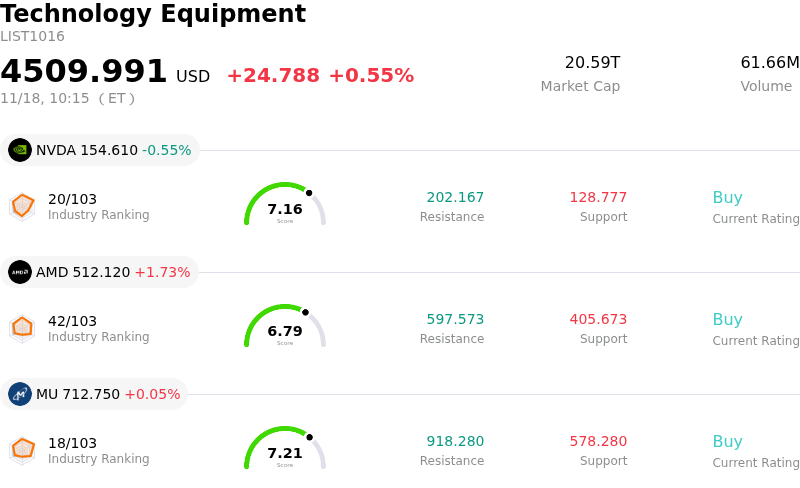
Arm Holdings PLC (ARM) moved up by 3.26%. The Technology Equipment sector is up by 0.55%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 0.48%; Advanced Micro Devices Inc (AMD) up 1.73%; Micron Technology Inc (MU) up 0.07%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced positive intraday momentum driven by broad-based institutional demand for semiconductor intellectual property, underpinned by accelerating market penetration of its advanced compute architectures. Investor optimism continues to center on the transition toward the Armv9 architecture, which commands substantially higher royalty rates relative to previous generations. As tier-one original equipment manufacturers integrate more specialized AI capabilities directly onto silicon, Arm’s compute subsystem offerings have emerged as a high-margin growth catalyst, bolstering confidence in the company’s long-term licensing and royalty pipeline.
A primary structural catalyst supporting today's upside is the expanding deployment of Arm-based processors across hyperscale data centers. With power consumption and thermal management remaining critical bottlenecks for artificial intelligence infrastructure, cloud service providers are increasingly turning to custom, Arm-designed silicon to optimize energy efficiency per watt. Collaborations across leading cloud providers and merchant silicon designers reinforce Arm's positioning beyond traditional mobile form factors, validating its expansion into enterprise servers and accelerating computing platforms.
Industry momentum surrounding edge AI and client computing also contributed to constructive market sentiment. The continued rollout of next-generation AI personal computers and premium mobile chipsets requires greater compute density and heterogeneous processing capabilities, areas where Arm’s high-performance cores maintain a distinct architectural edge. Positive supply chain commentary regarding smartphone replacement cycles and stable component demand has further alleviated lingering concerns regarding consumer hardware headwinds.
From a market strategy perspective, the upward traction reflects constructive institutional positioning within the semiconductor and IP software landscape. While Arm trades at a premium valuation multiple compared to legacy chipmakers, institutional buyers appear willing to support this premium given the defensible nature of its licensing model, expanding margin profile, and broad exposure to both cloud-based and on-device AI workloads. In the near term, investors will continue to monitor royalty growth rates, the ramp of custom silicon solutions, and broader macroeconomic factors influencing corporate enterprise technology budgets.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of 3.115, indicating a neutral signal. The RSI at 42.643 suggests neutral condition and the Williams %R at 42.544 suggests buy condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
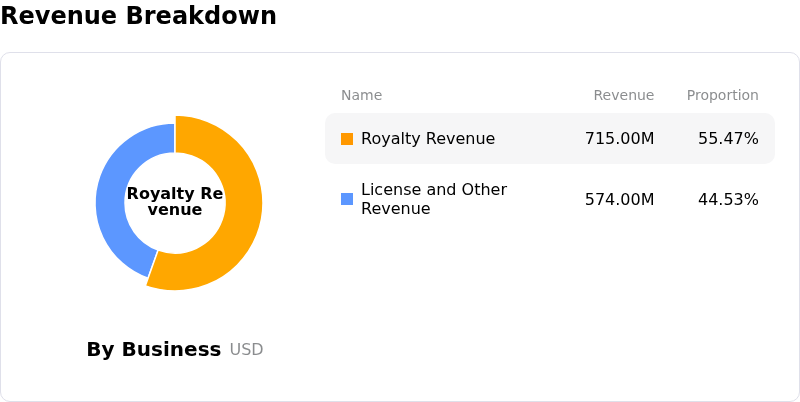
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Royalty Revenue Deceleration and Smartphone Exposure: Recent analyst commentary following the fiscal Q2 earnings cycle emphasizes vulnerability in recurring royalty growth, which slowed to just 8% year-over-year due to smartphone end-market sluggishness and elevated component pricing, underscoring that strong upfront architecture licensing is not yet translating smoothly into high-volume recurring cash flows.
- Gross Margin Dilution from In-House Hardware Transition: Institutional investors remain wary of the strategic pivot toward designing and shipping first-party AGI CPUs and custom subsystems, an operational shift that exposes the business to component inventory risk and dilutes Arm's high-margin (~98%) pure-play intellectual property model down toward lower hardware gross margins (projected at 30% to 40%).
- Supply Chain and Advanced Node Packaging Bottlenecks: Fulfilling medium-term delivery commitments of up to $2 billion in proprietary compute subsystems leaves the company disproportionately exposed to tightening advanced-node foundry capacity and advanced packaging allocations at third-party foundries, creating immediate execution and shipment delay risks.
- Extreme Valuation Multiple and High-Beta Vulnerability: Despite recent forecast revisions, Wall Street coverage highlights that Arm continues to carry an elevated forward earnings multiple that leaves no room for operational missteps, causing severe intraday price swings as capital rotates within semiconductor infrastructure and macro rates remain restrictive.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.