


 Discount


Palo Alto Networks Inc Stock (PANW) Moved Up by 6.77% on Nov 18: Key Drivers Unveiled


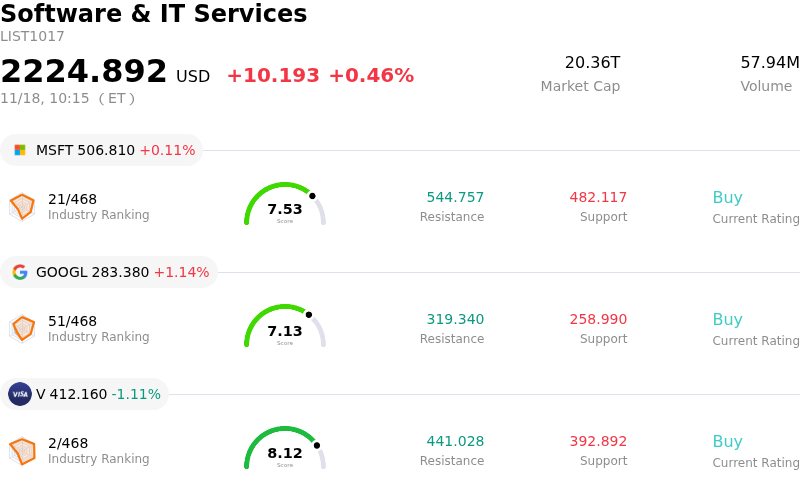
Palo Alto Networks Inc (PANW) moved up by 6.77%. The Software & IT Services sector is up by 0.46%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) up 0.18%; Alphabet Inc Class A (GOOGL) up 1.06%; Visa Inc (V) down 1.09%.
What is driving Palo Alto Networks Inc (PANW)’s stock price up today?
Palo Alto Networks experienced strong upward momentum during the session, driven by aggressive institutional accumulation and a relief rally ahead of its highly anticipated fiscal quarterly financial release. The stock had previously endured notable valuation compression, slipping into oversold territory following a multi-week retreat across high-multiple enterprise software names. With sentiment reaching cautious extremes, short covering combined with proactive dip-buying by institutional investors looking to position for durable execution across mission-critical cybersecurity infrastructure.
The primary catalyst supporting investor confidence centers on the company's platformization strategy. As enterprises increasingly seek to rationalize IT budgets and replace fragmented, multi-vendor point solutions with unified security architectures, Palo Alto Networks continues to capture outsized market share. The market is rewarding evidence of sustained growth in next-generation security annual recurring revenue, anchored by robust adoption of the Cortex security operations platform, cloud security offerings, and expanded identity capabilities. Expectations for resilient remaining performance obligations and healthy contract expansions have helped offset lingering concerns over broader enterprise spending scrutiny.
Broader industry dynamics also provided a favorable tailwind, as high-profile cyber threat activity and regulatory mandates continue to preserve cybersecurity as an insulated priority within corporate capital expenditures. Concurrently, investor enthusiasm surrounding generative artificial intelligence security tools has reinforced Palo Alto Networks' technological moat. Market participants view the company as uniquely positioned to monetize AI-driven automated threat detection and incident response at scale, shielding it from competitive encroachment by specialized niche vendors.
Favorable analyst commentary and defensive rotation into large-cap software balance sheets further amplified the advance. Wall Street has largely maintained constructive long-term outlooks, emphasizing the company's sustained operating leverage and robust free cash flow conversion. While the company's premium forward valuation remains a focal point of debate, today's price action reflects a distinct sentiment pivot toward operational resilience and structural secular growth over near-term macroeconomic hesitation.
Technical Analysis of Palo Alto Networks Inc (PANW)
Technically, Palo Alto Networks Inc (PANW) shows a MACD (12,26,9) value of -3.345, indicating a sell signal. The RSI at 44.737 suggests neutral condition and the Williams %R at 66.073 suggests sell condition. Please monitor closely.
Media Coverage of Palo Alto Networks Inc (PANW)
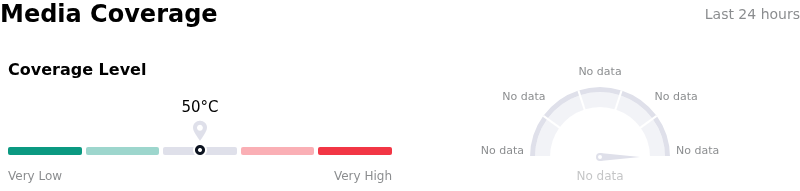
In terms of media coverage, Palo Alto Networks Inc (PANW) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Palo Alto Networks Inc (PANW)
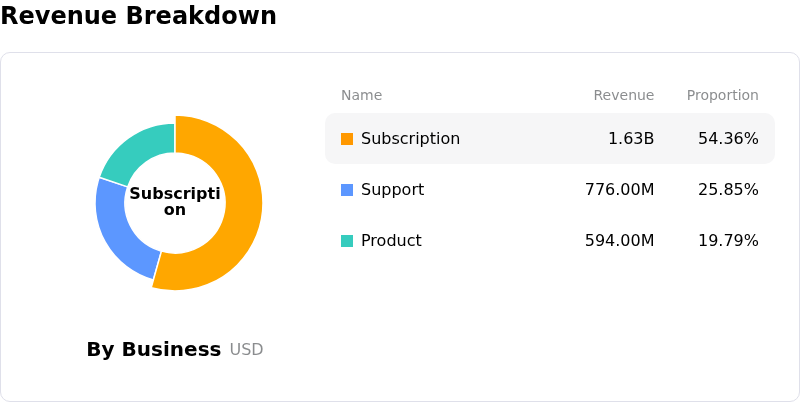
Palo Alto Networks Inc (PANW) is in the Software & IT Services industry. Its latest annual revenue is $11.48B, ranking 34 in the industry. The net profit is $307.00M, ranking 90 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $401.69, a high of $525.00, and a low of $190.00.
More details about Palo Alto Networks Inc (PANW)
Company Specific Risks:
- Earnings Binary Event Risk and Implied Volatility: Heading into its fiscal Q1 earnings announcement scheduled after today's market close, options markets are pricing in an implied swing exceeding 10%, exposing the stock to aggressive intraday de-risking if net new Annual Recurring Revenue (ARR) or forward billings guidance fail to beat elevated whisper numbers.
- Valuation Multiple Compression Following Price Target Cuts: Trading at an extreme earnings multiple, the equity faces ongoing valuation sensitivity triggered by institutional target reductions, including Jefferies lowering its price target from $450 to $400, reinforcing concerns that near-term platformization gains are fully priced in.
- Platformization Monetization and Margin Pressure: Intensified bundling and multi-product platform migration strategies risk contract concessions and deferred revenue recognition, raising concerns among institutional analysts that extended enterprise sales cycles could compress operating margins and cash flow conversion.
- Geopolitical and Overseas Regulatory Friction: Heightened regulatory scrutiny and compliance reviews of foreign enterprise cybersecurity hardware and software in international jurisdictions create persistent contract renewal overhangs for multinational deployments.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.