


ASML Holding NV Stock (ASML) Moved Down by 3.02% on Nov 17: What Investors Need To Know


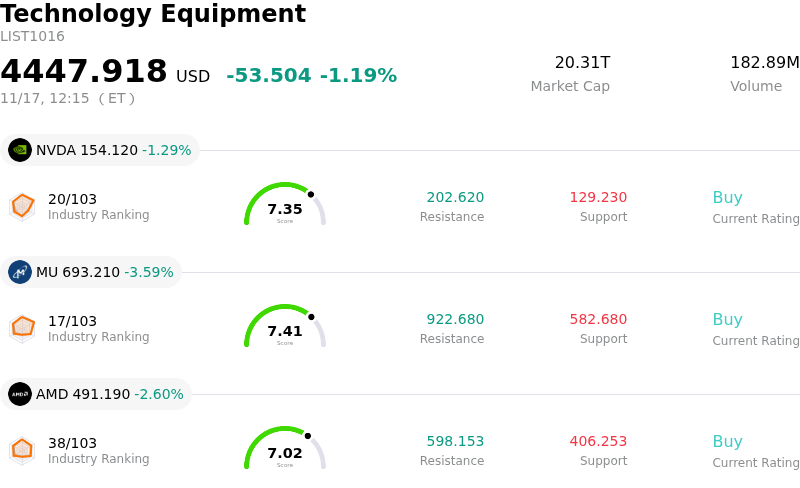
ASML Holding NV (ASML) moved down by 3.02%. The Technology Equipment sector is down by 1.19%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 1.43%; Micron Technology Inc (MU) down 3.73%; Advanced Micro Devices Inc (AMD) down 2.72%.
What is driving ASML Holding NV (ASML)’s stock price down today?
ASML faced noticeable downward pressure during the trading session, primarily driven by heightened scrutiny around semiconductor equipment trade policies and cross-border export restrictions. Institutional investors continue to recalibrate exposure amid shifting geopolitical dynamics, where tighter licensing frameworks on advanced immersion lithography tools threaten future regional order intake. Given that shipments to Chinese fabs have represented a substantial portion of recent tool deliveries, any prospective regulatory tightening directly clouds medium-term revenue visibility and dampens market sentiment.
Compounding this headwind are evolving capital expenditure strategies among key global chipmakers. While leading-edge artificial intelligence infrastructure investments remain resilient, legacy and consumer-oriented segments such as personal computing, mobile handsets, and automotive semiconductors are navigating an uneven recovery. Consequently, tier-one foundries and integrated device manufacturers have demonstrated heightened capital discipline, selectively pushing out fab construction timelines and adjusting delivery schedules for advanced lithography platforms. This measured procurement approach raises near-term concerns regarding net bookings momentum and overall backlog conversion.
From a market strategy perspective, broader sector rotation away from high-multiple semiconductor equipment equities amplified the downward move. High baseline valuations across premium technology hardware suppliers left the stock vulnerable to profit-taking, particularly as investors navigated macroeconomic uncertainty and shifting bond yield trajectories. While ASML retains an undisputed technological moat through its monopoly in extreme ultraviolet lithography, institutional market participants are adopting a cautious posture until clearer evidence of a broader industry capex inflection and regulatory stability materializes.
Technical Analysis of ASML Holding NV (ASML)
Technically, ASML Holding NV (ASML) shows a MACD (12,26,9) value of -16.775, indicating a sell signal. The RSI at 33.833 suggests neutral condition and the Williams %R at 97.237 suggests oversold condition. Please monitor closely.
Fundamental Analysis of ASML Holding NV (ASML)
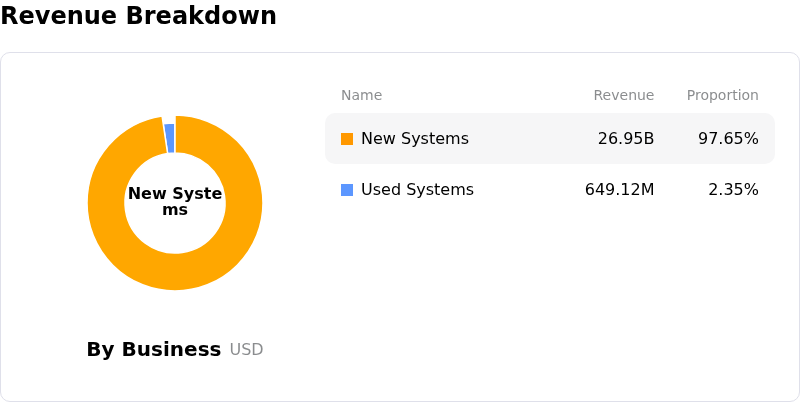
ASML Holding NV (ASML) is in the Technology Equipment industry. Its latest annual revenue is $36.83B, ranking 8 in the industry. The net profit is $10.83B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2203.99, a high of $2858.00, and a low of $1450.00.
More details about ASML Holding NV (ASML)
Company Specific Risks:
- Regulatory and Export Restriction Exposure: Heightened trade scrutiny and new export licensing restrictions imposed by the U.S. and Dutch governments on advanced lithography tools—particularly immersion DUV systems—pose an immediate threat to high-margin tool shipments and installed-base servicing revenue across the critical Chinese market.
- AI Infrastructure Digestion and Capex Volatility: Broader tech-sector volatility and emerging risk-off sentiment across artificial intelligence hardware leaders have triggered contagion selling, driving institutional analyst concerns that leading foundry clients could pause or push out capital expenditure commitments for next-generation EUV machinery.
- Manufacturing Capacity and Tool Delivery Bottlenecks: Analyst reviews indicate that planned production capacity expansion for Low-NA EUV and DUV systems through 2027–2028 risks falling short of surging fab schedules, creating operational friction, delivery delay risks, and customer pressure to explore architectural alternatives.
- Institutional Position Trimming and Multiple Contraction: Recent disclosures indicating stake reductions by prominent European asset managers have intensified intraday liquidation, exacerbating multiple compression on the company's valuation premium during broader semiconductor supply chain selloffs.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.