


Arm Holdings PLC Stock (ARM) Opened Up by 3.58% on Nov 17: Key Drivers Unveiled


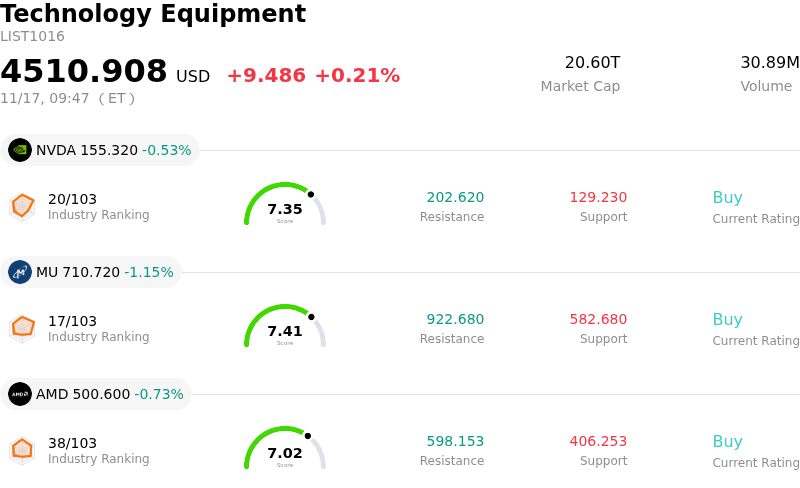
Arm Holdings PLC (ARM) opened up by 3.58%. The Technology Equipment sector is up by 0.21%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 0.39%; Micron Technology Inc (MU) down 1.42%; Advanced Micro Devices Inc (AMD) down 1.02%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced notable upward momentum during the session, driven by broad-based institutional accumulation across leading semiconductor and artificial intelligence infrastructure equities. Investor appetite was invigorated by mounting confidence in the company's multi-year licensing trajectory and accelerating royalty rate capture, particularly as hyperscalers and chipmakers expand deployments based on the advanced Armv9 architecture. Because Armv9 commands substantially higher royalty rates than its predecessor architecture, the sustained transition toward cutting-edge compute subsystems across both cloud data centers and premium edge devices continues to serve as a high-margin revenue engine, supporting strong intraday bid activity.
Compounding this architecture upgrade cycle is the structural expansion of custom silicon among Tier-1 cloud service providers. Hyperscalers facing severe power constraints and rising operational expenditures are increasingly prioritizing energy-efficient, proprietary server processors built upon Arm compute platforms. Sustained enterprise capital expenditure commitments toward artificial intelligence infrastructure have reinforced market expectations that Arm-based data center market share will continue to scale meaningfully. Furthermore, growing penetration across the client personal computing ecosystem and software-defined vehicle platforms provides additional validation of the company's addressable market diversification beyond its historical mobile core.
From a market strategy perspective, the upward price movement was further bolstered by constructive analyst sentiment and institutional reallocations into high-conviction semiconductor intellectual property providers. Investors continue to appreciate Arm's differentiated asset-light business model, which allows the company to monetize structural artificial intelligence compute demand without bearing the direct fabrication capital intensity, yield vulnerabilities, or balance sheet inventory risks that burden traditional device manufacturers. While elevated valuation multiples and broader macroeconomic volatility remain pertinent risk factors, Arm's robust royalty visibility and foundational positioning across modern compute architectures continue to attract sustained risk-on capital.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of 1.519, indicating a neutral signal. The RSI at 39.301 suggests neutral condition and the Williams %R at 73.032 suggests sell condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
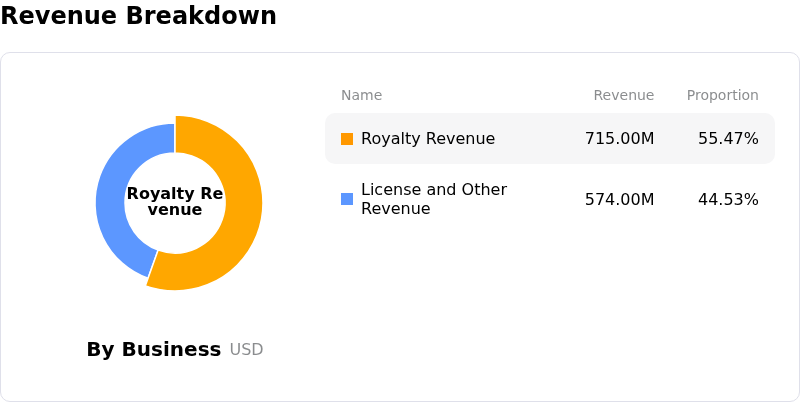
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Decelerating Royalty Growth and End-Market Exposure: Recent financial disclosures revealed royalty revenue increased only 8% year-over-year to $670 million, missing Wall Street expectations of approximately $720 million as elevated component pricing dampened global smartphone shipments, highlighting a widening lag between upfront design licensing and high-margin recurring volume monetization.
- Margin Compression from Proprietary Hardware Pivot: Arm's transition from a pure-play intellectual property licensor into manufacturing first-party data center silicon (Arm AGI CPUs) has driven research and development costs up 24% to $857 million and reduced quarterly free cash flow to $110 million, raising concerns among institutional analysts that capital expenditures and 30%–40% hardware margins will dilute Arm's core ~98% gross margin profile.
- Contract Breach Ruling and Qualcomm Royalty Overhang: A federal jury ruling that Arm breached its Architectural License Agreement and intentionally interfered in partner operations has intensified legal overhang, leaving Arm exposed to ongoing judicial review over whether its largest customer can seek to freeze royalty payments under contractual penalty clauses.
- Valuation Headwinds and Related-Party Licensing Scrutiny: Following modest fiscal Q3 guidance, institutional analysts lowered price targets while highlighting elevated multiples and dependence on parent company SoftBank for large licensing commitments, triggering multiple compression as high-beta semiconductor names face systematic de-risking.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.