


Southern Copper Corp Stock (SCCO) Moved Down by 5.19% on Nov 16: Drivers Behind the Movement


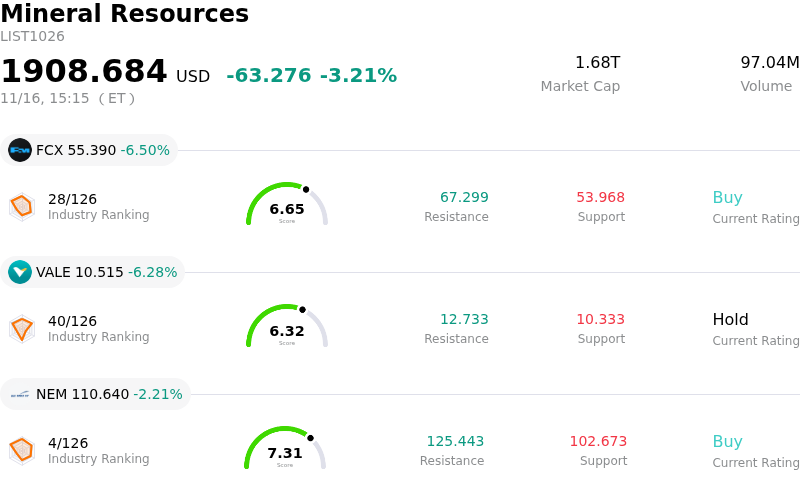
Southern Copper Corp (SCCO) moved down by 5.19%. The Mineral Resources sector is down by 3.21%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Freeport-McMoRan Inc (FCX) down 6.50%; Vale SA (VALE) down 6.24%; Newmont Corporation (NEM) down 2.16%.
What is driving Southern Copper Corp (SCCO)’s stock price down today?
Southern Copper Corporation experienced pronounced selling pressure as a convergence of deteriorating commodity pricing, macroeconomic headwinds, and sector-wide risk aversion weighed heavily on the base metals complex. As one of the lowest-cost, pure-play global copper producers, the company maintains high operational leverage to prevailing refined copper spot and futures prices. Consequently, a sharp pullback in physical and exchange-traded copper contracts directly compressed near-term cash flow expectations, sparking immediate multiple de-rating across the mining sector.
A primary catalyst behind the downturn is the macroeconomic environment, particularly the persistent strength of the U.S. dollar alongside shifting global interest rate expectations. A firmer greenback historically dampens appetite for dollar-denominated raw materials by making procurement more costly for international buyers. Compounding this currency pressure are ongoing demand concerns stemming from leading manufacturing centers, especially China, where sluggish industrial activity, property sector headwinds, and uneven infrastructure spending have suppressed global refined copper consumption. Because market participants view copper as an essential gauge of global economic vitality, signals of prolonged manufacturing softness invariably trigger defensive capital reallocations out of cyclical materials.
Jurisdictional and operational dynamics in Latin America also continue to introduce an elevated risk premium for Southern Copper. With primary mining and smelting operations concentrated in Peru and Mexico, the company remains structurally sensitive to regional political developments, community relations, and ongoing discussions surrounding mining royalties and environmental compliance. When top-line metal realizations decline, institutional investors tend to scrutinize jurisdictional and cost risks more critically, leading to accelerated profit-taking and reduced exposure to assets with exposure to emerging-market regulatory friction.
From a portfolio strategy and market mechanics perspective, institutional positioning exacerbated the downward trajectory. Cyclical mining equities faced systematic de-risking as asset managers rotated out of high-beta industrial commodities and into defensive sectors or fixed income instruments. Downward revisions in short-term average realized selling prices and cautious analyst sentiment further dampened trading volume support. While Southern Copper retains premier asset quality, extensive reserves, and competitive cash costs, its near-term trading dynamics remain tethered to swings in macroeconomic sentiment and broader base metal price discovery.
Technical Analysis of Southern Copper Corp (SCCO)
Technically, Southern Copper Corp (SCCO) shows a MACD (12,26,9) value of -3.189, indicating a sell signal. The RSI at 30.562 suggests neutral condition and the Williams %R at 98.022 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Southern Copper Corp (SCCO)
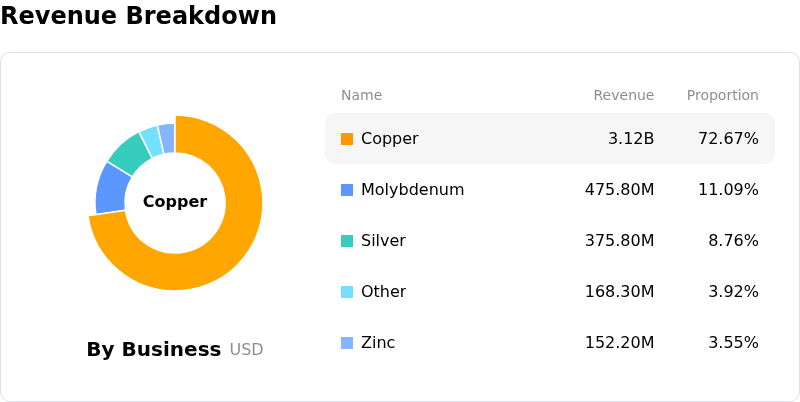
Southern Copper Corp (SCCO) is in the Mineral Resources industry. Its latest annual revenue is $13.42B, ranking 16 in the industry. The net profit is $4.33B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $173.06, a high of $272.12, and a low of $136.60.
More details about Southern Copper Corp (SCCO)
Company Specific Risks:
- Peruvian Production Contraction and Ore Grade Degradation: Deteriorating ore grades across flagship Peruvian operations, including Cuajone and Toquepala, have driven an output drop exceeding 6%, significantly elevating unit extraction cash costs and squeezing mining operating margins.
- Stretched Valuation Multiple and Prevailing Institutional Downgrades: Trading at a premium of over 21x forward earnings and approximately 14x EV/EBITDA against diversified peers, the stock has triggered downgrades and an aggregate consensus "Reduce" rating from Wall Street desks warning of limited upside and heightened vulnerability to valuation compression.
- Exposure to Unwinding AI Infrastructure Premiums and Copper Spot Weakness: Intraday volatility reflects the erosion of the speculative premium previously tied to AI data center electrification demand, leaving the company's high-beta cash flows exposed to falling copper spot realizations caused by high Treasury yields and a strong U.S. dollar.
- Jurisdictional and Permitting Bottlenecks on Greenfield Pipelines: The company's long-term volume replacement targets face execution roadblocks due to persistent social and regulatory friction surrounding major Peruvian capital projects, including Tia Maria and Los Chancas, risking capex overruns and delayed operational timelines.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.