


Analog Devices Inc Stock (ADI) Moved Down by 3.12% on Nov 16: Key Drivers Unveiled


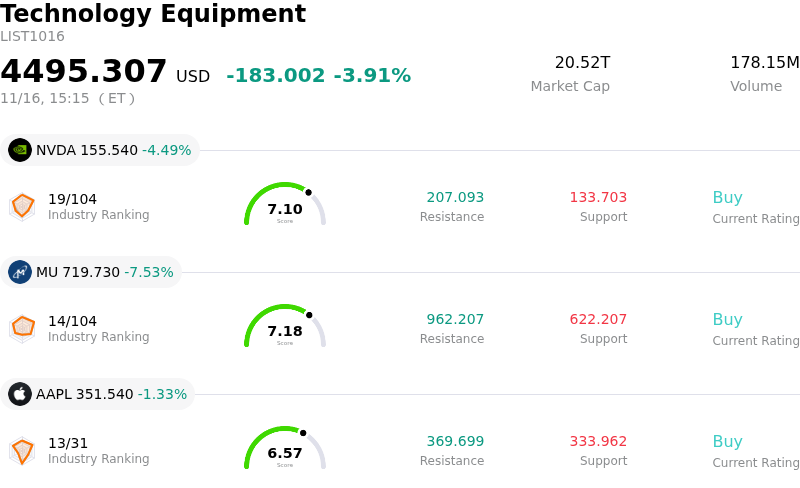
Analog Devices Inc (ADI) moved down by 3.12%. The Technology Equipment sector is down by 3.91%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.43%; Micron Technology Inc (MU) down 7.42%; Apple Inc (AAPL) down 1.31%.
What is driving Analog Devices Inc (ADI)’s stock price down today?
Analog Devices experienced notable downward pressure during the trading session, primarily driven by broader weakness across the semiconductor sector and mounting investor caution surrounding the pace of recovery in core end markets. As an industry bellwether for analog and mixed-signal chips, the company is particularly sensitive to macroeconomic shifts and cyclical trends within industrial automation and automotive applications. A broader risk-off tone across technology equities, coupled with lingering uncertainty over interest rate trajectories and corporate capital expenditure budgets, weighed heavily on high-multiple analog chipmakers throughout the day.
A key factor compounding the retreat stems from ongoing inventory digestion across industrial supply chains. While investors have been anticipating a synchronized cyclical rebound, channel checks and peer commentary within the broader semiconductor ecosystem continue to indicate uneven order patterns and cautious purchasing behavior among tier-one industrial and factory automation clients. The automotive segment, which historically offered a resilient growth cushion, has also faced growing scrutiny as global automakers moderate electric vehicle production targets and manage elevated component stockpiles. These demand dynamics have spurred renewed skepticism regarding how quickly utilization rates and gross margins can expand over the coming quarters.
Pre-earnings positioning also played a significant role in today’s pullback. With the company approaching its quarterly financial release, institutional market participants often rebalance risk exposure and pare back positions, particularly in names facing near-term visibility headwinds. Analysts have maintained a watchful eye on forward guidance, given that management commentary will be critical in confirming whether the analog inventory trough is firmly in the rearview mirror or if order stabilization will extend further into upcoming quarters.
From an institutional standpoint, the pullback reflects disciplined derisking rather than a fundamental breakdown in the company's long-term competitive moat. Analog Devices maintains high customer retention, substantial free cash flow generation, and exposure to long-term secular themes such as digital healthcare, advanced driver-assistance systems, and edge artificial intelligence. Nevertheless, in the near term, elevated sensitivity to macroeconomic indicators and conservative corporate guidance across enterprise technology continue to leave the shares vulnerable to tactical profit-taking and sentiment-driven volatility.
Technical Analysis of Analog Devices Inc (ADI)
Technically, Analog Devices Inc (ADI) shows a MACD (12,26,9) value of -3.629, indicating a neutral signal. The RSI at 44.853 suggests neutral condition and the Williams %R at 61.937 suggests sell condition. Please monitor closely.
Fundamental Analysis of Analog Devices Inc (ADI)
Analog Devices Inc (ADI) is in the Technology Equipment industry. Its latest annual revenue is $11.02B, ranking 18 in the industry. The net profit is $2.27B, ranking 14 in the industry. Company Profile
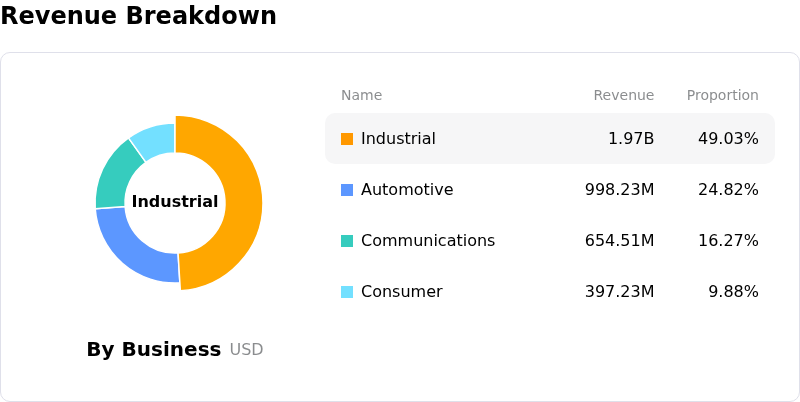
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $470.13, a high of $675.00, and a low of $315.00.
More details about Analog Devices Inc (ADI)
Company Specific Risks:
- Pre-Earnings Guidance Vulnerability: Heading into the upcoming fiscal fourth-quarter earnings release, institutional commentary has highlighted a decelerating beat magnitude and diminishing upside surprises over recent quarters, leaving the stock acutely sensitive to conservative forward guidance if distributor demand and channel inventories normalize.
- Stretched Valuation and Multiple Compression Exposure: Trading at elevated valuation multiples of approximately 29x EV/EBITDA and more than 40x earnings, analysts warn that expectations have priced in an aggressive AI data center narrative that outpaces the company's historical single-digit organic revenue growth rate, exposing shares to rapid multiple contraction during tech sell-offs.
- Margin Compression from Rival 300mm Fab Expansions: Aggressive capacity additions and 300mm wafer fabrication ramps by primary competitor Texas Instruments have heightened pricing competition across standard industrial and analog power-management sockets, posing a direct threat to ADI's gross margin resilience.
- Cyclical End-Market Headwinds in Industrial and Automotive Sectors: Despite expansion in data center optical and power semis, more than half of ADI's revenue base remains concentrated in broader automotive and industrial applications, where ongoing global manufacturing softness and prolonged customer order digestion continue to cap cyclical recovery momentum.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.