


 Discount


ASML Holding NV Stock (ASML) Opened Down by 3.69% on Nov 16: Key Drivers Unveiled


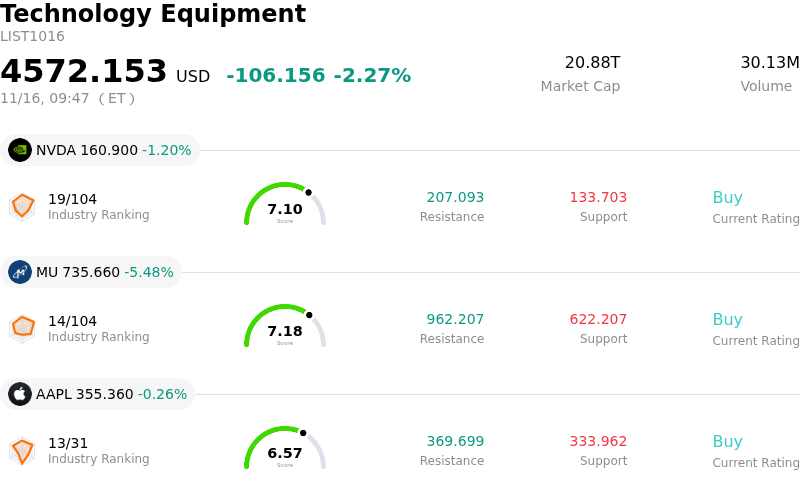
ASML Holding NV (ASML) opened down by 3.69%. The Technology Equipment sector is down by 2.27%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 1.20%; Micron Technology Inc (MU) down 5.48%; Apple Inc (AAPL) down 0.28%.
What is driving ASML Holding NV (ASML)’s stock price down today?
ASML faces pronounced downward pressure as renewed geopolitical scrutiny and heightened trade restrictions continue to weigh heavily on investor sentiment across the semiconductor capital equipment sector. Institutional market participants remain increasingly cautious regarding tighter export controls imposed by Dutch and U.S. regulatory authorities on advanced immersion deep ultraviolet lithography systems. With China having contributed a substantial share of tool shipments and order intake over recent quarters, persistent regulatory overhang and the anticipation of further licensing constraints create structural headwinds for future backlog conversion and regional revenue durability.
Industry-level dynamics further compound this negative price action. While artificial intelligence-related demand remains resilient, the broader recovery across legacy end markets, including smartphones, personal computing, automotive, and industrial electronics, continues to progress unevenly. Leading global foundry and memory manufacturers have maintained a disciplined stance toward capacity expansion, actively optimizing fab construction timelines and deferring non-essential tool installations. This cautious capital expenditure environment has heightened market sensitivity around ASML's net bookings trajectory, prompting analysts and portfolio managers to recalibrate their medium-term equipment delivery schedules.
From a macroeconomic and market strategy standpoint, broader weakness across high-multiple semiconductor peers has exacerbated the decline. Fluctuations in benchmark bond yields and shifting monetary policy expectations have triggered tactical portfolio de-risking and rotation out of premium-valued technology leaders. Because ASML commands a valuation premium underpinned by its technological moat in extreme ultraviolet lithography, any incremental uncertainty regarding wafer fab equipment spending leaves the stock susceptible to multiple compression. The convergence of heightened geopolitical friction, cautious customer capex, and institutional profit-taking underpins the prevailing downward momentum.
Technical Analysis of ASML Holding NV (ASML)
Technically, ASML Holding NV (ASML) shows a MACD (12,26,9) value of -2.849, indicating a sell signal. The RSI at 38.672 suggests neutral condition and the Williams %R at 73.120 suggests sell condition. Please monitor closely.
Fundamental Analysis of ASML Holding NV (ASML)
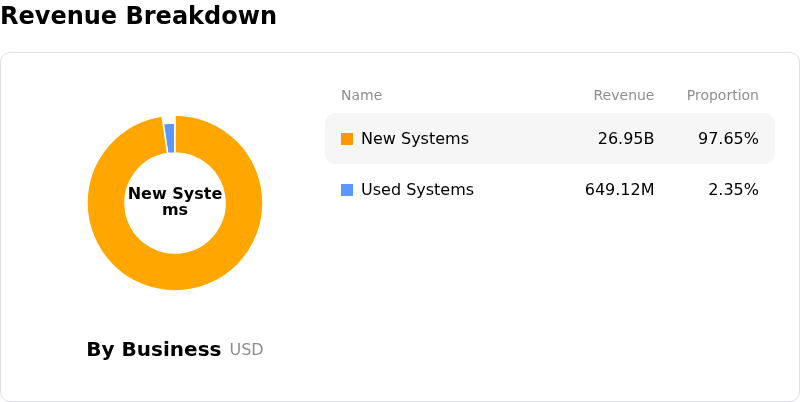
ASML Holding NV (ASML) is in the Technology Equipment industry. Its latest annual revenue is $36.83B, ranking 8 in the industry. The net profit is $10.83B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2203.99, a high of $2858.00, and a low of $1450.00.
More details about ASML Holding NV (ASML)
Company Specific Risks:
- Geopolitical and Regulatory Export Control Exposure: Renewed scrutiny from U.S. and Dutch authorities targeting DUV immersion lithography tool shipments and installed-base maintenance servicing in China threatens a major revenue driver, creating immediate downside risk to projected tool deliveries and lucrative recurring service margins.
- Semiconductor Downside Pressure and Order Deferral Risks: Intraday volatility across the broader semiconductor and AI hardware complex has intensified analyst concerns over wafer fab equipment (WFE) demand, leaving ASML vulnerable to sudden tool delivery pushbacks and order cancellations if leading foundry customers adjust near-term capital expenditure budgets.
- High-NA EUV Commercialization and High Unit-Cost Friction: Extreme capital requirements—exceeding €350 million per unit—and technical insertion complexities for next-generation High-NA EUV systems heighten execution risk, as tier-one customers risk delaying commercial volume adoption during periods of macroeconomic uncertainty.
- Extreme Customer Concentration Vulnerability: ASML's heavy reliance on a small base of key chipmakers (primarily TSMC, Samsung, and Intel) creates severe financial sensitivity, where an operational pause, fab construction delay, or revised node deployment schedule from any single client triggers sharp contractions in quarterly net bookings.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.