


Moderna Inc Stock (MRNA) Moved Down by 5.50% on Nov 12: Drivers Behind the Movement


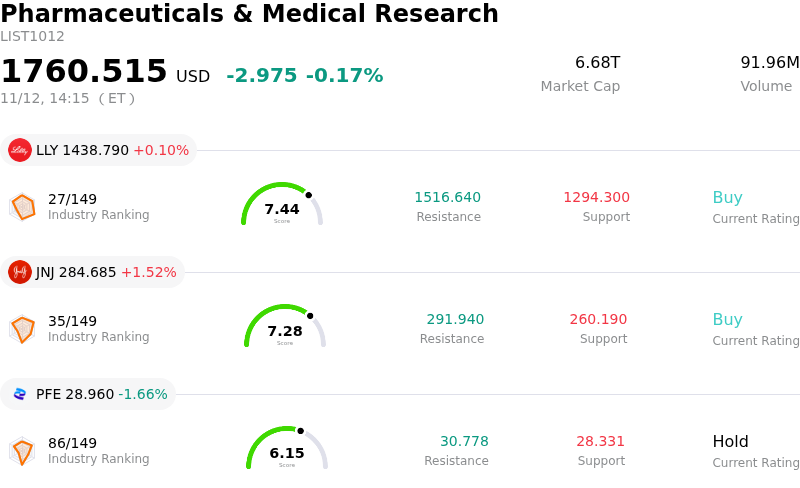
Moderna Inc (MRNA) moved down by 5.50%. The Pharmaceuticals & Medical Research sector is down by 0.17%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) up 0.10%; Johnson & Johnson (JNJ) up 1.52%; Pfizer Inc (PFE) down 1.66%.
What is driving Moderna Inc (MRNA)’s stock price down today?
Moderna experienced notable downward pressure as market participants reacted to the company’s annual Analyst Day presentation, triggering institutional profit-taking following a substantial multi-session rally. While management reiterated an upgraded near-term revenue growth outlook and highlighted operational milestones, the strategic update failed to provide fresh near-term catalysts, leading investors to reassess valuation premiums and long-term cost commitments.
A primary factor weighing on the stock is the capital intensity associated with the company’s multi-year pivot toward oncology. During the event, leadership outlined an extensive mid-term expenditure framework, signaling substantial ongoing annual cash costs through the end of the decade to support late-stage clinical trials, manufacturing automation, and commercial preparation for individualized cancer therapies. Although the company maintains solid liquidity and amended credit terms, institutional investors remain acutely focused on the cash burn trajectory and the extended horizon required to achieve sustainable, self-funded operational profitability.
Compounding the sell-off is persistent skepticism surrounding the durability of the commercial respiratory franchise. While the oncology pipeline, particularly individualized neoantigen therapy in partnership with Merck, has driven strong momentum, commercialized products face structural demand normalization and stiff competition in endemic vaccine markets. Investors continue to debate whether initial launches of next-generation respiratory vaccines can fully bridge the revenue gap before oncology candidates secure regulatory clearances and reach meaningful commercial scale.
Finally, the decline reflects a classic sell-the-news dynamic. With shares having advanced sharply heading into November and trading well above consensus price targets, the risk-reward profile had grown increasingly asymmetric. In the absence of unexpected positive data or accelerated commercial timelines, institutional funds moved to lock in gains, illustrating heightened market sensitivity to valuation multiples and execution risk across clinical-stage pipelines.
Technical Analysis of Moderna Inc (MRNA)
Technically, Moderna Inc (MRNA) shows a MACD (12,26,9) value of -0.359, indicating a neutral signal. The RSI at 54.039 suggests neutral condition and the Williams %R at 44.105 suggests buy condition. Please monitor closely.
Media Coverage of Moderna Inc (MRNA)
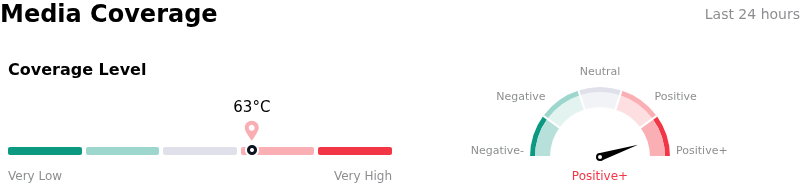
In terms of media coverage, Moderna Inc (MRNA) shows a coverage score of 63, indicating a high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Moderna Inc (MRNA)
Moderna Inc (MRNA) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $1.94B, ranking 39 in the industry. The net profit is $-2.82B, ranking 195 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $143.15, a high of $251.00, and a low of $45.00.
More details about Moderna Inc (MRNA)
Company Specific Risks:
- Extreme Valuation Multiple and Reversal Pressure: Institutional downgrades from brokerages including William Blair and Citigroup emphasize an acute valuation disconnect, with shares trading near 38 times forward sales following a multi-hundred percent rally; analysts warn that future speculative oncology cash flows are being priced years ahead of commercialization, exposing the stock to aggressive multiple compression and profit-taking.
- Pipeline Execution and Clinical Extrapolation Risks: Despite positive melanoma data for intismeran, subsequent trial details from the INTerpath-001 study fell below peak market expectations, and institutional analysts cite significant biological and regulatory hurdles in expanding individualized neoantigen therapy into additional solid tumor indications, compounded by recent late-stage pipeline setbacks such as the norovirus (mRNA-1403) program.
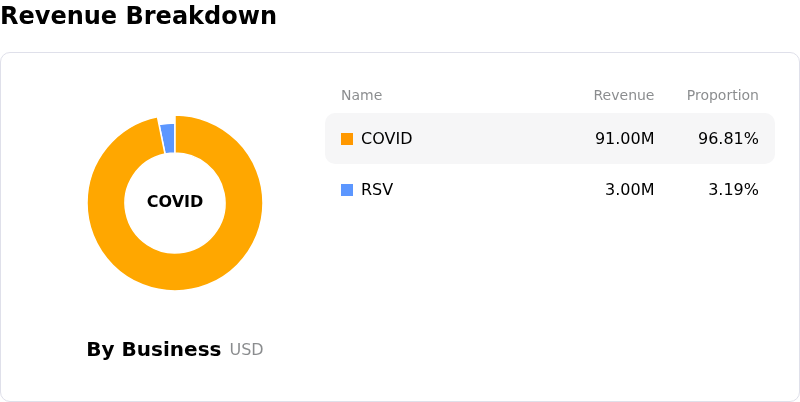
- Revenue Concentration and Respiratory Pricing Headwinds: Operations remain heavily reliant on COVID-19 vaccine deliveries—which represented over 70% of revenue in the third quarter—leaving top-line performance vulnerable to normalized post-pandemic demand and intensifying competitive pricing pressure from Pfizer/BioNTech and Sanofi/Novavax combination flu and COVID-19 candidates.
- Debt-Supported Liquidity and Severe R&D Retrenchment: Recent financial disclosures show that year-end cash projections remain heavily dependent on $2.6 billion in net proceeds from convertible debt financing rather than sustainable organic cash generation, while aggressive plans to slash $1.1 billion from research budgets and discontinue multiple clinical programs officially delay operational break-even targets into 2028.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.