


Summit Therapeutics Inc Stock (SMMT) Moved Down by 7.27% on Nov 12: Drivers Behind the Movement


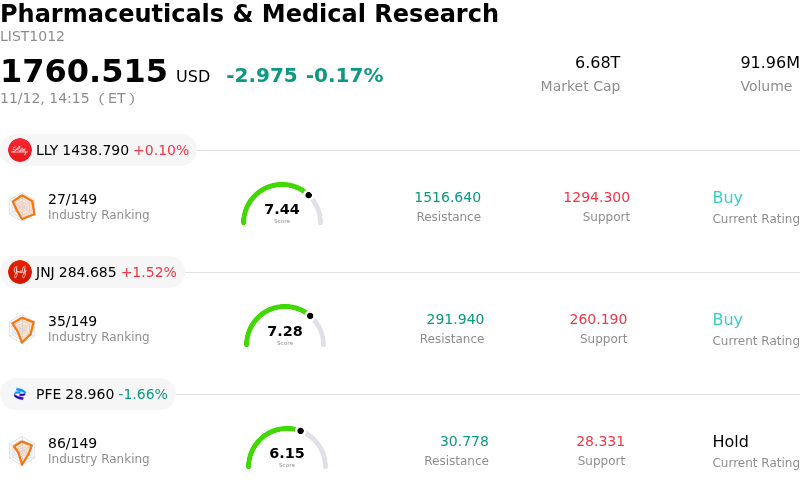
Summit Therapeutics Inc (SMMT) moved down by 7.27%. The Pharmaceuticals & Medical Research sector is down by 0.17%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) up 0.10%; Johnson & Johnson (JNJ) up 1.52%; Pfizer Inc (PFE) down 1.66%.
What is driving Summit Therapeutics Inc (SMMT)’s stock price down today?
Summit Therapeutics experienced downward pressure primarily driven by pre-catalyst de-risking as market participants reduced exposure ahead of the imminent regulatory decision for its lead investigational bispecific antibody, ivonescimab. With the targeted mid-November regulatory action date creating a high-stakes binary event, institutional and retail investors chose to lock in capital and limit portfolio vulnerability. Market caution has centered on the regulatory robustness of the clinical submission, where previous study readouts demonstrated progression-free survival benefits but missed formal statistical significance on overall survival. This historical data gap has amplified uncertainty regarding whether regulatory authorities will accept the surrogate endpoints without mandating more definitive Western overall survival verification.
Anxiety surrounding global clinical execution also contributed to the selling momentum. Investors remain sensitive to the clinical risk profile following earlier interim analyses in pivotal multi-regional Phase III trials, including cohorts within the HARMONi program, which raised questions about whether robust efficacy demonstrated in earlier regional trials can be seamlessly reproduced across broader global populations. Given the intense competitive landscape in advanced non-small cell lung cancer, where entrenched checkpoint inhibitor regimens hold dominant market positions, any perceived ambiguity regarding regulatory approval or comparative efficacy creates outsized downward pressure on pipeline expectations.
Financial realities and capital structure considerations further weighed on sentiment. As a pre-commercial biopharmaceutical company, Summit generates no commercial product revenue and continues to sustain elevated research and development expenses to support extensive late-stage clinical programs. Despite strategic equity backing and co-development alliances with major pharmaceutical partners, high quarterly cash burn and ongoing dilution sensitivities related to share count management have kept valuations under tight scrutiny. In an environment where capital remains highly selective regarding clinical-stage biotechnology risk, these compounded operational expenditures and binary regulatory overhangs triggered an intraday exit of speculative capital into safer holdings.
Technical Analysis of Summit Therapeutics Inc (SMMT)
Technically, Summit Therapeutics Inc (SMMT) shows a MACD (12,26,9) value of 0.215, indicating a neutral signal. The RSI at 47.137 suggests neutral condition and the Williams %R at 67.823 suggests sell condition. Please monitor closely.
Fundamental Analysis of Summit Therapeutics Inc (SMMT)
Summit Therapeutics Inc (SMMT) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $0.00, ranking 520 in the industry. The net profit is $-1.08B, ranking 624 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $29.99, a high of $43.00, and a low of $11.90.
More details about Summit Therapeutics Inc (SMMT)
Company Specific Risks:
- Imminent Binary Regulatory Decision on Ivonescimab: Shares have experienced sharp intraday selling pressure as market participants aggressively de-risk and lock in profits ahead of the FDA's November 14 target action date for lead oncology candidate ivonescimab, exposing the equity to severe binary downside if the agency issues a complete response letter, delays review, or grants a narrower-than-expected label.
- Scrutiny Over Clinical Trial Robustness and Survival Metrics: Institutional investor caution remains elevated over nuanced efficacy data from late-stage trials, specifically regarding whether initial overall survival figures met stringent statistical superiority thresholds and whether demographic homogeneity in pivotal data sets will fully satisfy US regulatory standards for broad commercial indication.
- Pre-Commercial Financial Burn and Elevated Operating Expenses: Following third-quarter financial results, the company continues to generate zero commercial product revenue while incurring heavy quarterly net losses and surging clinical development expenditures, sustaining acute operational cash burn as it concurrently advances multiple registration-enabling trials.
- Stretched Valuation Vulnerability and Dilution Overhang: With the company's valuation hovering above $12 billion following recent volatility and strategic partnership speculation, the stock faces acute multiple compression and heightened overhang from authorized share capital expansions that could dilute existing equity holders.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.