


Global Payments Inc Stock (GPN) Moved Down by 10.24% on Nov 12: Key Drivers Unveiled


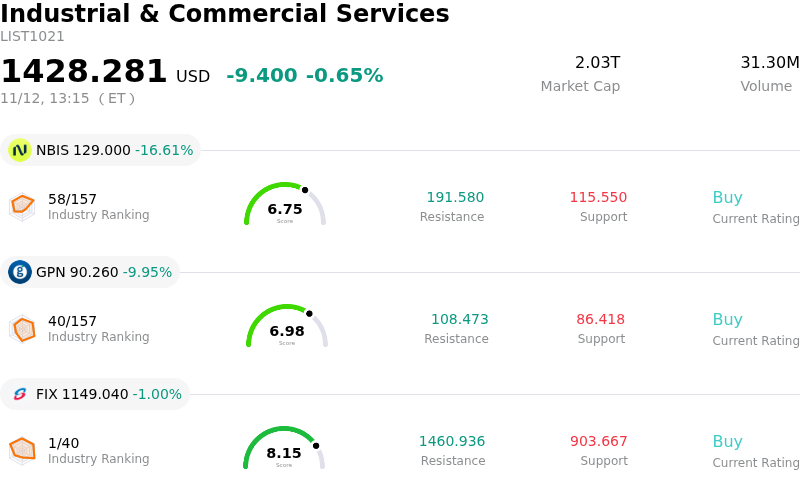
Global Payments Inc (GPN) moved down by 10.24%. The Industrial & Commercial Services sector is down by 0.65%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Nebius Group NV (NBIS) down 16.61%; Global Payments Inc (GPN) down 9.95%; Comfort Systems USA Inc (FIX) down 1.00%.
What is driving Global Payments Inc (GPN)’s stock price down today?
Global Payments experienced a sharp selloff during today's trading session, driven primarily by reports that private equity firms Clayton, Dubilier and Rice and GTCR have terminated their pursuit of a potential takeover of the company. Speculative momentum had recently supported the shares following reports of early-stage acquisition talks, particularly against the backdrop of ongoing activist engagement on the board. However, discussions reportedly fell apart as both buyout sponsors walked away due to the significant structural complexities, elevated financing hurdles, and scale associated with orchestrating a leveraged buyout for a firm with an enterprise value exceeding twenty-five billion dollars.
The collapse of acquisition talks triggered an aggressive unwinding of merger arbitrage and event-driven positions that had been established in anticipation of a transaction. Institutional capital rapidly rotated out of the name, while negative sentiment spilled over into the broader merchant acquiring and payment processing peer group as expectations for private-equity-sponsored consolidation across the fintech sector diminished. The loss of this immediate valuation floor left shares vulnerable to heightened intraday volatility as liquidity providers adjusted bids downward.
With the prospect of a near-term buyout now off the table, investor focus has abruptly reverted to Global Payments' underlying operational fundamentals and risk profile. While the company recently maintained its full-year earnings expectations and highlighted ongoing expense synergies from its Worldpay integration, headwinds persist. Investors remain cautious regarding high leverage from past acquisitions, cyclical exposure to consumer discretionary and travel spending, and relentless competitive pressure from cloud-native point-of-sale and integrated payment competitors. Absent an external take-private catalyst, the company must re-establish market confidence purely through standalone organic execution, debt reduction, and disciplined share repurchases.
Technical Analysis of Global Payments Inc (GPN)
Technically, Global Payments Inc (GPN) shows a MACD (12,26,9) value of 0.957, indicating a buy signal. The RSI at 49.201 suggests neutral condition and the Williams %R at 57.334 suggests sell condition. Please monitor closely.
Fundamental Analysis of Global Payments Inc (GPN)
Global Payments Inc (GPN) is in the Industrial & Commercial Services industry. Its latest annual revenue is $7.71B, ranking 15 in the industry. The net profit is $1.40B, ranking 12 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $105.59, a high of $194.00, and a low of $70.00.
More details about Global Payments Inc (GPN)
Company Specific Risks:
- Collapse of Private Equity Take-Private Negotiations: Shares tumbled intraday after reports revealed that buyout firms Clayton, Dubilier & Rice (CD&R) and GTCR abandoned preliminary talks to acquire Global Payments, removing a high-profile leveraged buyout catalyst due to complex deal execution and prohibitive debt financing conditions for a $26+ billion market capitalization company.
- Heightened Balance Sheet and Financing Vulnerabilities: The breakdown of transaction discussions emphasizes market concerns surrounding Global Payments' substantial debt load and elevated borrowing costs following its major Worldpay acquisition, limiting corporate financial flexibility in a higher-for-longer interest rate environment.
- GAAP Profitability Compression and Ongoing Integration Friction: Global Payments' GAAP diluted earnings per share dropped nearly 60% year-over-year in its third-quarter results, weighed down by discontinued operations, restructuring costs, and execution hurdles related to digesting Worldpay while divesting non-core operations.
- Sluggish Normalized Organic Growth and Merchant Vulnerability: The firm continues to face muted normalized top-line expansion of approximately 4% to 5%, revealing operational headwinds and macro sensitivity across its core small and medium-sized business merchant footprint alongside lingering discretionary spending softness.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.