


Millicom International Cellular SA Stock (TIGO) Moved Down by 8.40% on Nov 12: A Full Analysis


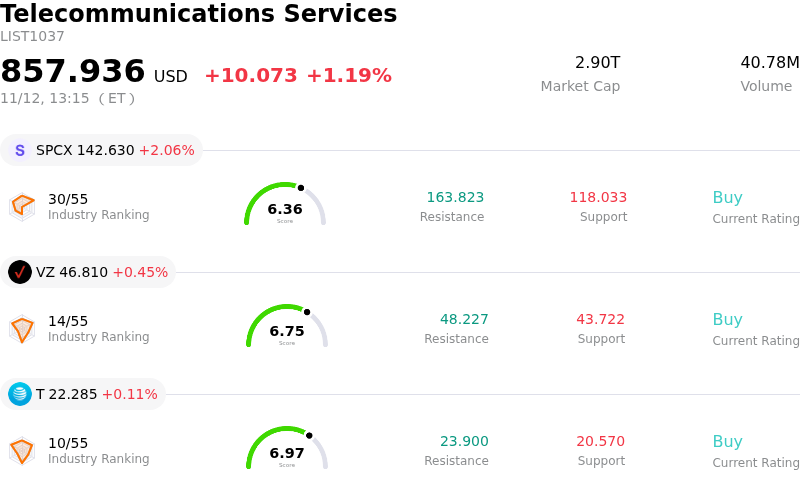
Millicom International Cellular SA (TIGO) moved down by 8.40%. The Telecommunications Services sector is up by 1.19%. The company underperformed the industry. Top 3 stocks by turnover in the sector: SpaceX (SPCX) up 2.05%; Verizon Communications Inc (VZ) up 0.45%; AT&T Inc (T) up 0.11%.
What is driving Millicom International Cellular SA (TIGO)’s stock price down today?
Shares of Millicom International Cellular experienced pronounced downward pressure during intraday trading, primarily driven by lingering post-earnings skepticism and mounting institutional concerns regarding profitability margins and integration expenses. While the company recently demonstrated solid top-line expansion, the market remains sharply focused on bottom-line underperformance, where net earnings fell considerably short of consensus expectations. The widening disparity between revenue growth and net profit conversion has sparked renewed debates across Wall Street regarding structural margin sustainability amid ongoing business transformations.
A critical factor weighing on investor sentiment is the elevated operational and capital cost trajectory associated with Millicom’s aggressive footprint expansion and network integration initiatives across core Latin American markets. Network upgrades, spectrum commitments, and restructuring charges have compressed operating margins, dampening the near-term cash-flow narrative. Furthermore, soft performance in business-to-business services has offset resilient consumer mobile and fixed-line additions, highlighting pockets of enterprise spending hesitation across the region.
Macroeconomic and currency dynamics across Latin America continue to compound these operational headwinds. Given Millicom’s high concentration of revenue in developing markets, local currency volatility against the US dollar tightens financial conditions and increases the real cost of servicing dollar-denominated obligations. Although management has focused on deleveraging, total debt remains high following prior acquisitions, making the equity sensitive to any margin slippage or fluctuations in sovereign borrowing costs.
From a market strategy perspective, the pullback also reflects institutional portfolio rebalancing and profit-taking. Following an extended upward trajectory over previous quarters, institutional investors adjusted exposure as multiple research desks reassessed forward price targets and voiced caution over near-term margin recovery. In the near term, Millicom’s ability to stabilize sentiment will depend on demonstrating tangible synergies from its regional integration, curtailing non-essential capital expenditures, and accelerating equity free cash flow to bolster debt reduction commitments.
Technical Analysis of Millicom International Cellular SA (TIGO)
Technically, Millicom International Cellular SA (TIGO) shows a MACD (12,26,9) value of 2.437, indicating a neutral signal. The RSI at 47.625 suggests neutral condition and the Williams %R at 61.910 suggests sell condition. Please monitor closely.
Fundamental Analysis of Millicom International Cellular SA (TIGO)
Millicom International Cellular SA (TIGO) is in the Telecommunications Services industry. Its latest annual revenue is $5.82B, ranking 26 in the industry. The net profit is $1.32B, ranking 9 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $89.00, a high of $100.00, and a low of $60.10.
More details about Millicom International Cellular SA (TIGO)
Company Specific Risks:
- Severe Q3 Net Income Contraction and EPS Miss: Millicom reported third-quarter earnings of $0.58 per share, missing consensus estimates of $0.98 by more than 40%, accompanied by a 49.9% year-over-year drop in net profit attributable to shareholders down to $98 million, intensifying institutional analyst concern over underlying margin degradation despite acquisition-driven top-line growth.
- Elevated Debt Burden and M&A Integration Exposures: Following the consolidation of Coltel, Tigo Ecuador, Tigo Uruguay, and Telefónica's operations in Chile, the company carries $8.65 billion in gross debt ($7.98 billion net debt), leaving its balance sheet with a high debt-to-equity ratio and amplifying vulnerability to emerging market macroeconomic shocks, currency devaluations, and debt-service constraints.
- Material Legal Settlement Obligations and Asset Impairments: Financial disclosures revealed a $99 million charge to resolve pending claims involving former Tigo Guatemala executives—with $68 million remaining payable over the next seven years—alongside a $32 million goodwill impairment recognized on its Costa Rica cash-generating unit and contingent earn-out commitments of up to $490 million tied to its Chile joint venture.
- Aggressive Dividend Expansion Straining Cash Allocation: Management’s decision to increase upcoming 2027 dividend distributions by an additional $0.75 per share on top of an already high payout ratio exceeding 70%, combined with a 51% year-over-year surge in quarterly capital expenditures to $243 million, significantly restricts liquidity buffers and risks overextending free cash flow headroom.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.