


Phillips 66 Stock (PSX) Closed Up by 3.18% on Nov 11: Drivers Behind the Movement


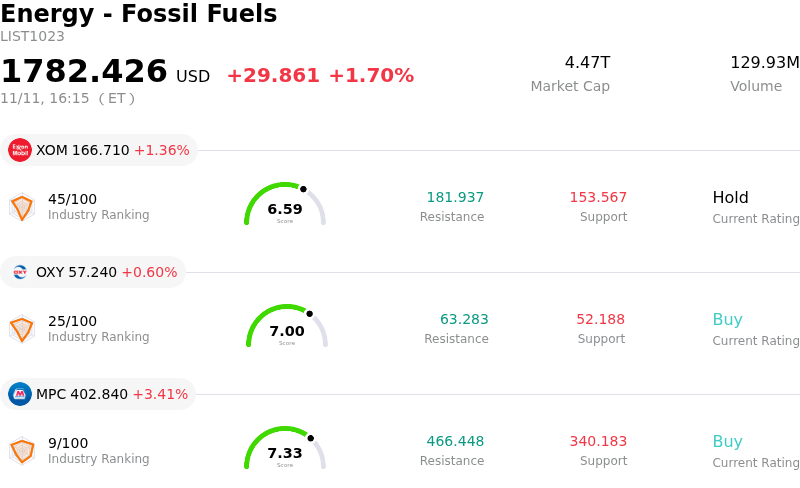
Phillips 66 (PSX) closed up by 3.18%. The Energy - Fossil Fuels sector is up by 1.70%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Exxon Mobil Corp (XOM) up 1.36%; Occidental Petroleum Corp (OXY) up 0.60%; Marathon Petroleum Corp (MPC) up 3.41%.
What is driving Phillips 66 (PSX)’s stock price up today?
Phillips 66 advanced as broader strength across the energy sector and favorable downstream fundamentals fueled institutional buying. Investor sentiment in the refining and midstream space was bolstered by firming regional crack spreads, reflecting resilient consumption for transport fuels and tight product inventories. As refining margins expanded, market participants revised their near-term margin expectations upward, positioning the company to capture stronger cash generation from its core refining footprint.
Operational execution and ongoing portfolio optimization have continued to provide structural support for the shares. Phillips 66 has maintained disciplined capital allocation, actively divesting non-core assets to streamline operations while returning substantial capital to shareholders via share buybacks and dividends. The company's growing midstream and chemicals segments also provide an important stabilizer against cyclical refining swings, offering steady fee-based earnings and feedstock advantages that appeal to defensive institutional capital.
A supportive macroeconomic backdrop and broader rotation into value-oriented cyclical equities further amplified the upward move. As energy market fundamentals tightened and macroeconomic indicators pointed to sustained domestic demand, institutional allocators increased their exposure to top-tier downstream operators with robust balance sheets. With strong operational reliability, attractive cash returns, and operational leverage to crack spread improvements, Phillips 66 stood out as a primary beneficiary of today's sector-wide momentum.
Technical Analysis of Phillips 66 (PSX)
Technically, Phillips 66 (PSX) shows a MACD (12,26,9) value of -7.363, indicating a sell signal. The RSI at 44.247 suggests neutral condition and the Williams %R at 66.863 suggests sell condition. Please monitor closely.
Fundamental Analysis of Phillips 66 (PSX)
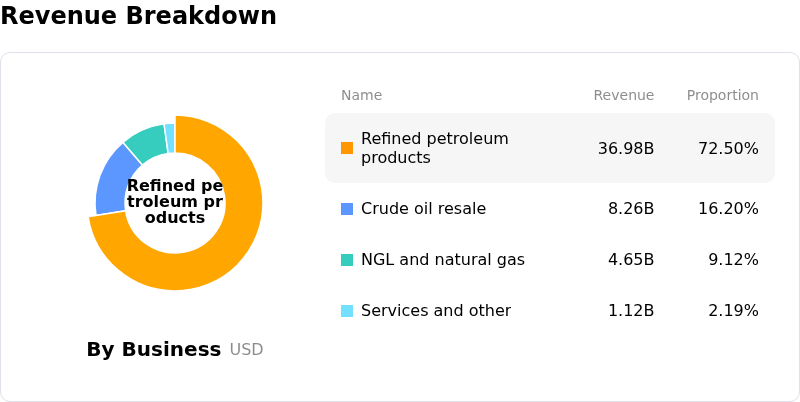
Phillips 66 (PSX) is in the Energy - Fossil Fuels industry. Its latest annual revenue is $132.38B, ranking 7 in the industry. The net profit is $4.39B, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $283.24, a high of $350.00, and a low of $158.00.
More details about Phillips 66 (PSX)
Company Specific Risks:
- Crack Spread Normalization and Cyclical Peak Sell-Off: Accelerating moderation in product futures and benchmark 3-2-1 crack spreads from recent highs has intensified sector-wide selling, heightening institutional fears that Phillips 66's $38.00 per barrel realized refining margin represents a cyclical profit peak that cannot be sustained into upcoming quarters.
- Multiple Compression Exposure from Premium Relative Valuation: Analyst commentary notes that Phillips 66 trades at an elevated trailing enterprise-value-to-EBITDA multiple of nearly 7.0x against the broader refining peer group average of 4.6x to 5.6x, leaving the equity uniquely exposed to rapid valuation multiple contraction as refining winds down from record levels.
- Litigation Liabilities and Midstream Legal Headwinds: Ongoing legal disclosures from SEC filings underscore substantial balance-sheet risk, including $947 million in accrued liabilities stemming from an $833 million trade-secret misappropriation judgment in favor of Propel Fuels that remains on appeal, alongside renewed tribal litigation challenging key capacity authorizations on the Dakota Access Pipeline.
- Sequential Earnings Deterioration in Non-Refining Segments: Company operational data highlights execution weaknesses across non-refining operations, where pre-tax earnings compressed sharply quarter-over-quarter across Chemicals, Marketing and Specialties (falling over 50% to $245 million), and Renewable Fuels (tumbling to $191 million) due to weaker chemical margins and inventory headwinds.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.