


Equinox Gold Corp Stock (EQX) Closed Down by 7.11% on Nov 10: Drivers Behind the Movement


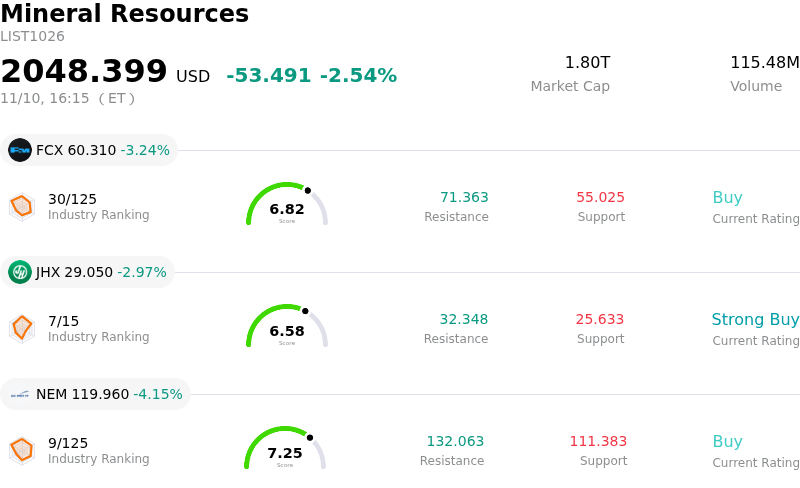
Equinox Gold Corp (EQX) closed down by 7.11%. The Mineral Resources sector is down by 2.54%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Freeport-McMoRan Inc (FCX) down 3.24%; James Hardie Industries PLC (JHX) down 2.97%; Newmont Corporation (NEM) down 4.15%.
What is driving Equinox Gold Corp (EQX)’s stock price down today?
Equinox Gold faced notable downward pressure following the release of its third-quarter financial results and subsequent management conference call. Although the company delivered substantial headline top-line expansion supported by contributions from its newly integrated assets, performance across key operational metrics fell short of broader market expectations. Revenue missed consensus estimates, prompting immediate selling pressure as investors reassessed near-term growth trajectories against elevated valuation multiples.
A primary catalyst for the decline was management commentary regarding full-year production guidance. Operating updates revealed that full-year output is currently tracking toward the low end of the guided range. Operational headwinds weighed on sentiment, notably throughput restrictions at the Greenstone mine resulting from equipment replacements, alongside geotechnical challenges at Mesquite. Furthermore, higher-than-expected fuel expenses, maintenance requirements, and sustaining capital expenditures elevated all-in sustaining costs, underscoring persistent inflationary and operational frictions across the asset base.
External macroeconomic conditions amplified the downward trajectory. A pullback in bullion prices, spurred by a firmer U.S. dollar and lingering hawkish monetary policy expectations, created broader headwinds across the precious metals mining complex. As intermediate producers often carry higher operational leverage to the underlying commodity price, equities in the sector exhibited heightened sensitivity to softening gold prices.
Despite positive corporate actions, including dividend payments and share repurchases, market participants prioritized near-term execution hurdles and free cash flow generation over capital return programs. With integration risks following major asset consolidation still underway and key expansion initiatives requiring disciplined capital deployment, institutional investors adopted a cautious stance, triggering sharp intraday de-risking.
Technical Analysis of Equinox Gold Corp (EQX)
Technically, Equinox Gold Corp (EQX) shows a MACD (12,26,9) value of 0.390, indicating a neutral signal. The RSI at 52.514 suggests neutral condition and the Williams %R at 35.793 suggests buy condition. Please monitor closely.
Fundamental Analysis of Equinox Gold Corp (EQX)
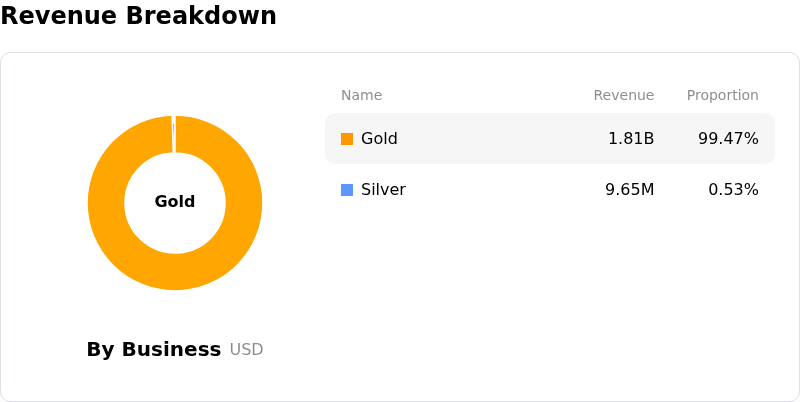
Equinox Gold Corp (EQX) is in the Mineral Resources industry. Its latest annual revenue is $1.82B, ranking 48 in the industry. The net profit is $221.47M, ranking 46 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $21.25, a high of $23.00, and a low of $19.51.
More details about Equinox Gold Corp (EQX)
Company Specific Risks:
- Elevated All-In Sustaining Costs and Margin Compression: In its Q3 2026 financial report released on November 9, the company reported all-in sustaining costs (AISC) escalating to $2,091 per ounce and cash costs reaching $1,654 per ounce of gold sold, demonstrating persistent unit-cost inflation that is eroding operating margins.
- Guidance Skewed Toward Lower Production and Higher Costs: Management confirmed in its latest operational update that full-year 2026 output is tracking toward the low end of its 870,000 to 920,000-ounce guidance range, while full-year AISC is pacing toward the top end of the $1,900 to $2,000 per ounce range, raising execution risks for the fourth quarter.
- Post-Merger Asset Integration Drag: Institutional analysts are scrutinizing elevated operating expenditures and integration costs following the July 31 business combination with Orla Mining, as assimilating the Musselwhite and Camino Rojo assets has introduced near-term operational friction and diluted free cash flow conversion.
- Permitting Exposure and Capital Outlay Overhang: The latest disclosures highlight continuing capital expenditure demands for growth projects alongside unfinalized state environmental permits and water rights extending into 2027, exposing forward development schedules to regulatory delays and potential cost overruns.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.