


Charter Communications Inc Stock (CHTR) Moved Up by 10.28% on Nov 10: Facts Behind the Movement


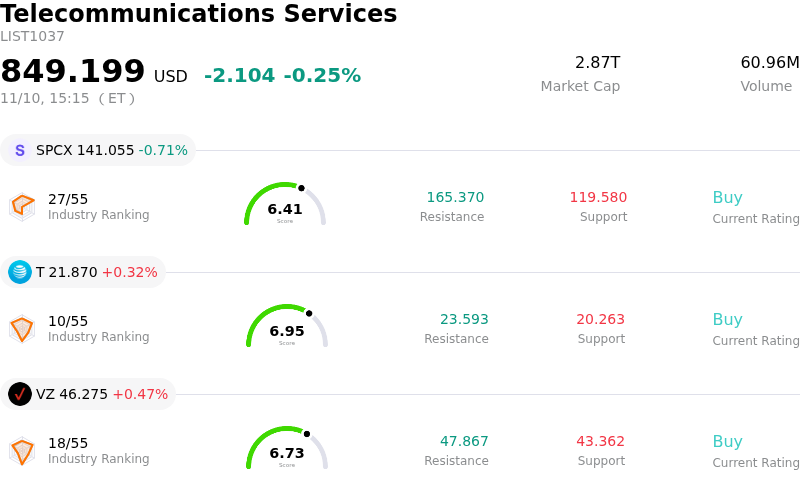
Charter Communications Inc (CHTR) moved up by 10.28%. The Telecommunications Services sector is down by 0.25%. The company outperformed the industry. Top 3 stocks by turnover in the sector: SpaceX (SPCX) down 0.66%; AT&T Inc (T) up 0.32%; Verizon Communications Inc (VZ) up 0.47%.
What is driving Charter Communications Inc (CHTR)’s stock price up today?
Charter Communications experienced a sharp upward surge as institutional investors aggressively re-evaluated the company following its latest quarterly disclosures and the unveiling of a comprehensive operational restructuring plan. While headline GAAP earnings appeared weighed down by a substantial non-cash franchise impairment charge, the market looked through the accounting write-down to focus on core cash generation, capital discipline, and management’s aggressive cost-containment initiatives.
The primary catalyst fueling buying pressure was management’s commitment to an extensive operational overhaul targeting billions of dollars in annualized run-rate operating expense reductions over the next eighteen months. These planned savings, combined with significant cost synergies anticipated from the ongoing integration of Cox Communications, provided investors with clear visibility into multi-year margin expansion and accelerated deleveraging. For a capital structure that has faced scrutiny over debt levels and high leverage ratios, the strategic emphasis on operational efficiency and debt exchange gains offered critical balance sheet reassurance.
Operationally, sentiment was buoyed by persistent strength in the convergence strategy. Although broadband customer trends remain challenged by competitive fiber buildouts and fixed wireless access, Charter continued to demonstrate strong momentum in its mobile division, delivering healthy line additions. Concurrently, video subscriber attrition moderated meaningfully compared to prior periods, signaling that bundled packaging and enhanced customer retention efforts are beginning to stabilize key customer relationships.
Market dynamics and positioning also played an instrumental role in amplifying the rally. Heading into the earnings cycle, sentiment toward cable and telecommunications operators had been deeply depressed, leaving the stock trading at historically compressed valuation multiples with notable short interest. The clarity provided around cost rationalization, combined with better-than-feared underlying cash flow, triggered an aggressive short squeeze alongside institutional bargain hunting. As Wall Street analysts updated models to reflect the structurally lower cost base, the convergence of multiple expansion and sentiment recovery drove strong intraday outperformance.
Technical Analysis of Charter Communications Inc (CHTR)
Technically, Charter Communications Inc (CHTR) shows a MACD (12,26,9) value of 6.158, indicating a neutral signal. The RSI at 65.850 suggests neutral condition and the Williams %R at 0.336 suggests overbought condition. Please monitor closely.
Fundamental Analysis of Charter Communications Inc (CHTR)
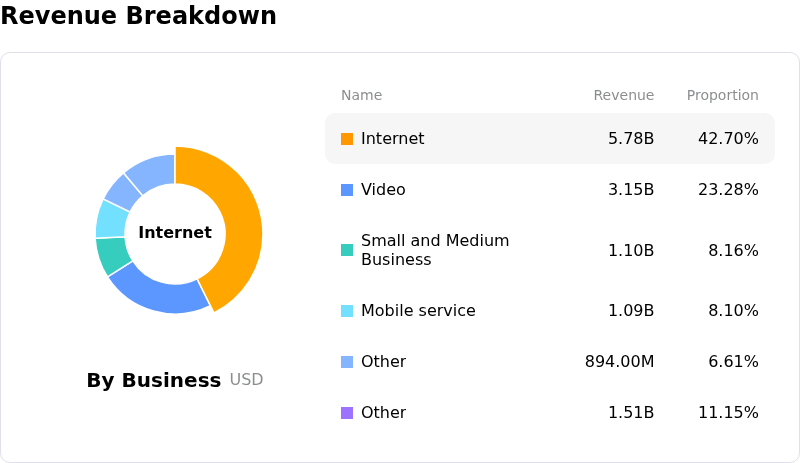
Charter Communications Inc (CHTR) is in the Telecommunications Services industry. Its latest annual revenue is $54.77B, ranking 5 in the industry. The net profit is $4.99B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $206.32, a high of $490.00, and a low of $80.00.
More details about Charter Communications Inc (CHTR)
Company Specific Risks:
- Accelerating Broadband Customer Attrition: Pro forma internet customer losses widened sharply to 233,000 in the third quarter (156,000 legacy Charter and 77,000 legacy Cox), worsening from a 171,000 loss in the prior-year period as intense competition from telecom fixed-wireless access (FWA) and aggressive fiber overbuilders continuously erodes core broadband market share.
- Multi-Billion Dollar Asset Impairment and Deep Net Loss: Third-quarter financial results triggered an adjusted net loss of $20.50 per share (missing expectations of a $9.02 profit per share) primarily caused by a $6.33 billion franchise impairment charge, reflecting institutional recognition of structural terminal value impairment in traditional cable network franchises.
- Free Cash Flow Deterioration Against Severe Leverage: Free cash flow dropped 58% year-over-year to $674 million, constrained by high capital expenditures alongside a massive $108.6 billion principal debt burden (3.93x leverage ratio), prompting the company to launch a $1.5 billion debt tender offer across eight series of senior notes to manage long-term maturity obligations.
- Operational Execution Risk Under Deep Cost Reductions: Management announced an aggressive $2 billion annualized operating expense reduction program to counter margin compression, but analysts warn that slashing costs during a period of heavy customer churn and complex Cox integration threatens customer service levels and network reliability without offering a definitive timeline to restore subscriber growth.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.