


Take-Two Interactive Software Inc Stock (TTWO) Moved Up by 7.02% on Nov 10: Facts Behind the Movement


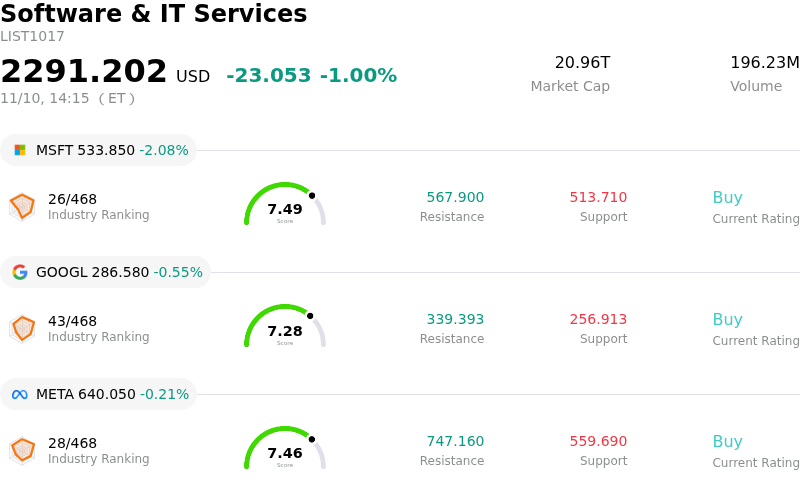
Take-Two Interactive Software Inc (TTWO) moved up by 7.02%. The Software & IT Services sector is down by 1.00%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 2.09%; Alphabet Inc Class A (GOOGL) down 0.51%; Meta Platforms Inc (META) down 0.19%.
What is driving Take-Two Interactive Software Inc (TTWO)’s stock price up today?
The primary catalyst driving the sharp upward momentum in Take-Two Interactive is the operational clarity and relief provided in the company's latest quarterly earnings announcement. Heading into the print, investor sentiment had been severely clouded by apprehension surrounding potential execution delays for the company's flagship pipeline asset. Executive management effectively dismantled these bearish concerns by firmly reaffirming the targeted launch schedule for Grand Theft Auto VI and revealing that player pre-orders are tracking significantly ahead of internal projections. This confirmation removed a major valuation overhang that had depressed the stock over recent quarters.
Reassurance on medium-term forward guidance further reinforced the buying interest. Take-Two maintained its full-year net bookings outlook, underscoring management's high degree of visibility into substantial revenue acceleration and expanding recurrent consumer spending in the second half of the fiscal year. Although reported top-line revenue reflected modest near-term friction in mobile engagements and select legacy sports titles, adjusted profitability came in ahead of Wall Street expectations due to rigorous cost containment and improved operating leverage. This operational discipline demonstrated that Take-Two can effectively protect cash flows while preparing for its broader commercial deployment.
The magnitude of the advance also stems from market positioning dynamics and institutional portfolio flows. The equity had been trading near technical multi-month lows following an extended period of de-risking, creating an environment primed for a strong relief rally upon the delivery of stable operating guidance. With key downside tail risks mitigated and the multi-billion-dollar product cycle reaffirmed, institutional capital rotated aggressively back into the name, while short-covering further amplified intraday liquidity and propelled the shares higher.
Technical Analysis of Take-Two Interactive Software Inc (TTWO)
Technically, Take-Two Interactive Software Inc (TTWO) shows a MACD (12,26,9) value of 5.226, indicating a neutral signal. The RSI at 62.991 suggests neutral condition and the Williams %R at 16.282 suggests overbought condition. Please monitor closely.
Media Coverage of Take-Two Interactive Software Inc (TTWO)
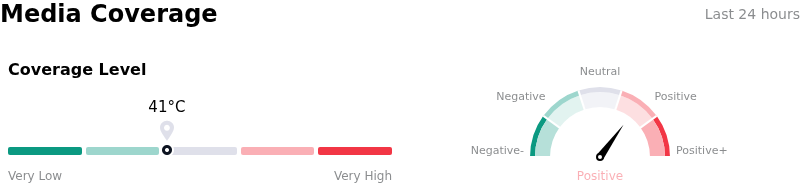
In terms of media coverage, Take-Two Interactive Software Inc (TTWO) shows a coverage score of 41, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Take-Two Interactive Software Inc (TTWO)
Take-Two Interactive Software Inc (TTWO) is in the Software & IT Services industry. Its latest annual revenue is $6.66B, ranking 50 in the industry. The net profit is $-298.20M, ranking 579 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $277.82, a high of $330.00, and a low of $172.41.
More details about Take-Two Interactive Software Inc (TTWO)
Company Specific Risks:
- Q2 Financial Miss and Bookings Shortfall: In its fiscal Q2 2027 results filed on Form 8-K, Take-Two reported net bookings of $1.60 billion (down 18% year-over-year), missing management's guidance range of $1.62 billion to $1.67 billion, alongside a GAAP net loss of -$0.29 per share that trailed market expectations.
- Acceleration in Recurrent Consumer Spending Decline: High-margin recurrent consumer spending dropped 9% year-over-year—significantly worse than management's forecasted 5% decline—dragged down by softer-than-projected launch performance and monetization of NBA 2K27 and ongoing weakness across the Zynga mobile portfolio.
- Sub-Consensus Q3 Bookings Guidance: Forward guidance for fiscal Q3 net bookings was set at $3.35 billion to $3.50 billion, coming in below consensus expectations of $3.51 billion and reflecting cautious assumptions for near-term monetization heading into the holiday quarter.
- Extreme Valuation and Execution Dependency on GTA VI: Reiterating full-year bookings guidance of $8.0 billion to $8.2 billion despite recent top-line misses concentrates immense execution risk on the imminent November 19 launch of Grand Theft Auto VI, leaving the company highly vulnerable to severe downside volatility if technical launch issues or monetization delays occur.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.