


GFL Environmental Inc Stock (GFL) Moved Down by 8.02% on Nov 10: Facts Behind the Movement


GFL Environmental Inc (GFL) moved down by 8.02%. The Industrial & Commercial Services sector is down by 0.72%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Nebius Group NV (NBIS) down 6.33%; Comfort Systems USA Inc (FIX) down 0.65%; GFL Environmental Inc (GFL) down 8.02%.
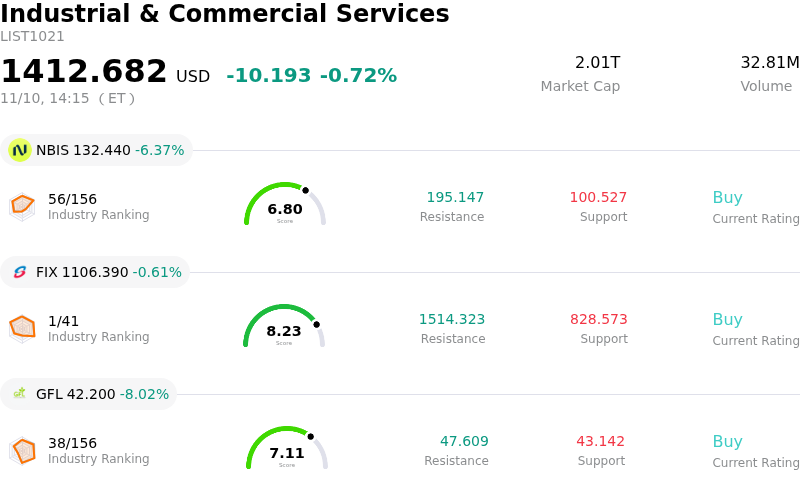
What is driving GFL Environmental Inc (GFL)’s stock price down today?
GFL Environmental experienced intense downward pressure primarily due to the abrupt conclusion of its multi-month strategic review without a transaction, which triggered an immediate unwinding of the takeover premium embedded in the shares. The company announced that its board and independent special committee unanimously determined to end discussions and remain an independent public entity after rejecting a take-private bid from a consortium of major private equity investors. With the pricing gap between the board’s valuation targets and the buyers’ offers proving insurmountable, event-driven funds and merger-arbitrage investors quickly rotated out of the stock, causing a steep retracement of prior deal-related gains.
Compounding the selloff is the emerging equity overhang associated with major shareholder liquidity. Alongside the decision to remain public, the company indicated it would facilitate the orderly sale of a substantial portion of the equity stake held by its primary financial sponsor, BC Partners, to third-party investors. Although framed as a measure to broaden the institutional register and resolve sponsor exit timelines, the prospect of a massive block of shares entering the secondary market heightened fears of near-term liquidity absorption and persistent technical overhang.
Fundamentally, the end of takeover negotiations forces investors to refocus on the company’s standalone profile, where high financial leverage remains a central concern. While management maintains an optimistic multi-year outlook centered on robust core pricing gains and expanding free cash flow, the business carries significant net debt following years of aggressive roll-up acquisitions. In a sustained higher-for-longer interest rate environment, institutional investors are reassessing execution risks tied to balance sheet de-leveraging and capital expenditure demands. Absent a buyout backstop, the company’s valuation is being re-anchored to its fundamental cash flow yield and standalone operational delivery.
Technical Analysis of GFL Environmental Inc (GFL)
Technically, GFL Environmental Inc (GFL) shows a MACD (12,26,9) value of -0.397, indicating a neutral signal. The RSI at 40.478 suggests neutral condition and the Williams %R at 73.906 suggests sell condition. Please monitor closely.
Fundamental Analysis of GFL Environmental Inc (GFL)
GFL Environmental Inc (GFL) is in the Industrial & Commercial Services industry. Its latest annual revenue is $4.87B, ranking 30 in the industry. The net profit is $2.79B, ranking 4 in the industry. Company Profile
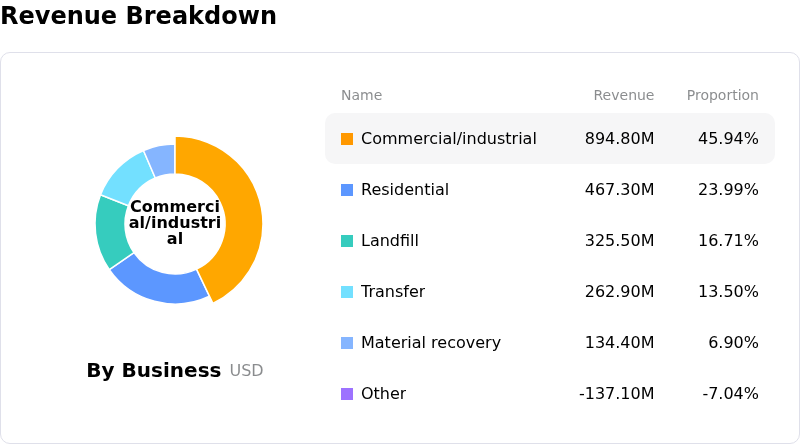
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $52.41, a high of $65.00, and a low of $38.60.
More details about GFL Environmental Inc (GFL)
Company Specific Risks:
- Termination of Strategic Review and Lost Takeover Premium: GFL's board formally concluded its strategic review and unanimously rejected a $52-per-share ($22 billion) take-private proposal from a private equity consortium led by Blackstone, KKR, and Energy Capital Partners after the consortium refused a $58-per-share counteroffer, instantly stripping out the acquisition premium embedded in the equity and triggering an immediate double-digit share price collapse.
- Imminent Equity Overhang from Major Sponsor Stake Sale: Coinciding with the decision to remain a public standalone company, GFL announced it will facilitate the secondary liquidation of a significant portion of BC Partners' 22% equity stake to outside buyers, creating substantial market supply overhang and downside pressure on share pricing.
- Heavy Leverage Profile and Standalone Cost Pressures: Remaining public refocuses institutional attention on GFL's aggressive rollup debt profile, which carries roughly $12 billion in total liabilities and a ~3.8x net leverage ratio; this balance sheet exposes the company to elevated debt servicing costs, volatile diesel fuel cost inflation, and margin compression without the capital shielding of private equity sponsorship.
- Ongoing GAAP Net Losses and Softening Institutional Conviction: GFL continues to operate at a net loss—recording a $409.8 million net loss from continuing operations through the first nine months of 2026—which, paired with a recent quarterly EPS miss and disclosed equity divestments by large institutional asset managers, amplifies the risk of further valuation multiple compression.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.