


Shopify Inc Stock (SHOP) Moved Down by 4.96% on Nov 10: Drivers Behind the Movement


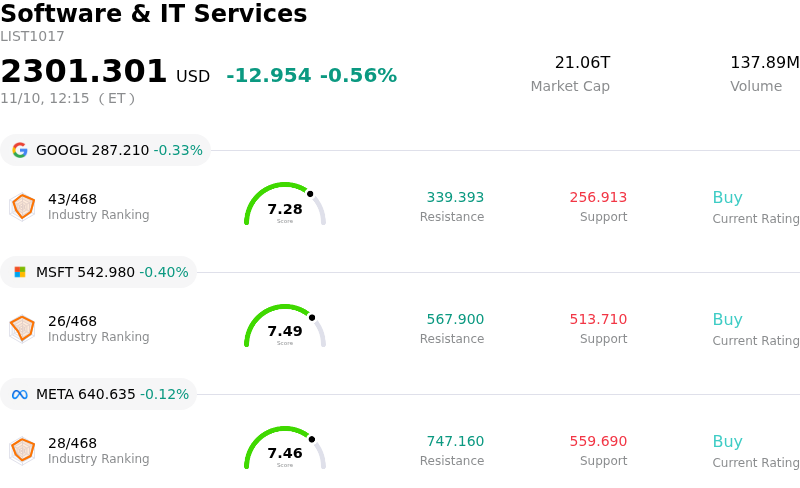
Shopify Inc (SHOP) moved down by 4.96%. The Software & IT Services sector is down by 0.56%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) down 0.33%; Microsoft Corp (MSFT) down 0.40%; Meta Platforms Inc (META) down 0.12%.
What is driving Shopify Inc (SHOP)’s stock price down today?
Shopify came under notable selling pressure as investor sentiment turned defensive ahead of the critical holiday shopping season, driven by concerns over consumer spending resilience and holiday-quarter gross merchandise volume growth. Heightened sensitivity to discretionary household budgets, persistent macroeconomic crosscurrents, and moderating retail sales momentum have prompted institutional investors to reassess their near-term growth expectations for e-commerce platforms.
Margin sustainability and operating leverage have re-emerged as key focal points for market participants. Although Shopify has sharpened its operational discipline and sustained profitable growth following the divestment of its capital-intensive logistics operations, the market remains acutely sensitive to reinvestment cycles. Rising sales and marketing expenditures, alongside ongoing capital commitments toward expanding enterprise merchant acquisition and artificial intelligence tools, have stirred concerns that near-term operating margins could face pressure during the high-volume promotional window.
Broader sector dynamics and macroeconomic headwinds also contributed to the intraday retreat. Across the technology and software-as-a-service landscape, elevated valuation multiples faced scrutiny amid broader equity market consolidation and fluctuations in benchmark Treasury yields. Growth equities trading at premium revenue and cash flow multiples remain particularly susceptible to de-risking flows whenever macroeconomic data points to potential deceleration in consumer discretionary outlays.
Competition within digital commerce continues to intensify as legacy platforms and emerging social commerce channels vie aggressively for digital merchant ad spend and conversion share. While Shopify maintains an industry-leading ecosystem and strong merchant retention, competitive promotional discounting across the digital retail sphere could weigh on effective take rates and cross-border commerce activity.
Looking ahead, institutional focus will remain centered on merchant volume execution throughout the upcoming peak promotional days, international expansion metrics, and the monetization trajectory of Shopify Payments. Until clearer data demonstrates that robust consumer engagement can sustain margin expansion into the new fiscal year, the shares are likely to remain sensitive to macroeconomic headlines and broader risk appetite.
Technical Analysis of Shopify Inc (SHOP)
Technically, Shopify Inc (SHOP) shows a MACD (12,26,9) value of -5.986, indicating a neutral signal. The RSI at 40.695 suggests neutral condition and the Williams %R at 77.969 suggests sell condition. Please monitor closely.
Fundamental Analysis of Shopify Inc (SHOP)
Shopify Inc (SHOP) is in the Software & IT Services industry. Its latest annual revenue is $11.56B, ranking 32 in the industry. The net profit is $1.23B, ranking 40 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $176.65, a high of $220.00, and a low of $120.00.
More details about Shopify Inc (SHOP)
Company Specific Risks:
- Gross Merchandise Volume and Revenue Deceleration: Recent financial reporting highlighted a rare top-line and Gross Merchandise Volume (GMV) shortfall against consensus forecasts, as GMV growth cooled from 31.6% to 29.5%; this deceleration raises immediate institutional concern over merchant transactional volumes and consumer demand fatigue heading into the peak holiday quarter.
- Structural Gross Margin Dilution from Payments Mix: Operational profitability faces ongoing margin compression as gross profit dollar growth (28%) continues to lag total revenue growth (32%), driven by higher penetration of lower-margin merchant solutions like Shopify Payments; Q4 forward guidance confirms this margin drag will persist with revenue expected to outpace gross profit expansion.
- Valuation Sensitivity to Multiple Compression: Trading at an elevated forward earnings multiple exceeding 60x, institutional analysts (including Cantor Fitzgerald and Seaport Research) have noted that the stock remains priced for near-flawless execution, leaving it highly susceptible to severe intraday derating and price target cuts upon any perceived softness in subscription solutions or guidance metrics.
- Insider Liquidation and Share Supply Overhang: Downward pressure and volatility are exacerbated by automated disposition plans adopted by senior management, including pre-arranged Class A share sales by executive leadership, creating persistent technical resistance and supply overhang as market participants absorb institutional profit-taking.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.