


Arm Holdings PLC Stock (ARM) Closed Up by 6.69% on Nov 9: What Signal Does It Send?


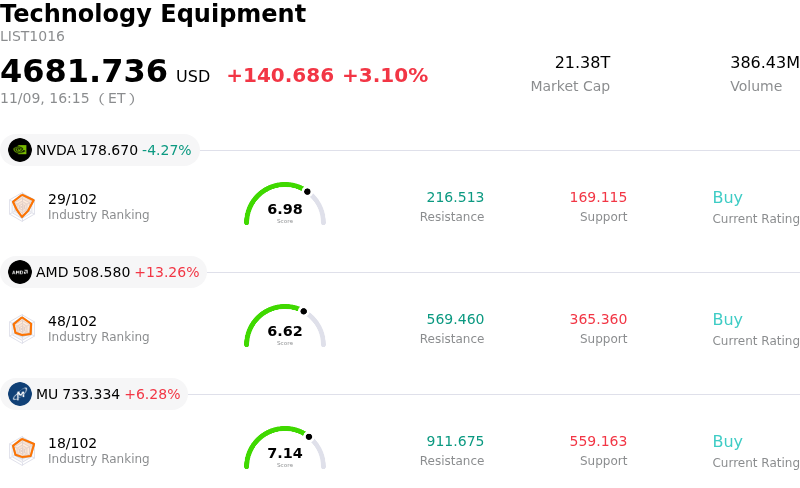
Arm Holdings PLC (ARM) closed up by 6.69%. The Technology Equipment sector is up by 3.10%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.27%; Advanced Micro Devices Inc (AMD) up 13.26%; Micron Technology Inc (MU) up 6.28%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced a strong upward move as market participants digested the company's latest quarterly financial results and medium-term strategic roadmap. Following initial post-earnings volatility, institutional sentiment rebounded decisively as investors refocused on the accelerating monetization of the Armv9 architecture and expanding penetration across artificial intelligence workloads and cloud data centers.
A primary catalyst driving today's rally is the growing institutional confidence in Arm's expanding footprint within the data center ecosystem. Hyperscalers and cloud service providers are accelerating their adoption of custom silicon and Arm-based central processing units to curb soaring power consumption in AI inference and training environments. Management's constructive commentary regarding chip production capacity and customer commitments reinforced expectations that data center compute will continue to displace legacy x86 architectures at an accelerated clip, significantly bolstering the company's long-term total addressable market.
Underpinning this expansion is the structural tailwind provided by the ongoing transition to the higher-royalty Armv9 instruction set architecture and Arm Compute Subsystems. Because Armv9 commands substantially higher royalty rates compared to legacy generations, the company is generating improved unit economics across both smartphone upgrades and edge AI computing deployments. Even amid cyclical crosscurrents in mature consumer electronics categories, the resilience of multi-year architectural licensing agreements and premium royalty expansions provides robust revenue visibility.
Broader semiconductor sector momentum and positive revisions in institutional risk appetite further amplified the advance. With macroeconomic conditions remaining supportive for high-growth secular winners and options-related volatility contracting, institutional inflows and technical follow-through helped propel shares higher throughout the session. While the stock continues to trade at a premium valuation relative to traditional semiconductor peers, the market's focus has firmly shifted toward Arm's indispensable positioning as a cornerstone intellectual property provider for the global AI compute buildout.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -6.570, indicating a sell signal. The RSI at 36.484 suggests neutral condition and the Williams %R at 69.003 suggests sell condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
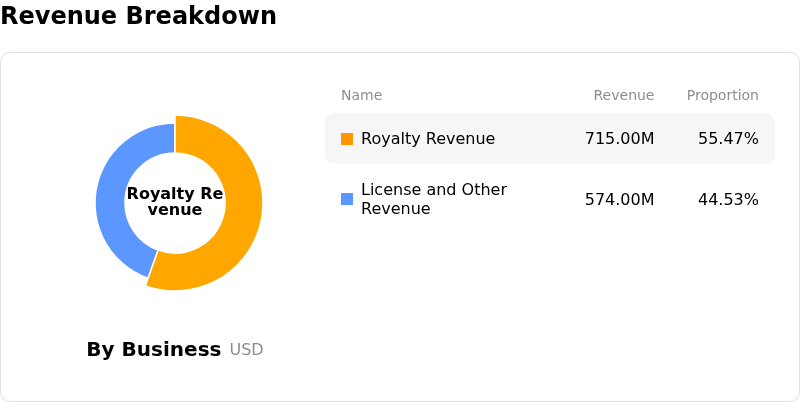
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Royalty Revenue Deceleration and Handset Weakness: Fiscal Q2 royalty revenue grew just 8% year-over-year to $670 million—missing consensus expectations—as elevated memory pricing curbed smartphone volumes, underscoring that strong upfront IP licensing gains have yet to convert into predictable, high-volume recurring royalties.
- Gross Margin Dilution from In-House Hardware Pivot: Management's initiative to manufacture and sell proprietary Arm AGI CPUs introduces hardware inventory and cost risks that dilute ARM's traditional ~98% pure-play IP gross margin profile down toward 87%, as initial hardware gross margins are projected at only 30% to 40%.
- Supply Chain and Advanced Node Foundry Constraints: Fulfilling the targeted $2 billion in first-party AGI CPU shipments through fiscal 2028 leaves ARM highly vulnerable to tight advanced packaging and leading-edge foundry capacity, threatening operational execution and delivery milestones.
- Analyst Downgrades and Multiple Compression: Wall Street firms including JPMorgan, Barclays, and Piper Sandler lowered price targets following cautious fiscal Q3 guidance, while Goldman Sachs reiterated a Sell rating with a $160 price target, warning that ARM's premium valuation multiple is unsustainable given decelerating royalty cash flows and rising R&D spending.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.