


KLA Corp Stock (KLAC) Closed Up by 9.31% on Nov 9: A Full Analysis


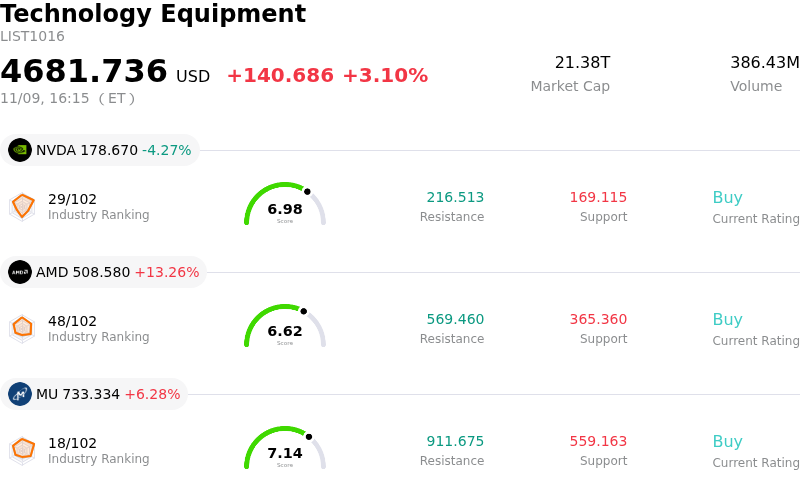
KLA Corp (KLAC) closed up by 9.31%. The Technology Equipment sector is up by 3.10%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.27%; Advanced Micro Devices Inc (AMD) up 13.26%; Micron Technology Inc (MU) up 6.28%.
What is driving KLA Corp (KLAC)’s stock price up today?
KLA Corporation exhibited sharp upward momentum today, driven by an accelerating resurgence in semiconductor capital expenditure sentiment and heightened investor enthusiasm for process diagnostics across advanced manufacturing nodes. As leading-edge foundries and memory makers advance transitions toward gate-all-around architectures and high-bandwidth memory packaging, inspection and metrology requirements have intensified significantly. Because structural yield challenges multiply at smaller physical dimensions and complex multi-die configurations, KLA stands as a prime beneficiary of structural capital allocation shifts within the wafer fab equipment sector.
The rally reflects broader institutional recognition of resilient demand fundamentals. Recent industry commentary and channel checks suggest that leading foundries and logic manufacturers are maintaining aggressive deployment plans for sub-three-nanometer capacity and advanced packaging expansions. KLA maintains a dominant market share in optical wafer inspection and patterned defect detection, where competitive moats remain extraordinarily wide. This technological defensibility shields the company from broader cyclical drawdowns while allowing disproportionate margin capture when industry sentiment turns expansionary.
In addition to bottom-up operational strengths, macroeconomic and broader technology sector tailwinds bolstered institutional bidding. Favorable risk appetite across mega-cap technology and semiconductor hardware fueled rotation into high-quality capital equipment leaders with robust free cash flow conversion and capital return programs. Sell-side analysts have increasingly revised revenue estimates and price targets upward, citing an extended runway for high-end process control intensity and stabilized legacy spending in international markets.
While geopolitical constraints and export controls on advanced semiconductor equipment remain persistent background variables for the broader sector, KLA's elevated exposure to critical, non-replaceable process control steps provides superior earnings visibility relative to commoditized equipment peers. The strong buying interest underscores growing institutional conviction that yield management spending will outpace broader wafer fab equipment growth over the next cyclical leg, positioning the stock for continued multiple support as capital spending momentum builds.
Technical Analysis of KLA Corp (KLAC)
Technically, KLA Corp (KLAC) shows a MACD (12,26,9) value of -1.681, indicating a sell signal. The RSI at 43.844 suggests neutral condition and the Williams %R at 46.193 suggests neutral condition. Please monitor closely.
Media Coverage of KLA Corp (KLAC)
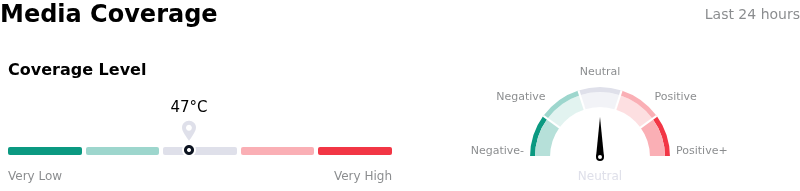
In terms of media coverage, KLA Corp (KLAC) shows a coverage score of 47, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of KLA Corp (KLAC)
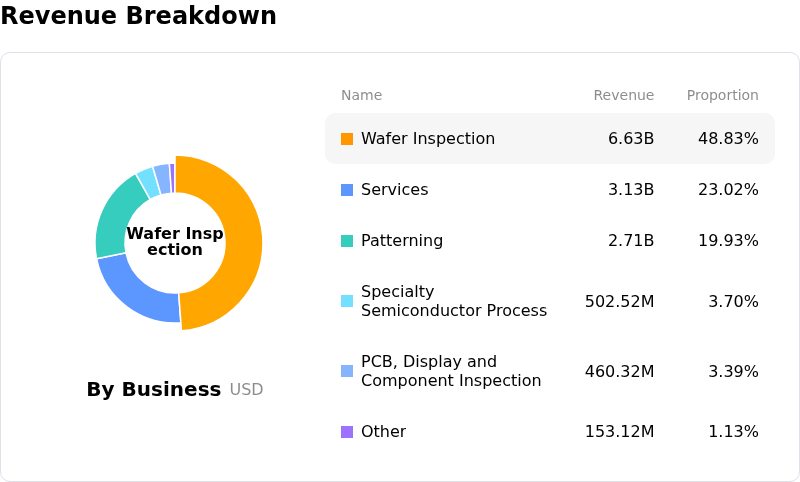
KLA Corp (KLAC) is in the Technology Equipment industry. Its latest annual revenue is $13.58B, ranking 15 in the industry. The net profit is $4.83B, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $214.38, a high of $275.00, and a low of $138.80.
More details about KLA Corp (KLAC)
Company Specific Risks:
- Wafer Fab Equipment Capex Digestion: Institutional investors are reassessing downstream customer capacity expansion, driven by concerns that chipmakers may slow wafer fabrication equipment (WFE) spending and yield-enhancement tool purchases after aggressive AI-linked capacity rollouts.
- High Valuation Multiple Compression: Trading at an elevated valuation exceeding 32x price-to-earnings, the stock is experiencing severe intraday multiple de-rating as models flag a diminished margin of safety if top-line growth and record operating margins fail to maintain their acceleration trajectory.
- Sustained Executive Insider Dispositions: Market sentiment has been weighed down by reports of heavy executive share liquidations totaling over $112 million across recent quarters with zero insider open-market purchases, fueling investor caution regarding near-term cyclical peaks.
- Geopolitical and China Trade Vulnerabilities: Heightened regulatory scrutiny and potential incremental export controls on advanced wafer inspection and metrology tools threaten a high-margin portion of international tool shipments and servicing revenue.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.