


CrowdStrike Holdings Inc Stock (CRWD) Moved Up by 5.89% on Nov 9: What Signal Does It Send?


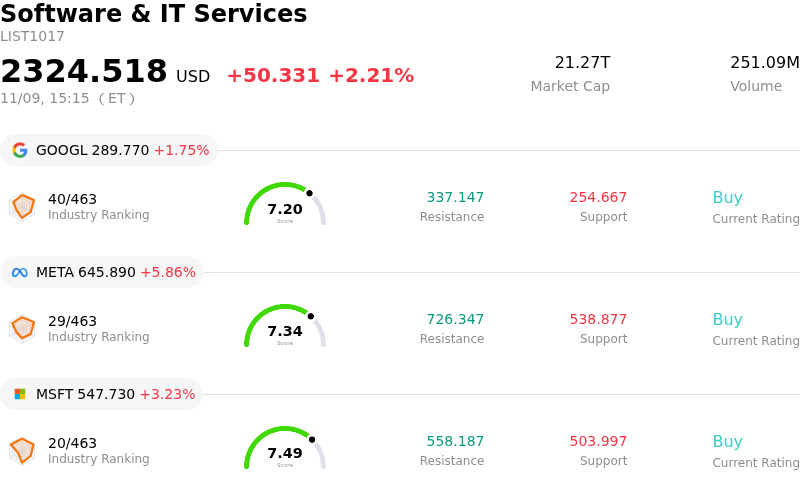
CrowdStrike Holdings Inc (CRWD) moved up by 5.89%. The Software & IT Services sector is up by 2.21%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) up 1.69%; Meta Platforms Inc (META) up 5.79%; Microsoft Corp (MSFT) up 3.23%.
What is driving CrowdStrike Holdings Inc (CRWD)’s stock price up today?
CrowdStrike experienced robust buying momentum, outperforming the broader software sector as institutional investors responded favorably to positive industry checks and an improving risk appetite across high-growth enterprise technology. The primary catalyst behind the advance stems from accelerating enterprise commitment toward vendor consolidation in cybersecurity, where CrowdStrike continues to capture market share through its comprehensive Falcon platform. Strong demand across identity protection, cloud workload security, and next-generation security information and event management has reaffirmed institutional confidence in the company’s ability to sustain durable annual recurring revenue expansion.
Favorable Wall Street commentary further catalyzed market sentiment, with research analysts highlighting resilient corporate cybersecurity budgets despite broader macroeconomic scrutiny on discretionary enterprise IT spending. Channel checks across key system integrators and technology partners suggest solid pipeline conversion and steady platform adoption, driven by customer efforts to eliminate redundant point products. The steady uptake of multi-module subscriptions reflects strong customer retention and lifetime value, easing prior investor anxieties regarding execution headwinds and demonstrating the platform’s mission-critical role within enterprise defense architectures.
Macroeconomic conditions provided an additional tailwind for premium software assets. Easing volatility in benchmark Treasury yields and sustained institutional accumulation in secular growth leaders created a constructive backdrop for valuation multiples. Short-covering dynamics and systematic fund inflows into leading cybersecurity exchange-traded funds added technical support to the upward move, underscoring strong liquidity and risk tolerance for top-tier software franchises with proven free cash flow generation.
Looking ahead, while fundamental positioning remains among the strongest in the cybersecurity landscape, investors should remain mindful of near-term tactical considerations. CrowdStrike trades at a premium valuation relative to the broader software peer group, leaving the equity sensitive to any potential elongation of corporate sales cycles or execution variance in upcoming earnings releases. Nevertheless, structural tailwinds in cloud migration, artificial intelligence security threats, and strict regulatory compliance requirements continue to anchor a compelling long-term thesis for institutional portfolios.
Technical Analysis of CrowdStrike Holdings Inc (CRWD)
Technically, CrowdStrike Holdings Inc (CRWD) shows a MACD (12,26,9) value of -8.069, indicating a sell signal. The RSI at 42.820 suggests neutral condition and the Williams %R at 72.829 suggests sell condition. Please monitor closely.
Media Coverage of CrowdStrike Holdings Inc (CRWD)
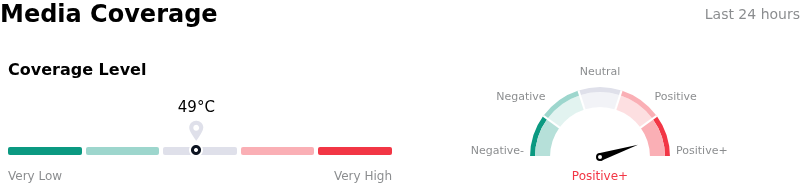
In terms of media coverage, CrowdStrike Holdings Inc (CRWD) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of CrowdStrike Holdings Inc (CRWD)
CrowdStrike Holdings Inc (CRWD) is in the Software & IT Services industry. Its latest annual revenue is $4.81B, ranking 67 in the industry. The net profit is $-162.50M, ranking 555 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $248.28, a high of $325.00, and a low of $119.00.
More details about CrowdStrike Holdings Inc (CRWD)
Company Specific Risks:
- Extreme Valuation Multiple and Institutional De-Risking: CrowdStrike remains exposed to severe multiple compression following recent high-volume drawdowns, as institutional investors reduce exposure to equities trading at an elevated forward price-to-sales multiple above 35x, with cautious analyst price targets such as Bernstein's $177 Market Perform pointing to substantial downside risk.
- Top-Line Revenue Growth Deceleration: Institutional analysts have flagged persistent deceleration in CrowdStrike's annual growth rate—slowing toward the low-20% range compared to historical rates above 35%—triggering concerns that net new annual recurring revenue (ARR) momentum is insufficient to justify current valuation premiums.
- M&A Integration Frictions and Margin Drag: CrowdStrike's recent $495 million capital commitment to acquire AI security startups Fiddler and Dreadnode introduces immediate operational integration risks and cash absorption that threaten near-term operating margins and free cash flow conversion.
- Escalating Competitive Encroachment: Heightened aggressive platform bundling and price discounting from large enterprise security rivals, including Microsoft, Fortinet, and Zscaler, heighten execution risk around customer renewal rates, module attach rates, and average contract values.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles











Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.