


Dell Technologies Inc Stock (DELL) Moved Up by 6.19% on Nov 9: Facts Behind the Movement


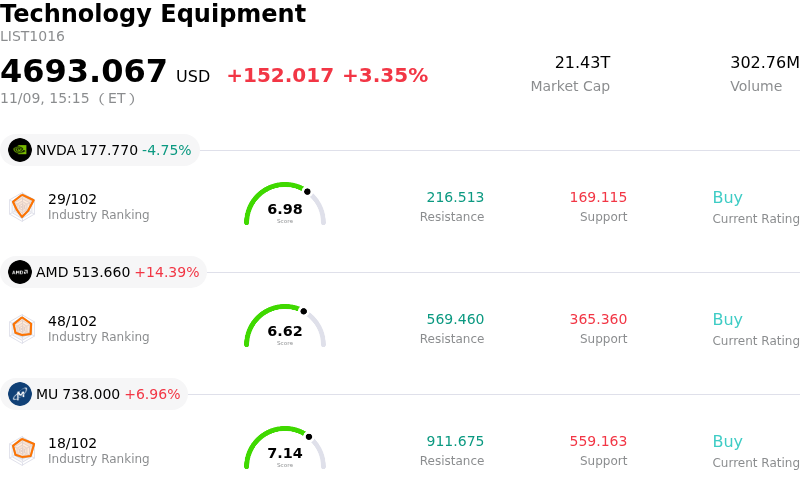
Dell Technologies Inc (DELL) moved up by 6.19%. The Technology Equipment sector is up by 3.35%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.82%; Advanced Micro Devices Inc (AMD) up 13.94%; Micron Technology Inc (MU) up 6.54%.
What is driving Dell Technologies Inc (DELL)’s stock price up today?
Dell Technologies experienced strong buying momentum during the trading session, driven primarily by renewed institutional confidence in enterprise artificial intelligence server demand and accelerating backlog conversion within its Infrastructure Solutions Group. Market sentiment was buoyed by positive channel checks and ecosystem commentary confirming sustained, robust capital expenditure from tier-two cloud service providers, sovereign entities, and enterprise clients deploying specialized high-density compute clusters. This enterprise-led hardware expansion continues to position Dell as a premier systems integrator capable of delivering full rack-scale architectures, proprietary liquid-cooling configurations, and integrated high-performance storage solutions.
Beyond dedicated artificial intelligence servers, investor enthusiasm was further reinforced by emerging tailwinds across the Client Solutions Group. Expectations surrounding an accelerating commercial personal computer refresh cycle, catalyzed by corporate deployments of next-generation AI-enabled devices and ongoing enterprise operating system upgrades, provide a resilient baseline for high-margin cash flow generation. At the same time, supply chain stabilization and disciplined pricing strategies are easing earlier concerns regarding server gross margin dilution, reassuring portfolio managers that operational leverage can offset elevated component costs.
Broader equity market dynamics also provided supportive conditions, with institutional capital actively rotating toward established infrastructure providers offering clear visibility into corporate hardware spending and shareholder-friendly capital return frameworks. Heightened sell-side optimism and favorable revisions to forward server delivery timelines have solidified Dell as an attractive vehicle for capturing enterprise compute expansion. While ongoing component supply constraints and potential macroeconomic headwinds on discretionary corporate budgets remain relevant risk factors, the current advance reflects strong conviction in Dell's strategic execution and expanding competitive moat across enterprise data center environments.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -27.731, indicating a sell signal. The RSI at 33.296 suggests neutral condition and the Williams %R at 82.467 suggests oversold condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
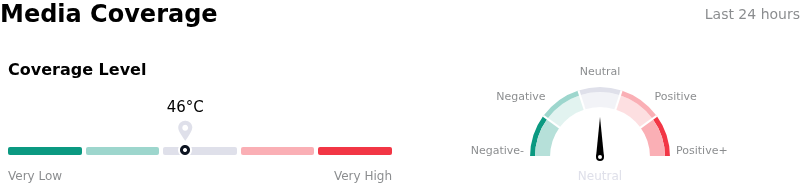
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
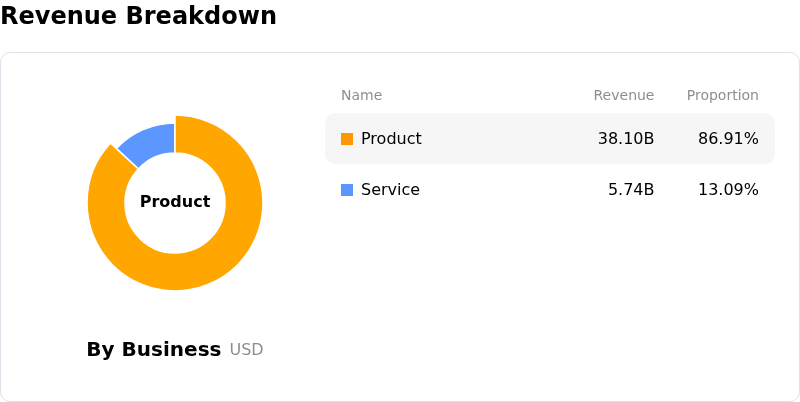
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $588.12, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- Data Center Permitting Headwinds and AI Backlog Execution: Emerging political proposals for state-level data center construction pauses and moratoriums across major infrastructure hubs threaten to delay hyperscaler deployments, directly jeopardizing the delivery schedule and conversion efficiency of Dell's $95 billion AI server backlog.
- Structural Margin Dilution and High Component Costs: Institutional analysts are increasingly concerned over Dell's compressed gross margins (hovering near 19.9%), which face continued dilution from low-margin GPU server assemblies and elevated memory pricing that limit free cash flow conversion despite strong top-line AI hardware orders.
- Prolonged Contraction in Core PC Segment Demand: Bleak supply-chain forecasts projecting a sustained 10% to 12% decline in global personal computer shipments into 2027—exacerbated by memory shortages and component cost inflation—threaten profitability and cash generation in Dell's Client Solutions Group.
- Persistent Insider Divestitures and Bearish Options Positioning: Market sentiment has deteriorated following recent Form 4 filings detailing extensive insider equity liquidation, which coincided with a spike in implied options volatility and an inverted put-call ratio signaling heightened institutional hedging against near-term downside.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.