


Lam Research Corp Stock (LRCX) Moved Up by 8.41% on Nov 9: Facts Behind the Movement


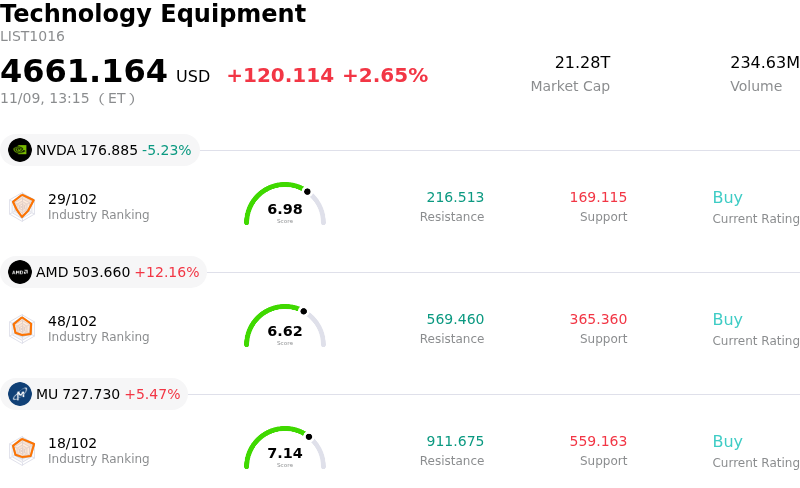
Lam Research Corp (LRCX) moved up by 8.41%. The Technology Equipment sector is up by 2.65%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 5.30%; Advanced Micro Devices Inc (AMD) up 12.27%; Micron Technology Inc (MU) up 5.54%.
What is driving Lam Research Corp (LRCX)’s stock price up today?
Lam Research experienced strong upward momentum as investor sentiment across the semiconductor capital equipment sector strengthened, driven by accelerating capital expenditure commitments from major chipmakers. Hyperscale cloud providers and leading semiconductor manufacturers continue to expand their infrastructure investments to meet the compute requirements of artificial intelligence, bolstering demand expectations for advanced wafer fab equipment. This macro and sector-wide tailwind has directed substantial capital flows toward premier toolmakers that supply essential front-end manufacturing technologies.
A primary fundamental catalyst behind this rally is the ongoing cyclical recovery in memory spending alongside rising adoption of next-generation packaging and architecture. Lam Research maintains an industry-leading position in high-aspect-ratio etching and advanced deposition technologies, which are indispensable for producing high-bandwidth memory, leading-edge DRAM, and advanced vertical 3D NAND. As memory producers transition to higher layer counts and expand capacities for advanced memory modules, equipment utilization and order intake are experiencing meaningful acceleration. Concurrently, the foundry and logic segment is benefiting from the structural migration toward gate-all-around architectures, which significantly expands the etch and deposition intensity per wafer and enhances Lam Research’s content opportunity.
Institutional sentiment was further reinforced by positive sell-side commentary and upward revisions to forward earnings estimates. Market participants are increasingly confident that wafer fab equipment spending has entered a durable expansionary phase. In addition, Lam Research’s high-margin Customer Support Business Group continues to generate resilient recurring revenue, providing steady cash flow and downside protection as older fab lines operate at elevated run rates and require ongoing servicing and upgrades.
While the broader operational trajectory is positive, institutional investors remain attentive to potential risks, including regulatory scrutiny regarding semiconductor trade policies, export licensing restrictions, and the timing of broad-based enterprise electronics demand recovery. Nevertheless, robust structural tailwinds from artificial intelligence infrastructure, coupled with the cyclical rebound in memory wafer fab equipment, served as the dominant drivers fueling the stock’s pronounced upward movement.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of -6.189, indicating a sell signal. The RSI at 37.813 suggests neutral condition and the Williams %R at 61.822 suggests sell condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
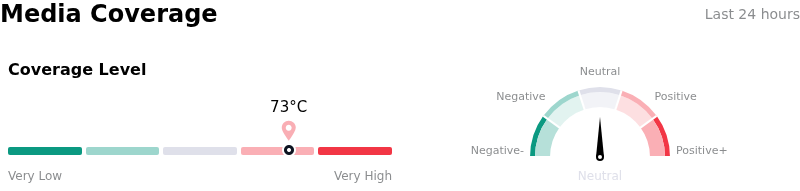
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 73, indicating a high level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Lam Research Corp (LRCX)
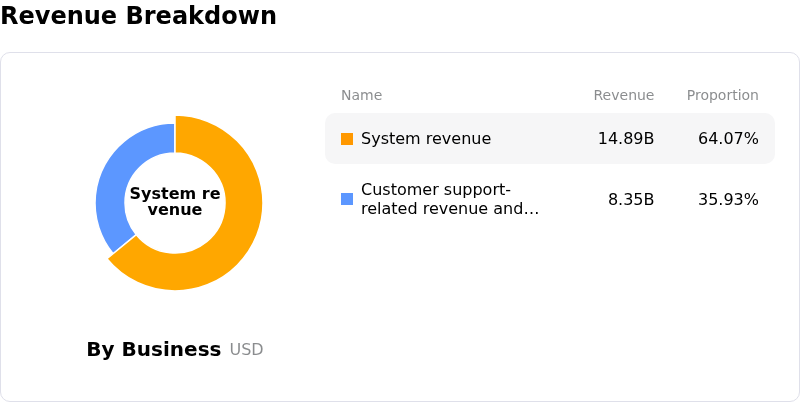
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $358.02, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Supply Chain Bottlenecks and Delivery Caps: Operational friction, critical component shortages, and customer clean-room space constraints have capped equipment delivery speed, forcing management to acknowledge that near-term revenue guidance was constrained despite robust order backlogs.
- Moderating China Revenue Exposure: Lam faces heightened vulnerability due to its concentrated exposure to China—representing roughly 35% of total revenues—as forward guidance signaled sequential sales deceleration in the region alongside ongoing trade and export restriction risks.
- Executive Insider Dispositions: SEC filings detailing sizable share liquidations by senior executives, including Chief Executive Officer Timothy Archer, have fueled broader institutional de-risking and exacerbated intraday selling pressure.
- Heightened Downside Options Skew and Multiple Sensitivity: An abrupt spike in 30-day implied volatility past 73 alongside steepening downside put-call skew points to aggressive institutional hedging, leaving the stock vulnerable to sharp pullbacks given its premium valuation multiple relative to historical norms.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.