


Broadcom Inc Stock (AVGO) Moved Up by 7.70% on Nov 9: Facts Behind the Movement


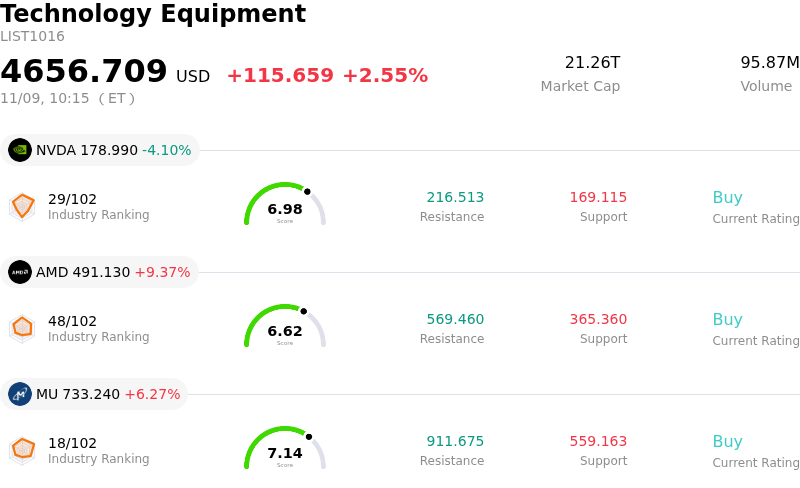
Broadcom Inc (AVGO) moved up by 7.70%. The Technology Equipment sector is up by 2.55%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.07%; Advanced Micro Devices Inc (AMD) up 8.99%; Micron Technology Inc (MU) up 5.87%.
What is driving Broadcom Inc (AVGO)’s stock price up today?
Broadcom is experiencing strong upward momentum driven by accelerating institutional conviction in its custom AI accelerator pipeline and high-performance networking architecture. Sustained expansion in capital expenditure budgets across global hyperscalers has reaffirmed multi-year demand visibility for application-specific integrated circuits, where Broadcom maintains a dominant market share. As tier-one cloud providers scale their internal machine learning clusters, Broadcom's co-designed silicon and next-generation Ethernet switching platforms continue to capture disproportionate wallet share, cementing its position as an indispensable infrastructure partner.
The sustained momentum is further reinforced by the operational execution of its infrastructure software segment, anchored by VMware. The shift toward higher-margin, multi-cloud subscription bundles is yielding robust recurring revenue and rapid margin expansion, dampening the cyclicality traditionally associated with pure-play semiconductor manufacturers. The combination of resilient software cash flows and explosive enterprise AI hardware growth has led several institutional research desks to lift medium-term earnings forecasts and valuation multiples, catalyzing renewed institutional accumulation.
From a market strategy perspective, the rally reflects a flight to quality within the semiconductor complex. Institutional portfolio managers are reallocating capital into cash-generative technology leaders possessing substantial moat depth, pricing power, and transparent backlog visibility. The resulting buy-side momentum, supported by favorable broader equity sentiment and firm risk appetite in large-cap technology, has spurred disciplined follow-through buying across institutional trading desks.
While near-term performance underscores Broadcom's strategic advantages, investors must monitor potential customer concentration risks among top hyperscalers and the pace of advanced packaging capacity deployment across the broader supply chain. Nevertheless, Broadcom’s dual-engine model, superior free cash flow conversion, and shareholder-friendly capital return policy solidify its standing as a cornerstone allocation in institutional technology portfolios.
Technical Analysis of Broadcom Inc (AVGO)
Technically, Broadcom Inc (AVGO) shows a MACD (12,26,9) value of -5.234, indicating a sell signal. The RSI at 43.361 suggests neutral condition and the Williams %R at 57.973 suggests sell condition. Please monitor closely.
Media Coverage of Broadcom Inc (AVGO)
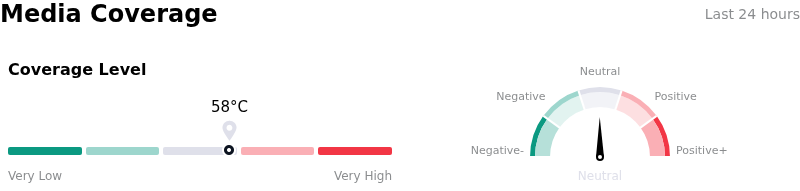
In terms of media coverage, Broadcom Inc (AVGO) shows a coverage score of 58, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Broadcom Inc (AVGO)
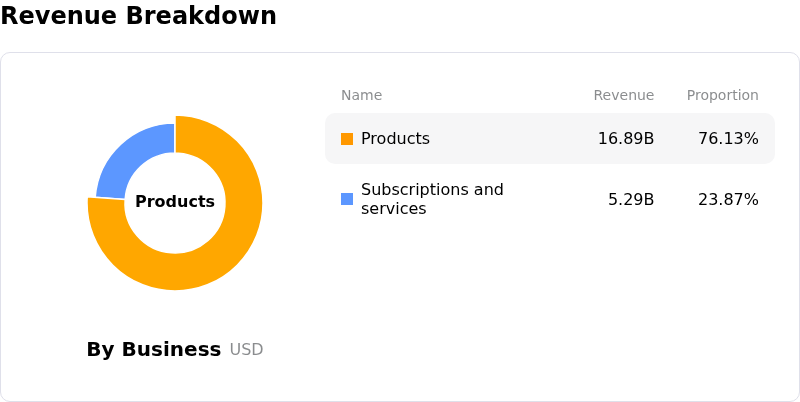
Broadcom Inc (AVGO) is in the Technology Equipment industry. Its latest annual revenue is $63.89B, ranking 5 in the industry. The net profit is $23.13B, ranking 5 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $516.73, a high of $663.00, and a low of $215.88.
More details about Broadcom Inc (AVGO)
Company Specific Risks:
- Residual Value Guarantee and AI Financing Exposure: Market scrutiny has intensified regarding Broadcom's contractual commitments tied to a multi-billion-dollar AI debt and lease financing structure for Anthropic, wherein Broadcom has reportedly extended residual value guarantees on deployed hardware, exposing its balance sheet to accelerated equipment obsolescence and counterparty credit risk.
- Gross Margin Dilution from Custom Silicon Mix: Institutional analysts are actively de-risking the stock due to sustained margin compression, with fiscal fourth-quarter gross margin guidance dropping to approximately 73% (down from roughly 78% year-over-year), driven by an aggressive revenue shift toward high-bandwidth memory-heavy custom AI accelerators (XPUs) that generate structurally lower profitability than legacy software and networking lines.
- Data Center Permitting and Neocloud Deployment Disruptions: Intraday volatility has spiked following reports that primary hyperscalers, such as Microsoft, are tightening oversight on third-party neocloud infrastructure, creating order-timing uncertainty that is exacerbated by regional power constraints and post-election permitting headwinds stalling data-center buildouts.
- Extreme Hyperscaler Customer Concentration: Broadcom's projected AI growth curve remains overwhelmingly tied to a concentrated pool of just six major XPU accounts, leaving revenue targets highly vulnerable to capex reallocations, design-in revisions, or supply bottlenecks in leading-edge silicon, substrates, and advanced packaging.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.