


Philip Morris International Inc Stock (PM) Moved Down by 3.81% on Nov 5: Drivers Behind the Movement


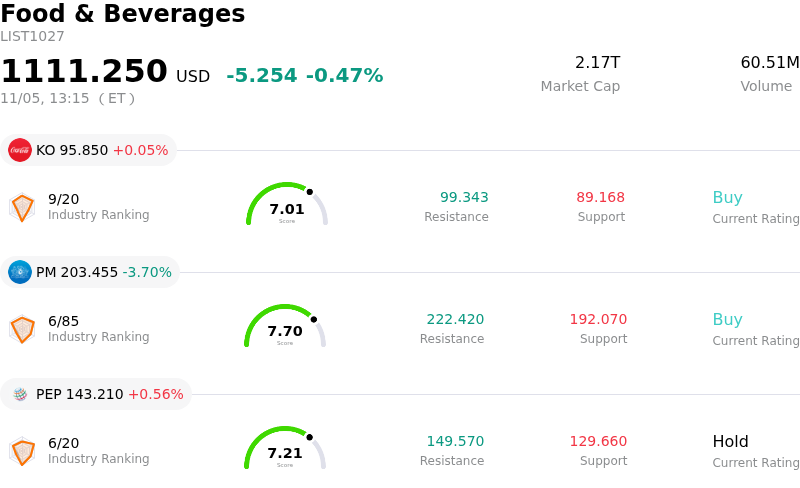
Philip Morris International Inc (PM) moved down by 3.81%. The Food & Beverages sector is down by 0.47%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Coca-Cola Co (KO) up 0.05%; Philip Morris International Inc (PM) down 3.70%; PepsiCo Inc (PEP) up 0.56%.
What is driving Philip Morris International Inc (PM)’s stock price down today?
Shares of Philip Morris International experienced notable downward pressure during the session, driven by a combination of macroeconomic factor rotations and sector-wide weakness across consumer staples. A broad market repositioning away from traditional defensive, income-oriented assets toward pro-cyclical and higher-beta sectors created significant liquidity outflows. Compounding this dynamic, rising benchmark yields reduced the relative valuation appeal of dividend-yielding consumer staples, encouraging multi-asset and institutional portfolios to trim low-beta yield exposures.
Currency fluctuations represent another key driver behind the pullback. Because Philip Morris derives the vast majority of its revenues and operating earnings from international markets while reporting in U.S. dollars, renewed strength in the greenback creates immediate translational headwinds. Appreciation of the U.S. dollar against core foreign currencies, such as the euro and the Japanese yen, mechanically compresses converted top-line receipts and net earnings, prompting quantitative and institutional models to recalibrate near-term profit projections downward.
From an operational and sector perspective, investor attention has centered on near-term margin implications associated with the company's smoke-free transition. While flagship platforms such as IQOS and ZYN remain fundamental to the long-term growth thesis, substantial capital commitments are required to expand domestic and international supply chains, build brand infrastructure, and counter competitive entrants. Elevated commercial investments and regulatory compliance overhead can create temporary margin friction, leading investors to adopt a more conservative stance on near-term operating leverage.
Finally, technical multiple compression and institutional profit-taking exacerbated the decline. Following extended outperformance relative to traditional combustible peers, the stock had reached valuation levels that left little room for macroeconomic or operational variance. In response to broad sector rotation and foreign exchange headwinds, large funds actively rebalanced risk, capitalizing on prior gains and driving an intraday valuation reset. Despite the pullback, institutional interest will likely remain anchored to the trajectory of smoke-free volume adoption and foreign exchange stabilization over the coming quarters.
Technical Analysis of Philip Morris International Inc (PM)
Technically, Philip Morris International Inc (PM) shows a MACD (12,26,9) value of 0.095, indicating a buy signal. The RSI at 52.603 suggests neutral condition and the Williams %R at 37.628 suggests buy condition. Please monitor closely.
Media Coverage of Philip Morris International Inc (PM)
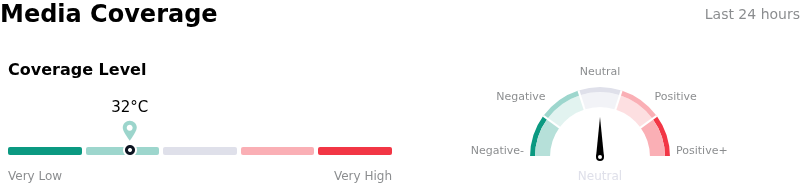
In terms of media coverage, Philip Morris International Inc (PM) shows a coverage score of 32, indicating a low level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Philip Morris International Inc (PM)
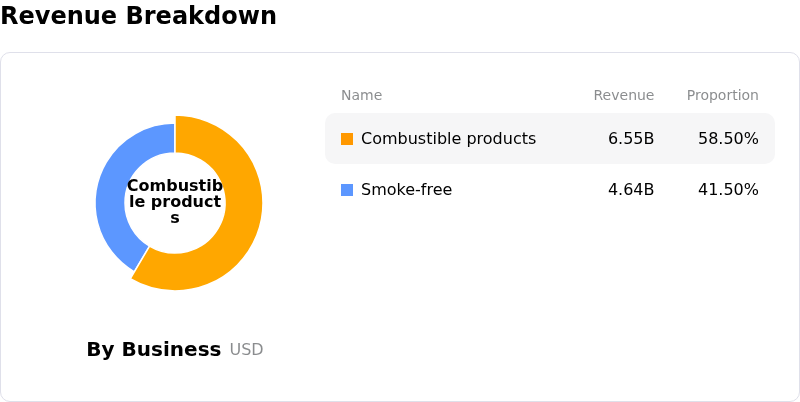
Philip Morris International Inc (PM) is in the Food & Beverages industry. Its latest annual revenue is $40.65B, ranking 5 in the industry. The net profit is $11.32B, ranking 1 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $207.35, a high of $232.00, and a low of $151.00.
More details about Philip Morris International Inc (PM)
Company Specific Risks:
- Margin Compression from ZYN Restructuring and Surging U.S. Commercial Outlays: Philip Morris is experiencing near-term margin erosion in its core smoke-free segment due to transitioning flagship ZYN cans from 15-pouch to 20-pouch formats without equivalent price increases, creating an approximate 25% drop in revenue per pouch. Compounded by aggressive national marketing and commercial expenditure to defend market share, management guided fourth-quarter U.S. adjusted operating income to roughly break-even or slightly negative.
- Geopolitical Supply Disruptions and Energy Inflation Pressuring Operating Targets: Management disclosures and institutional analyses indicate persistent cost headwinds stemming from repeated logistical disruptions to supply chain infrastructure in Ukraine alongside Middle East conflict-driven energy inflation. These mounting input and freight expenses have forced full-year organic operating income expectations down toward the lower half of the company's 7% to 9% guidance band.
- Stretched Valuation Premium Vulnerable to Multiple Contraction: Trading near record highs with a price-to-earnings multiple hovering near 30x—significantly higher than historical norms and defensive consumer staples peers—the stock faces heightened multiple compression risk. Recent analyst assessments highlight limited further re-rating potential, with target trims reflecting concerns that decelerating sequential earnings growth cannot sustain the current valuation multiple.
- Intensifying Market Share Threats Across Smoke-Free Categories: Institutional coverage cautions that PMI's core growth engines face aggressive competitive encroachment, led by British American Tobacco's Velo discounting in the U.S. oral pouch category and Japan Tobacco expanding heated-tobacco capacity against IQOS overseas. This mounting competitive friction threatens to limit volume offtake and require extended promotional reinvestment that restricts medium-term operating margins.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.