


Dell Technologies Inc Stock (DELL) Moved Up by 4.21% on Nov 3: What Signal Does It Send?


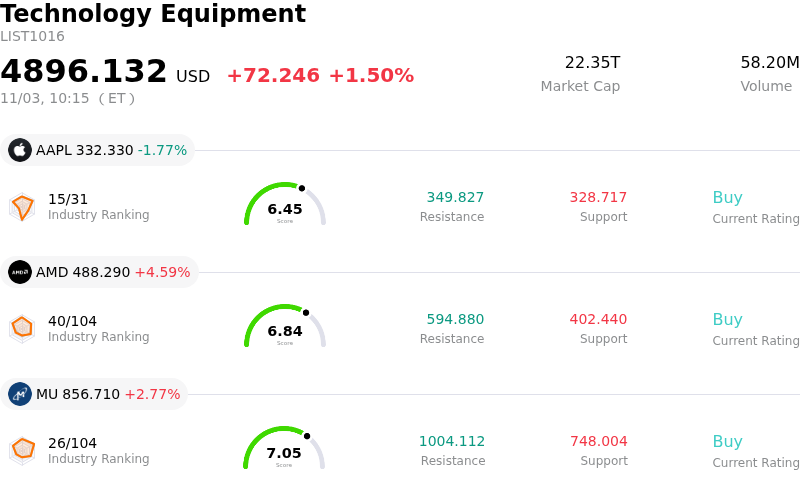
Dell Technologies Inc (DELL) moved up by 4.21%. The Technology Equipment sector is up by 1.50%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) down 1.77%; Advanced Micro Devices Inc (AMD) up 4.82%; Micron Technology Inc (MU) up 2.95%.
What is driving Dell Technologies Inc (DELL)’s stock price up today?
Dell Technologies registered positive price movement during the trading session, reflecting a sharp intraday reversal driven by aggressive dip-buying following a multi-session pullback across hardware and technology stocks. Market sentiment was initially weighed down by broader semiconductor volatility and macro concerns surrounding traditional personal computer volume forecasts. However, institutional investors utilized the recent price weakness as an opportunity to accumulate shares, recognizing that the selloff had outpaced the company's operational fundamentals. The intraday volatility highlighted a distinct shift in market positioning as bargain-hunting buyers stepped in to support the stock.
A key factor driving investor optimism is the clear separation between traditional consumer PC cycles and the structural momentum in high-performance enterprise hardware. Dell continues to capture substantial market share in artificial intelligence computing, anchored by an expansive AI server order backlog that recently surged to ninety-five billion dollars. The company's expansion into enterprise AI security solutions, post-quantum encryption, and data protection platforms has further strengthened its competitive positioning against legacy server and networking rivals. Strong order velocity for enterprise AI infrastructure and storage architectures continues to reassure investors that revenue growth is firmly anchored in high-margin enterprise spending.
From a strategic perspective, institutional sentiment remains underpinned by favorable analyst outlooks and elevated consensus price targets across major Wall Street firms. Investors are closely eyeing upcoming earnings reports from major chipmakers and hardware partners to gauge broader demand dynamics across AI server supply chains. While risks persist around potential memory component cost increases and near-term margin pressure on high-volume enterprise deployments, Dell's leadership in turnkey AI server solutions and robust cash flow dynamics provide solid fundamental support. The day's price action indicates renewed market confidence that structural enterprise AI tailwinds will continue to outweigh short-term cyclical friction.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -18.282, indicating a sell signal. The RSI at 35.753 suggests neutral condition and the Williams %R at 84.604 suggests oversold condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
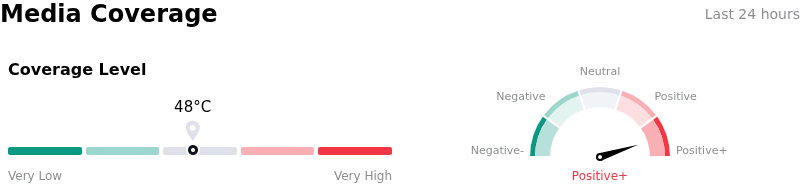
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
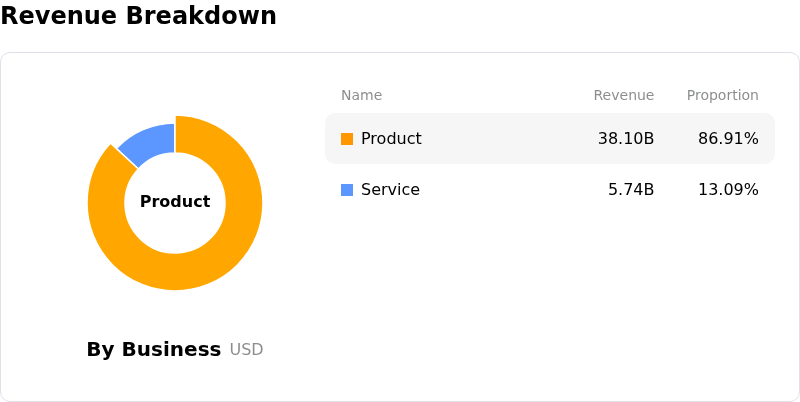
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $587.28, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- PC Market Contraction & Inventory Pressure: Intel's recent forecast of a 12% decline in PC unit shipments for 2026 and continued contraction in 2027 triggered severe intraday selling in Dell stock, reflecting heightened operational risk in Dell's Client Solutions Group as enterprise clients defer hardware refreshes.
- Free Cash Flow & Working Capital Strain: Dell's quarterly free cash flow dropped 47% year-over-year to $986 million as $6.67 billion was absorbed by customer financing receivables, creating severe cash conversion headwinds required to meet full-year cash targets.
- Margin Compression & Component Inflation: A rating downgrade from Barclays highlighted that recent revenue gains stem from elevated memory component costs passed to customers rather than true volume growth, while lower-margin AI server builds threaten to dilute corporate gross margins.
- Counterparty Exposure & AI Backlog Conversion Risk: Dell's $95 billion AI server backlog relies heavily on specialized neocloud providers facing debt market pressure, creating substantial downside risk that customers may struggle to secure financing to convert orders into recognized revenue.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.