


Datadog Inc Stock (DDOG) Moved Up by 7.80% on Oct 21: A Full Analysis



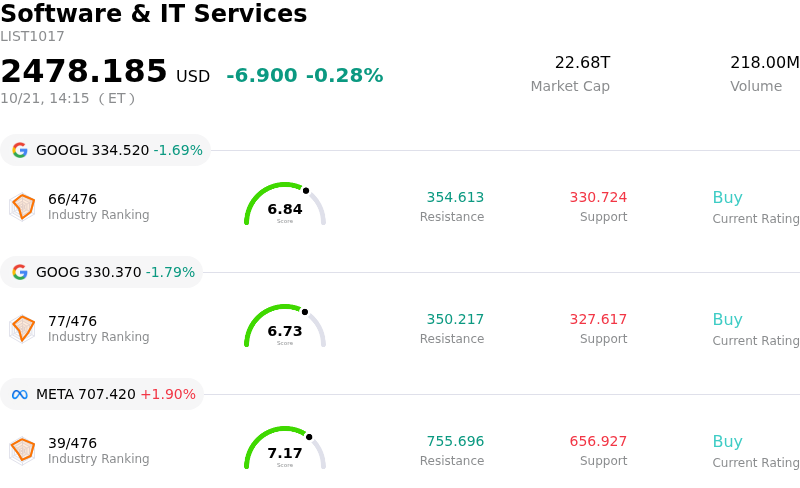
Datadog Inc (DDOG) moved up by 7.80%. The Software & IT Services sector is down by 0.28%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) down 1.69%; Alphabet Inc Class C (GOOG) down 1.79%; Meta Platforms Inc (META) up 1.90%.
What is driving Datadog Inc (DDOG)’s stock price up today?
Datadog experienced a sharp upward trajectory driven by a major analyst upgrade from Bernstein SocGen Group, which elevated the stock to an Outperform rating while substantially raising its price target. The bullish pivot was anchored by proprietary tracking data revealing a quarter-over-quarter surge of over 50 percent in enterprise token consumption across leading artificial intelligence laboratories. As generative AI applications scale rapidly into production, the accompanying compute complexity and query latency require continuous telemetry, infrastructure monitoring, and log management. This dynamic directly converts heavy model usage into billable platform consumption, reassuring investors that accelerating AI workloads are providing a powerful structural tailwind to recurring revenue.
Compounding the positive momentum is noticeable institutional accumulation, highlighted by sizable share acquisitions from major asset managers such as Robeco, along with reported institutional and congressional disclosures. Market participants are actively positioning ahead of the company's upcoming quarterly financial report, seeking high-quality enterprise software names with tangible AI monetization channels. Proprietary tools such as Bits AI and Agent Observability have effectively positioned the enterprise platform to capture value across the entire lifecycle of AI models, shifting the market narrative away from earlier fears of customer budget rationalization toward expectations of resilient enterprise adoption.
The stock's gain was further amplified by broader macroeconomic relief across high-growth enterprise technology equities. A retreat in benchmark Treasury yields helped alleviate discount-rate pressure on premium-valued cloud software vendors, triggering broad-based dip-buying across software platforms. While valuation multiples remain elevated relative to historical sector averages, Datadog's strong gross profit margins, solid balance sheet, and expanding tier of large enterprise clients continue to reinforce institutional confidence in its long-term competitive moat within cloud observability and security.
Technical Analysis of Datadog Inc (DDOG)
Technically, Datadog Inc (DDOG) shows a MACD (12,26,9) value of -5.192, indicating a neutral signal. The RSI at 56.724 suggests neutral condition and the Williams %R at 42.244 suggests buy condition. Please monitor closely.
Fundamental Analysis of Datadog Inc (DDOG)
Datadog Inc (DDOG) is in the Software & IT Services industry. Its latest annual revenue is $3.43B, ranking 84 in the industry. The net profit is $107.74M, ranking 141 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $287.53, a high of $350.00, and a low of $158.00.
More details about Datadog Inc (DDOG)
Company Specific Risks:
- Elevated Valuation Multiple: Trading at a high earnings multiple above 500x and carrying a significant premium over intrinsic fair value estimates, the stock remains highly vulnerable to sudden software sector multiple compressions and interest rate volatility.
- Client Concentration and Contract Downsizing: Datadog faces revenue volatility driven by contract reductions from key customers, highlighted by a $100 million annual recurring revenue reduction from its largest AI client alongside softness across traditional enterprise accounts.
- Competitive Disruption from In-House Tools: Emerging threats from major AI laboratories and cloud hyperscalers developing proprietary internal observability tools present a long-term risk of disintermediation for third-party monitoring platforms.
- Persistent Insider Equity Selling: SEC Form 4 and Form 144 filings indicate sustained insider net selling exceeding $900 million over the past 12 months with zero recorded insider purchases, amplifying market caution ahead of quarterly earnings.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.