


HubSpot Inc Stock (HUBS) Moved Up by 7.07% on Oct 20: Drivers Behind the Movement



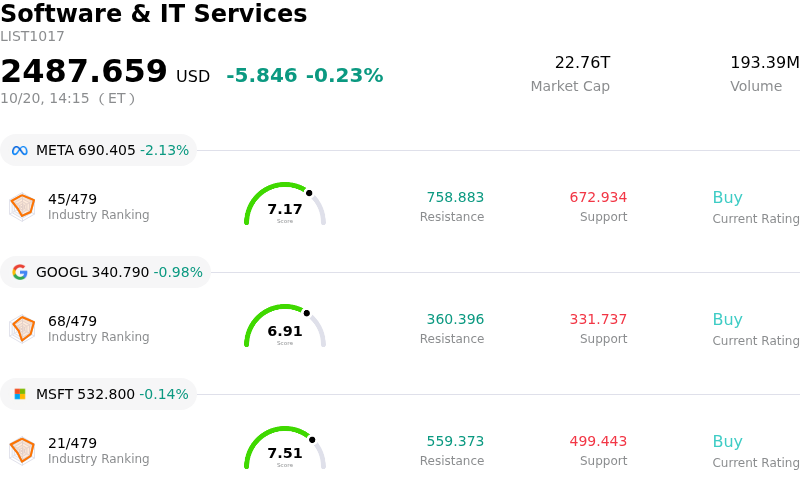
HubSpot Inc (HUBS) moved up by 7.07%. The Software & IT Services sector is down by 0.23%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) down 2.13%; Alphabet Inc Class A (GOOGL) down 0.98%; Microsoft Corp (MSFT) down 0.14%.
What is driving HubSpot Inc (HUBS)’s stock price up today?
HubSpot experienced strong upward momentum driven primarily by a broader capital rotation within the technology sector. Investors shifted capital out of semiconductor and hardware infrastructure trades into high-growth software-as-a-service providers. Prior concerns surrounding software obsolescence due to artificial intelligence have meaningfully eased, replaced by growing confidence that enterprise software platforms with deep customer integrations will effectively monetize AI capabilities. HubSpot's recent product strategy, including its expanded partnership with OpenAI, the launch of its Agent Hub platform, and updated flexible pricing models, has reinforced expectations that the company is well-positioned to capture AI adoption across small and mid-sized businesses.
Market sentiment was further supported by management's operational discipline and strategic alignment. The company recently initiated a corporate restructuring plan to eliminate redundant management layers and align product teams around customer outcomes rather than siloed product lines. While incurring short-term restructuring charges, HubSpot reaffirmed its third-quarter and full-year financial guidance alongside its long-term operating margin targets. This combination of proactive cost discipline and stable top-line trajectory reassured institutional investors regarding the company's margin expansion potential.
From a technical perspective, the stock received a significant boost as price action broke above key technical benchmarks, including its long-term two-hundred-day simple moving average. Reclaiming this critical support level catalyzed systematic and momentum-based buying, accelerating the day's gain. Positive earnings estimate revisions heading into the upcoming quarterly report further solidified investor confidence, providing strong tailwinds for the stock.
Technical Analysis of HubSpot Inc (HUBS)
Technically, HubSpot Inc (HUBS) shows a MACD (12,26,9) value of 6.882, indicating a neutral signal. The RSI at 62.031 suggests neutral condition and the Williams %R at 1.044 suggests overbought condition. Please monitor closely.
Fundamental Analysis of HubSpot Inc (HUBS)
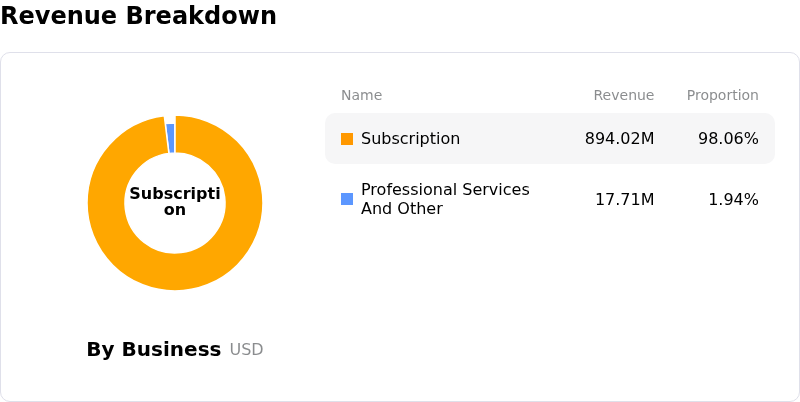
HubSpot Inc (HUBS) is in the Software & IT Services industry. Its latest annual revenue is $3.13B, ranking 89 in the industry. The net profit is $45.91M, ranking 170 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $250.66, a high of $320.00, and a low of $190.00.
More details about HubSpot Inc (HUBS)
Company Specific Risks:
- Analyst Downgrades and Delayed AI Monetization: Wall Street research firms, including Barclays, downgraded the stock citing delays in materializing meaningful AI revenue streams, as increased client budget scrutiny has lengthened sales cycles from a few weeks to nearly five months.
- Workforce Reductions and Restructuring Charges: The company announced a 7% headcount reduction affecting approximately 660 employees, incurring $65 million to $75 million in restructuring and severance costs while highlighting underlying operational efficiency headwinds.
- Pricing Disruption and Execution Headwinds: Ongoing go-to-market strategy shifts and the Q4 testing of a new pricing and consumption model in EMEA create near-term friction that threatens net retention rates and risks slowing net new annual recurring revenue (ARR) growth.
- Decelerating Customer Growth and Pipeline Scrutiny: Net new customer additions have slowed to an estimated 5,000–6,000 per quarter—down sharply from historical quarterly benchmarks of 9,000–10,000—exposing the business to reduced software spending among core small and mid-sized business clients.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.