


ServiceNow Inc Stock (NOW) Moved Down by 5.09% on Oct 16: Drivers Behind the Movement



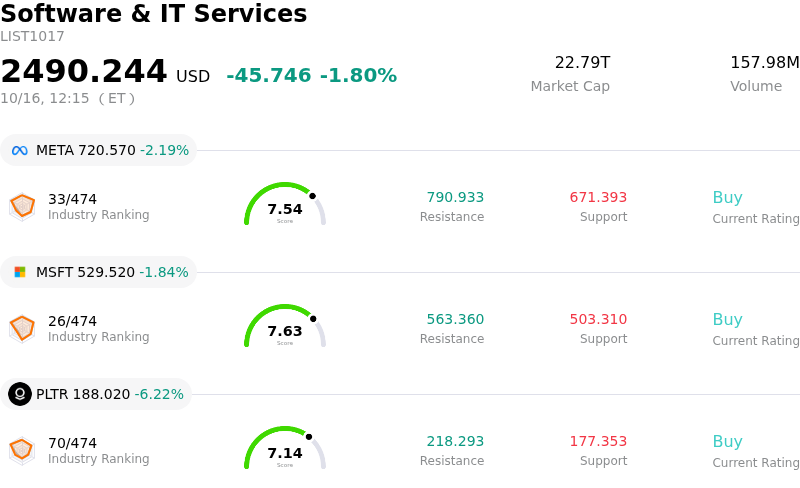
ServiceNow Inc (NOW) moved down by 5.09%. The Software & IT Services sector is down by 1.80%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) down 2.19%; Microsoft Corp (MSFT) down 1.84%; Palantir Technologies Inc (PLTR) down 6.29%.
What is driving ServiceNow Inc (NOW)’s stock price down today?
ServiceNow experienced noticeable downward pressure today, driven primarily by a broader pullback across the enterprise software sector and profit-taking following a strong previous session rally. Enterprise software equities faced macro-level risk-off sentiment as market participants reassessed high-valuation tech names and questioned the timeline for monetizing massive artificial intelligence capital expenditures. Additionally, after ServiceNow gained strong momentum yesterday on major product unveilings—including new generative AI tools and enterprise credentialing systems—short-term traders stepped in to capture gains ahead of the upcoming quarterly earnings release.
Beyond sector rotation and immediate profit-taking, fundamental concerns over software licensing models and operational expenditures continue to weigh on investor sentiment. Wall Street remains focused on potential seat rationalization, where traditional per-user subscription models face structural disruption from autonomous AI agents that handle tasks with fewer human credentials. While ServiceNow has proactively introduced consumption-based pricing options and no-code deployment platforms to defend its workflow franchise, the transition introduces revenue predictability risks. Furthermore, elevated sales, engineering, and infrastructure investments continue to put pressure on operating margins, heightening stock price sensitivity when trading at premium valuation multiples.
Looking ahead, institutional focus is shifting directly to ServiceNow's approaching third-quarter financial results and remaining performance obligation metrics. Investors will be scrutinizing current remaining performance obligation growth and executive commentary regarding enterprise IT budget trends, particularly within public sector accounts where spending has shown historical volatility. Until clear evidence demonstrates that AI product expansion translates directly into margin expansion and sustained subscription contract acceleration, the stock remains susceptible to heightened volatility driven by sector shifts and sentiment rebalancing.
Technical Analysis of ServiceNow Inc (NOW)
Technically, ServiceNow Inc (NOW) shows a MACD (12,26,9) value of 0.722, indicating a buy signal. The RSI at 53.674 suggests neutral condition and the Williams %R at 52.492 suggests neutral condition. Please monitor closely.
Media Coverage of ServiceNow Inc (NOW)
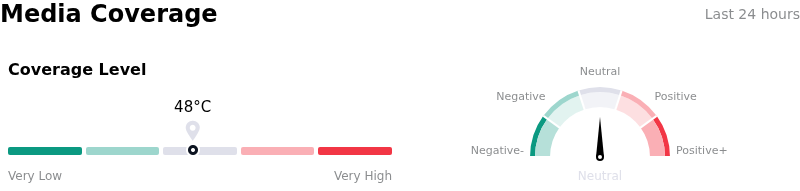
In terms of media coverage, ServiceNow Inc (NOW) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of ServiceNow Inc (NOW)
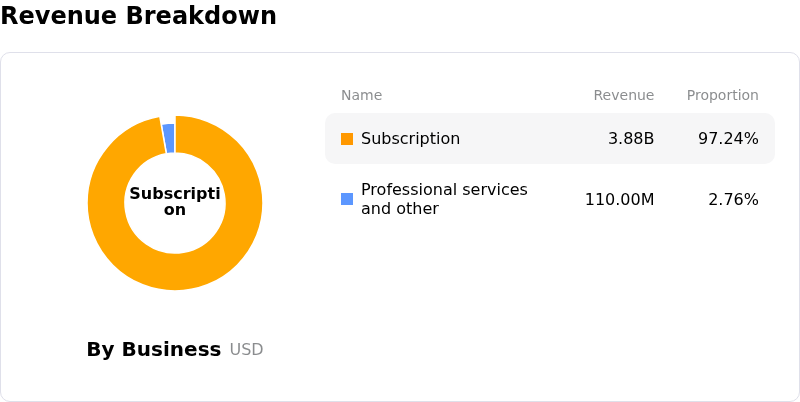
ServiceNow Inc (NOW) is in the Software & IT Services industry. Its latest annual revenue is $13.28B, ranking 28 in the industry. The net profit is $1.75B, ranking 30 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $155.19, a high of $248.00, and a low of $72.00.
More details about ServiceNow Inc (NOW)
Company Specific Risks:
- U.S. Federal Demand Softness and Enterprise Seat Rationalization: Recent analyst channel checks indicate U.S. federal obligations dropped 16% year-over-year to $424 million, significantly trailing historical seasonal averages as government agencies and enterprise clients rationalized software seat counts and tightened IT budgets.
- Operating Margin Compression from Heavy Generative AI R&D Spending: Substantial capital allocation toward generative AI development—including tools such as EmployeeWorks, Flow, and AI Passport—along with elevated sales and software engineering expenses has squeezed operating margins, causing profit growth to lag subscription revenue expansion.
- Uncertain Monetization Timelines for New Consumption-Based AI Tools: The deployment of standalone AI offerings introduces revenue predictability risks, as product launches lack immediate adoption forecasts or guaranteed incremental revenue, raising concerns over whether consumption-based pricing can match traditional multi-year enterprise licenses.
- Valuation Multiples Heightening Volatility Ahead of Q3 Earnings: Carrying a premium forward price-to-earnings ratio above 33x, the stock remains highly sensitive to intraday swings, leaving shares vulnerable if upcoming quarterly results or current remaining performance obligations (cRPO) guidance fail to surpass elevated market estimates.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.