


Accenture PLC Stock (ACN) Moved Up by 4.33% on Oct 15: Key Drivers Unveiled



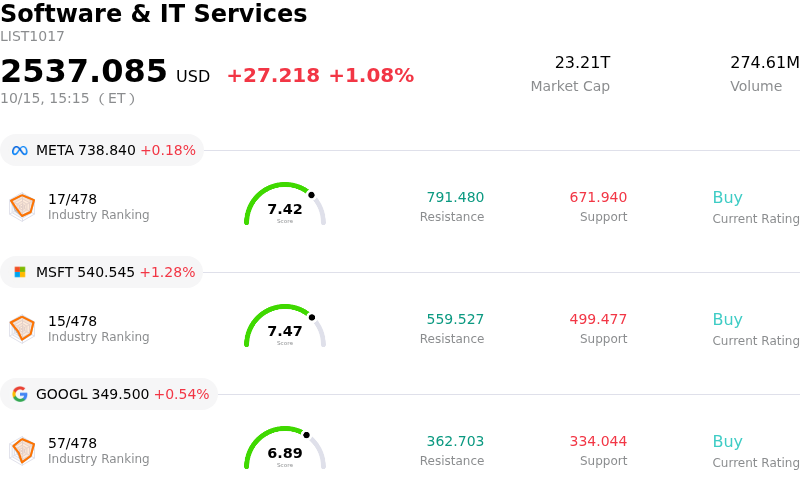
Accenture PLC (ACN) moved up by 4.33%. The Software & IT Services sector is up by 1.08%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 0.20%; Microsoft Corp (MSFT) up 1.28%; Alphabet Inc Class A (GOOGL) up 0.50%.
What is driving Accenture PLC (ACN)’s stock price up today?
Accenture experienced positive upward momentum driven primarily by market reaction to its multi-year strategic roadmap presented during its recent investor day. Management outlined clear financial targets for fiscal years 2027 through 2029, projecting steady mid-single-digit local currency revenue growth over the next two fiscal years followed by an acceleration to mid-to-high single-digit growth in fiscal 2029. Crucially, the company committed to annual operating margin expansion of 10 to 30 basis points and reaffirmed a disciplined capital return framework featuring significant share repurchases and growing dividends. This long-term outlook provided institutional investors with reassuring visibility, directly addressing market concerns regarding potential AI disruption to traditional consulting business models.
The bullish trajectory is further reinforced by Accenture's strategic positioning within enterprise generative and agentic artificial intelligence. Recent announcements, including a joint forward-deployed engineering initiative with Workday and expanded infrastructure collaborations with Dell Technologies, highlight the company's role in helping clients scale complex AI deployments. Furthermore, strategic acquisitions in customer intelligence and specialized digital engineering continue to enhance its service capabilities. These initiatives demonstrate Accenture's ability to turn enterprise AI adoption from a competitive threat into a high-margin growth vector, as evidenced by expanding enterprise bookings.
From a valuation perspective, the stock had experienced multiple compression earlier in the year as markets priced in slowing enterprise IT expenditures. Today's upward price movement reflects a valuation re-rating as market participants recognize the company's resilient free cash flow, robust balance sheet, and market leadership. Supported by a recent fiscal fourth-quarter earnings beat that delivered record large-scale client bookings, the stock is seeing heightened institutional buying interest as investors gain confidence in the firm's multi-year execution path.
Technical Analysis of Accenture PLC (ACN)
Technically, Accenture PLC (ACN) shows a MACD (12,26,9) value of 5.632, indicating a buy signal. The RSI at 70.037 suggests buy condition and the Williams %R at 6.230 suggests overbought condition. Please monitor closely.
Media Coverage of Accenture PLC (ACN)
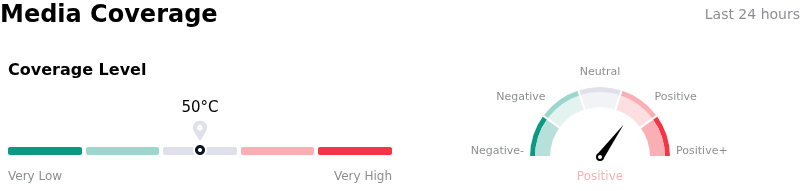
In terms of media coverage, Accenture PLC (ACN) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Accenture PLC (ACN)
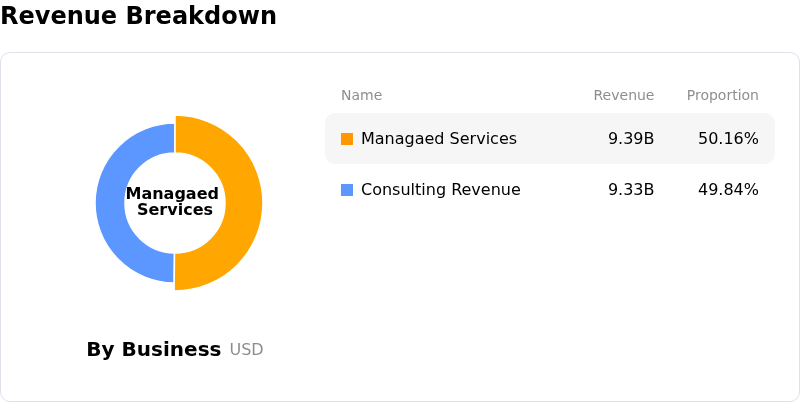
Accenture PLC (ACN) is in the Software & IT Services industry. Its latest annual revenue is $74.18B, ranking 6 in the industry. The net profit is $8.37B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $229.65, a high of $329.00, and a low of $185.00.
More details about Accenture PLC (ACN)
Company Specific Risks:
- Core Business Growth Stagnation: Filings surrounding Accenture's October 14 Investor Day (Form 8-K) and management commentary revealed that its core IT consulting and outsourcing business—representing 94% of total revenue—is projected to see minimal near-term expansion, leaving fiscal 2027 organic revenue growth at a sluggish 0.5% to 3.5%.
- Generative AI Structural Disruption: Wall Street analysts highlighted immediate concerns that enterprise adoption of generative AI and automated agents is commoditizing traditional billable consulting hours, threatening long-term operating margin compression across legacy service lines.
- Over-Reliance on Inorganic M&A Expansion: To achieve its top-line target, Accenture remains heavily dependent on inorganic M&A to generate roughly 2.5 percentage points of its fiscal 2027 revenue growth, elevating capital allocation, execution, and integration risks amid elevated deal-making budgets.
- Persistent Enterprise Discretionary Budget Deferrals: Institutional analysts noted ongoing caution and pricing pressures across corporate IT departments, as enterprise clients continue deferring discretionary strategy consulting contracts and high-margin advisory engagements.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.