


Philip Morris International Inc Stock (PM) Closed Up by 3.16% on Oct 14: A Full Analysis



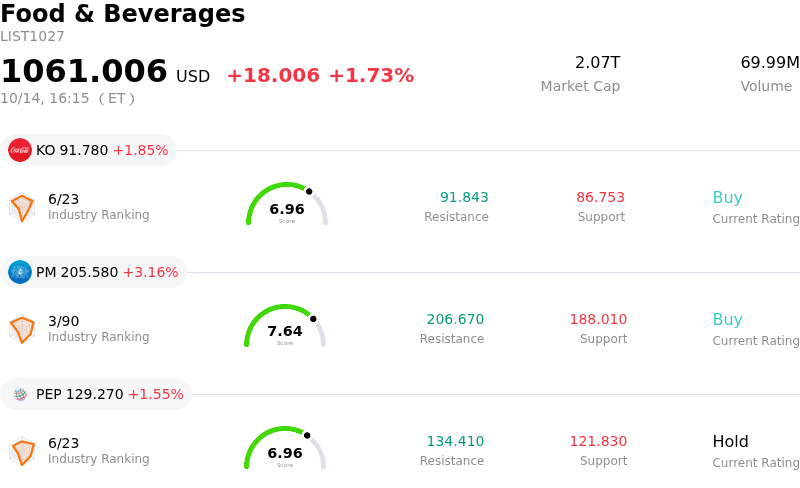
Philip Morris International Inc (PM) closed up by 3.16%. The Food & Beverages sector is up by 1.73%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Coca-Cola Co (KO) up 1.85%; Philip Morris International Inc (PM) up 3.16%; PepsiCo Inc (PEP) up 1.55%.
What is driving Philip Morris International Inc (PM)’s stock price up today?
Philip Morris International demonstrated solid upward momentum and heightened trading volatility as market sentiment rallied ahead of the company's upcoming third-quarter earnings release. Institutional positioning in options markets and equity flows reflected growing investor confidence in the business's financial trajectory. Market participants are increasingly anticipating top- and bottom-line expansion, bolstered by positive analyst estimate revisions and a consistent history of quarterly earnings beats that highlight operational resilience.
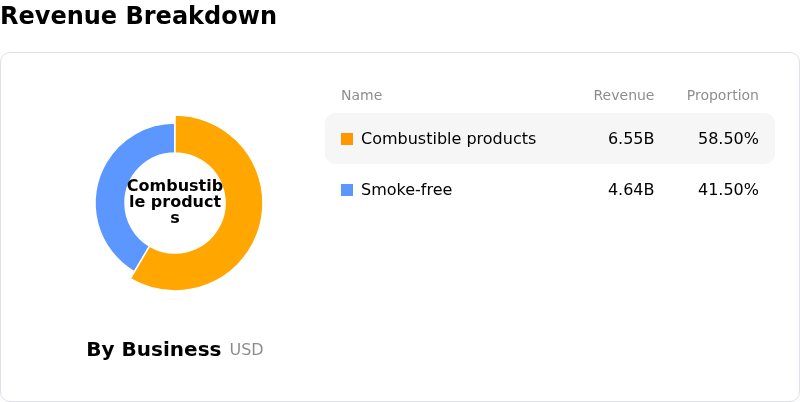
Underpinning this bullish sentiment is the sustained acceleration of Philip Morris's smoke-free transformation, spearheaded by key growth platforms such as IQOS heated tobacco systems and ZYN oral nicotine pouches. The expanding weight of smoke-free offerings within total net revenues has enhanced margin profiles and diversified revenue streams away from traditional combustible products. Furthermore, the recent dividend increase underscores management's commitment to robust capital returns, reinforcing the stock's appeal to income-oriented investors seeking stability.
From a macroeconomic perspective, consumer defensive equities equipped with strong pricing power and reliable cash flows continue to attract steady institutional capital amid broader market swings. Although current valuation metrics trade at a premium relative to historical averages, investors remain focused on commercial execution and category leadership in reduced-risk alternatives. Near-term trading volatility may persist as the earnings date nears, but the overarching trend reflects confidence in the company's strategic growth strategy.
Technical Analysis of Philip Morris International Inc (PM)
Technically, Philip Morris International Inc (PM) shows a MACD (12,26,9) value of 3.000, indicating a buy signal. The RSI at 70.070 suggests buy condition and the Williams %R at 1.287 suggests overbought condition. Please monitor closely.
Media Coverage of Philip Morris International Inc (PM)
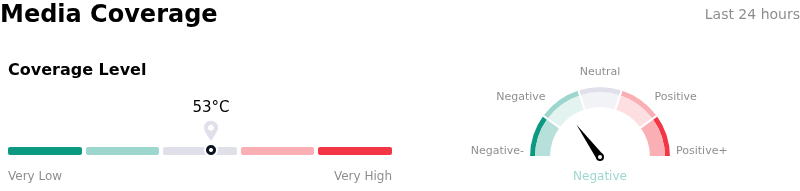
In terms of media coverage, Philip Morris International Inc (PM) shows a coverage score of 53, indicating a moderate level of media attention. The overall market sentiment index is currently in bearish zone.
Fundamental Analysis of Philip Morris International Inc (PM)
Philip Morris International Inc (PM) is in the Food & Beverages industry. Its latest annual revenue is $40.65B, ranking 5 in the industry. The net profit is $11.32B, ranking 1 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $202.71, a high of $225.00, and a low of $151.00.
More details about Philip Morris International Inc (PM)
Company Specific Risks:
- Elevated Valuation Premium and Overvaluation Risk: Philip Morris is trading at a trailing P/E ratio near 28.8x—more than 50% above its five-year median valuation—leaving the stock vulnerable to sharp intraday pullbacks and multiple contraction if market sentiment shifts.
- Consensus Expectations Exceeding Internal Guidance: Ahead of the upcoming Q3 earnings print, Wall Street consensus estimates of $2.29 to $2.31 per share exceed management's official guidance range of $2.20 to $2.25 per share, creating substantial risk of an earnings-day miss or downside guidance disappointment.
- Intensifying Global Regulatory and Policy Tightening: Heightened regulatory scrutiny over smoke-free and nicotine pouch products, including upcoming marketing restrictions in European markets and proposed flavor limits in international regions, threatens long-term growth trajectories for next-generation offerings.
- Smoke-Free Shipment Volatility and Escalating Pouch Competition: Irregularities in ZYN volume trajectory alongside aggressive modern oral pouch expansion by key global competitors introduce execution risk to the company's smoke-free revenue momentum.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.