


Valero Energy Corp Stock (VLO) Moved Up by 3.44% on Oct 5: Facts Behind the Movement



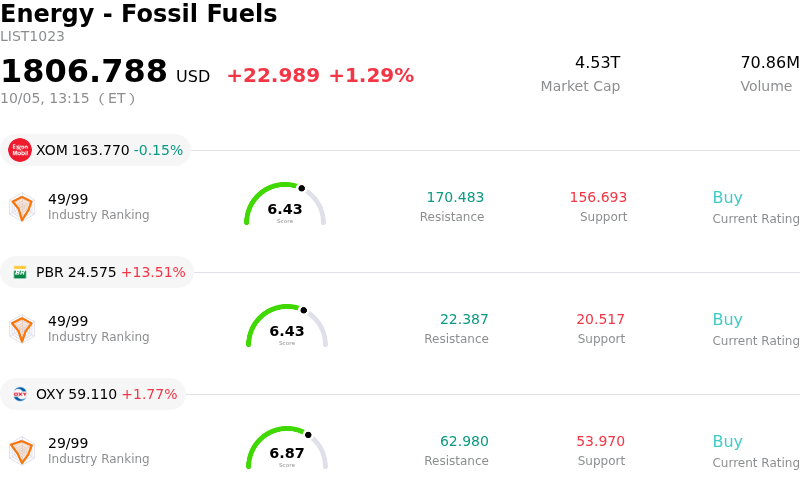
Valero Energy Corp (VLO) moved up by 3.44%. The Energy - Fossil Fuels sector is up by 1.29%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Exxon Mobil Corp (XOM) down 0.15%; Petroleo Brasileiro SA Petrobras (PBR) up 13.51%; Occidental Petroleum Corp (OXY) up 1.77%.
What is driving Valero Energy Corp (VLO)’s stock price up today?
Valero Energy experienced strong upward price action driven by favorable industry fundamentals, positive momentum in the refining sector, and strong analyst sentiment ahead of its upcoming quarterly earnings release. Investors are increasingly optimistic about the company's financial performance as tight global supply conditions, particularly in middle distillates such as diesel and jet fuel, continue to keep refining crack spreads well above historical averages. With global refining capacity constrained due to geopolitical disruptions and seasonal turnarounds, high-complexity U.S. Gulf Coast refiners like Valero remain exceptionally well-positioned to capitalize on high throughput demand and elevated product margins.
The rally is further reinforced by a series of bullish analyst revisions and strong earnings expectations. Wall Street consensus has steadily increased earnings estimates for the third quarter and full year, reflecting robust throughput volumes, disciplined cost management, and favorable feedstock pricing. Recent target price increases from major brokerage firms have highlighted Valero's superior operational execution and sustained free cash flow generation. Market participants are actively positioning ahead of the company's scheduled third-quarter financial results, betting on another earnings surprise driven by persistent strength in refining margins.
From a broader perspective, macroeconomic factors and global supply dynamics continue to favor independent refiners. Resilient transportation fuel demand combined with low global distillate inventories provides a solid floor for corporate profitability. Although potential news regarding emergency fuel reserve releases or broader market volatility may induce temporary intraday price swings, the underlying structural tight capacity in global refining ensures that low-cost domestic operators maintain a durable competitive advantage. Consequently, strong institutional support and positive momentum indicators continue to drive investor interest in the stock.
Technical Analysis of Valero Energy Corp (VLO)
Technically, Valero Energy Corp (VLO) shows a MACD (12,26,9) value of 0.308, indicating a buy signal. The RSI at 70.480 suggests buy condition and the Williams %R at 0.270 suggests overbought condition. Please monitor closely.
Fundamental Analysis of Valero Energy Corp (VLO)
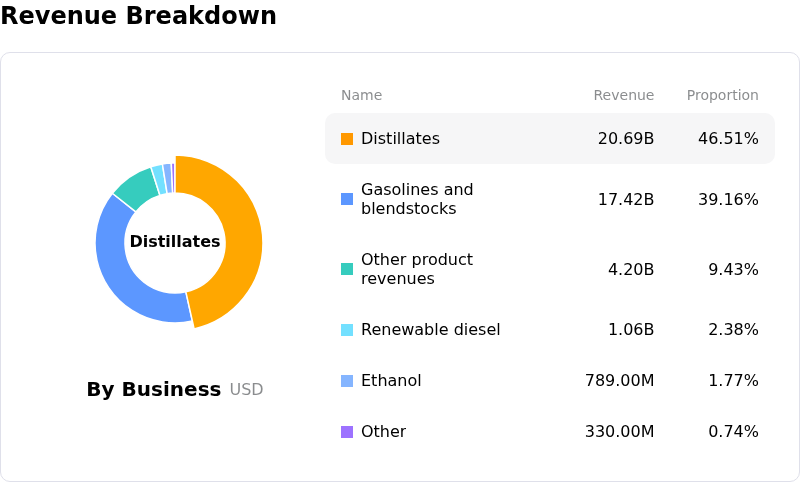
Valero Energy Corp (VLO) is in the Energy - Fossil Fuels industry. Its latest annual revenue is $115.97B, ranking 8 in the industry. The net profit is $2.34B, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $345.47, a high of $450.00, and a low of $193.45.
More details about Valero Energy Corp (VLO)
Company Specific Risks:
- Refining Margin and Crack Spread Compression: High sensitivity to 3-2-1 crack spreads exposes profitability to cyclical normalization, as rebuilding fuel inventories and returning global refining capacity threaten to erode elevated margins per barrel.
- Regulatory Compliance and Mandate Costs: Escalating environmental regulations, including shifting Renewable Fuel Standard compliance obligations and state-level operational constraints in key regions, threaten to inflate operating expenses and compress net margins.
- High Utilization Operational Vulnerability: Operating processing facilities near peak utilization leaves refining operations highly sensitive to margin compression caused by unscheduled refinery downtime, turnaround delays, or regional weather disruptions.
- Peak-Cycle Earnings and Valuation Risk: Forward earnings models projecting mid-term margin decay alongside insider share sales reflect elevated downside risks if macro refined product demand softens toward historical mid-cycle levels.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.