


Royal Caribbean Cruises Ltd Stock (RCL) Moved Up by 5.34% on Sep 24: Drivers Behind the Movement



Royal Caribbean Cruises Ltd (RCL) moved up by 5.34%. The Cyclical Consumer Services sector is up by 1.27%. The company outperformed the industry. Top 3 stocks by turnover in the sector: McDonald's Corp (MCD) up 0.73%; Warner Bros Discovery Inc (WBD) down 0.03%; Royal Caribbean Cruises Ltd (RCL) up 5.45%.
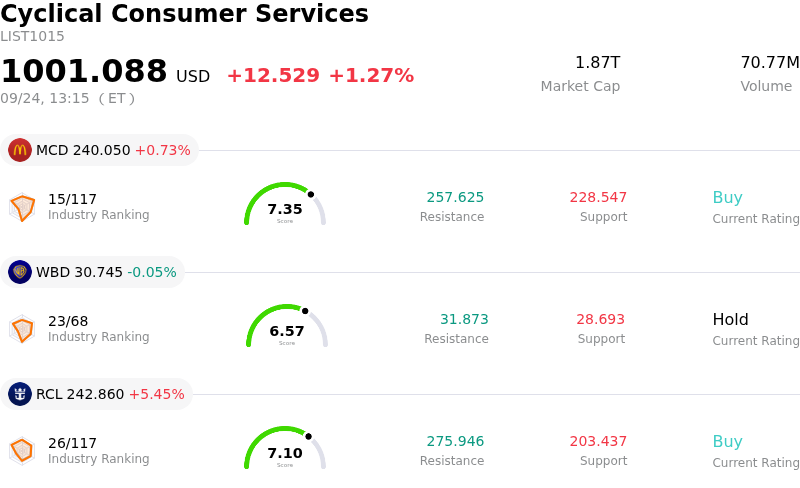
What is driving Royal Caribbean Cruises Ltd (RCL)’s stock price up today?
The upward movement in Royal Caribbean Group’s equity was primarily driven by a sharp technical rebound following an oversold selloff, combined with strong institutional buying prompted by major Wall Street analyst price target upgrades. After experiencing intense selling pressure surrounding the announcement of a massive land-based resort expansion, momentum indicators dipped into oversold territory, attracting bargain hunters and short-covering activity. Sentiment was further bolstered by major investment banks, notably JPMorgan Chase, which significantly raised its price target for the cruise operator while maintaining an Overweight rating, highlighting substantial prospective upside from depressed levels.
Market participants also began re-evaluating the strategic implications of Royal Caribbean's joint venture acquisition of a fifty percent stake in Sandals and Beaches Resorts. While initial market reaction reflected anxiety over the debt-financed nature of the transaction and existing balance sheet obligations, institutional investors increasingly focused on the deal's reasonable forward valuation multiple and its projected accretive impact on earnings after closing. The venture broadens Royal Caribbean's land-based vacation ecosystem, creating cross-distribution channels across its core cruise fleet and expanding its addressable share of consumer travel spending.
The underlying fundamental health of the business continues to provide a supportive floor for valuation. Royal Caribbean's recent quarterly operating performance demonstrated resilient consumer demand, strong booking yields, and robust onboard revenue growth, supporting a positive full-year earnings outlook. Trading at a notable valuation discount compared to broader hospitality industry peers and its own historical multiples, the stock presented an attractive risk-reward profile for long-term equity investors reassessing the balance between capital commitment risks and structural growth opportunities.
Technical Analysis of Royal Caribbean Cruises Ltd (RCL)
Technically, Royal Caribbean Cruises Ltd (RCL) shows a MACD (12,26,9) value of -1.832, indicating a sell signal. The RSI at 34.829 suggests neutral condition and the Williams %R at 56.499 suggests sell condition. Please monitor closely.
Media Coverage of Royal Caribbean Cruises Ltd (RCL)
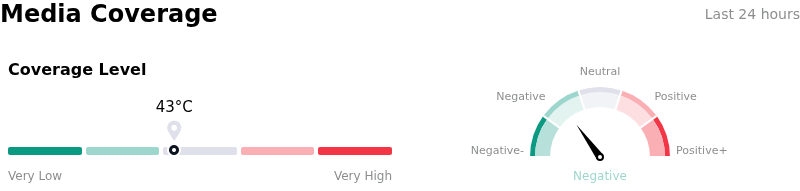
In terms of media coverage, Royal Caribbean Cruises Ltd (RCL) shows a coverage score of 43, indicating a moderate level of media attention. The overall market sentiment index is currently in bearish zone.
Fundamental Analysis of Royal Caribbean Cruises Ltd (RCL)
Royal Caribbean Cruises Ltd (RCL) is in the Cyclical Consumer Services industry. Its latest annual revenue is $17.93B, ranking 7 in the industry. The net profit is $4.27B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $346.87, a high of $425.00, and a low of $259.71.
More details about Royal Caribbean Cruises Ltd (RCL)
Company Specific Risks:
- Balance Sheet Leverage from $3 Billion Sandals Acquisition: Royal Caribbean filed a Form 8-K on September 23, 2026, confirming a $3.0 billion debt-financed transaction to acquire a 50% stake in Sandals and Beaches Resorts. The acquisition, funded via new debt committed by Morgan Stanley, increases net balance sheet leverage on top of the company's existing $23.4 billion debt load, raising investor concern over impending debt maturities in 2027 and 2028.
- Strategic Diversification and Land-Based Operational Risks: Wall Street analysts at Stifel and Truist Securities highlighted execution risks associated with Royal Caribbean expanding outside its core cruise competency into land-based hospitality. Analysts emphasized that fixed land-based resort assets carry structural liabilities—including direct exposure to Caribbean weather and hurricane disruptions—that cannot be managed by repositioning ships like traditional cruise operations.
- Technical Breakdown and Insider Selling Overhang: RCL shares plunged over 6% to 52-week lows near $222–$234 following the deal announcement, dropping sharply below both 20-day and 50-day moving averages and driving RSI indicators to deeply oversold levels. Institutional selling pressure is exacerbated by historical insider sales totaling hundreds of millions of dollars over the past year and complete market surprise regarding the non-core acquisition.
- Unhedged Fuel Exposure and Margin Compression: Royal Caribbean carries a 42% unhedged fuel position for fiscal 2026, leaving profitability highly vulnerable to spikes in benchmark crude oil prices. Furthermore, despite revenue growth and strong booking volumes, recent financial performance showed underlying adjusted EBITDA margin contraction, creating ongoing friction for free cash flow generation.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.