


Eli Lilly and Co Stock (LLY) Moved Up by 3.73% on Sep 24: A Full Analysis



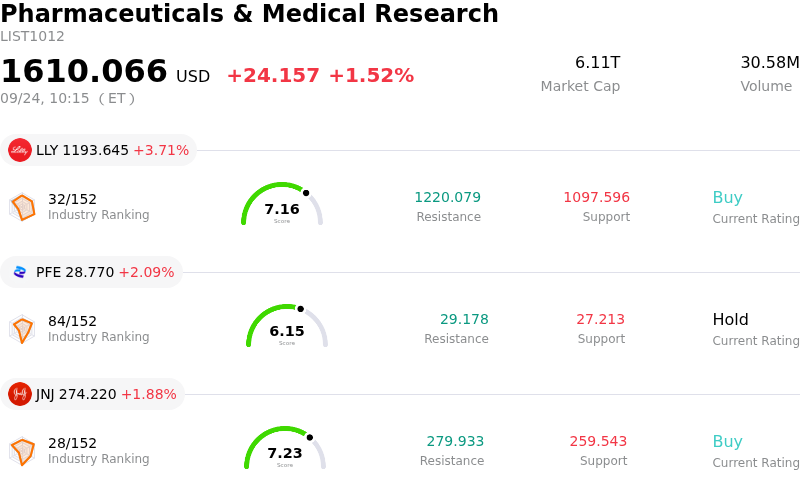
Eli Lilly and Co (LLY) moved up by 3.73%. The Pharmaceuticals & Medical Research sector is up by 1.52%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) up 3.73%; Pfizer Inc (PFE) up 2.09%; Johnson & Johnson (JNJ) up 1.88%.
What is driving Eli Lilly and Co (LLY)’s stock price up today?
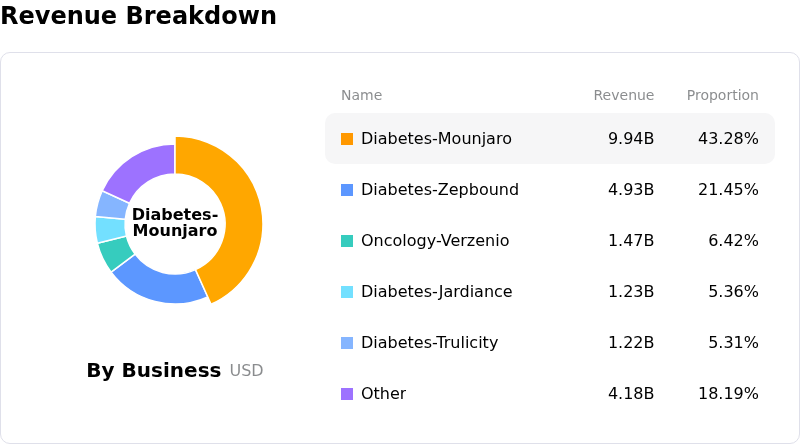
Eli Lilly experienced upward share price momentum, driven primarily by major regulatory developments in its core cardiometabolic portfolio. The U.S. Food and Drug Administration granted approval for Onswik, the company's novel once-weekly basal insulin designed for adults with type 2 diabetes. This regulatory win expands Eli Lilly's leadership in diabetes care by replacing daily injection regimens with a once-weekly alternative, offering substantial market adoption potential. Investors reacted positively to this milestone, which reinforces the pharmaceutical giant's continuous pipeline execution alongside its dominant incretin therapy footprint featuring Mounjaro and Zepbound.
Compounding the regulatory breakthrough is robust commercial traction across Eli Lilly's metabolic franchise. Recent operational updates highlighted expanding market share for its oral GLP-1 treatment, supported by broader Medicare coverage for obesity therapies. To address elevated global demand and prevent supply bottlenecks, the company recently broke ground on a massive multi-billion-dollar manufacturing facility in Houston dedicated to scaling production. This aggressive capital deployment demonstrates management's commitment to converting pipeline innovations into sustainable revenue growth, satisfying institutional demand for long-term scalability.
Positive sentiment was further supported by Wall Street analyst commentary and upward target price revisions across major investment research firms. Institutional analysts pointed to Eli Lilly's industry-leading return on research investment, strong operating margins, and expanding market share relative to global competitors. With forward earnings expectations continuing to be revised upward ahead of the upcoming quarterly reporting cycle, institutional investors view the stock's risk-reward profile favorably. The convergence of new product approvals, manufacturing scale, and favorable broker upgrades provided clear momentum for the stock's movement.
Technical Analysis of Eli Lilly and Co (LLY)
Technically, Eli Lilly and Co (LLY) shows a MACD (12,26,9) value of 10.214, indicating a neutral signal. The RSI at 56.661 suggests neutral condition and the Williams %R at 1.992 suggests overbought condition. Please monitor closely.
Media Coverage of Eli Lilly and Co (LLY)
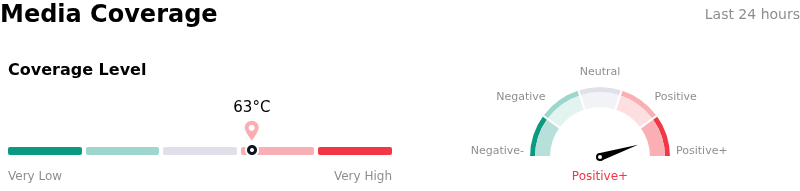
In terms of media coverage, Eli Lilly and Co (LLY) shows a coverage score of 63, indicating a high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Eli Lilly and Co (LLY)
Eli Lilly and Co (LLY) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $65.18B, ranking 4 in the industry. The net profit is $20.64B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1306.81, a high of $1600.00, and a low of $891.22.
More details about Eli Lilly and Co (LLY)
Company Specific Risks:
- Emerging GLP-1 Litigation and Adverse Side Effect Claims: Recent legal filings and reporting highlight growing product liability lawsuits targeting Eli Lilly over alleged severe adverse effects, including vision loss risks and gastroparesis associated with its GLP-1 treatments like Mounjaro and Zepbound, introducing potential financial liabilities and regulatory scrutiny.
- Valuation Premium and Incretin Revenue Concentration: Trading at an elevated forward P/E ratio near 32x—roughly double the broader pharmaceutical industry benchmark of 16x—the stock remains vulnerable to rapid intraday multiple contraction if GLP-1 revenue growth decelerates or if insurance payer price pressures intensify.
- R&D Complexity in Multi-Target Licensing Collaborations: Recent early-stage research agreements, including the partnership with InnoCare Pharma to pursue up to five new specialty drug candidates, increase R&D operational complexity and early-stage trial failure risk as Eli Lilly attempts to diversify away from its core GLP-1 portfolio.
- Capital Outlay and Execution Risk on Manufacturing Expansion: Breaking ground on a massive $6.5 billion active pharmaceutical ingredient production site in Houston as part of a $50 billion domestic manufacturing push exposes the firm to construction delays, cost overruns, and operational execution bottlenecks for its oral weight-loss drug Foundayo.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.