


Wayfair Inc Stock (W) Moved Down by 7.71% on Sep 23: Key Drivers Unveiled



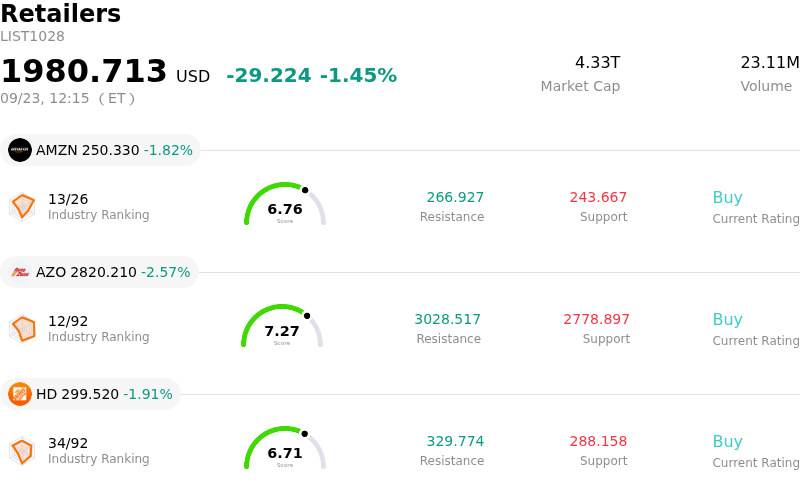
Wayfair Inc (W) moved down by 7.71%. The Retailers sector is down by 1.45%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Amazon.com Inc (AMZN) down 1.82%; Autozone Inc (AZO) down 2.57%; Home Depot Inc (HD) down 1.91%.
What is driving Wayfair Inc (W)’s stock price down today?
Wayfair shares experienced notable downside pressure as broader macroeconomic headwinds and profit-taking converged on high-beta consumer discretionary stocks. A risk-off tone across equity markets, driven by elevated Treasury yields following recent Federal Reserve rate decisions and persistent inflationary concerns, created a challenging environment for rate-sensitive e-commerce retailers. Because Wayfair's business model is closely tied to home improvement activity, housing turnover, and discretionary household spending, broader market anxieties over sustained higher borrowing costs triggered selling across the sector.
Adding to the downward momentum was growing investor sensitivity around corporate insider activity and valuation levels. Regulatory filings disclosed significant insider stock sales by top leadership, including the chief executive officer and co-chairman. Although these transactions were executed under pre-established trading plans, the sizable share disposals prompted market participants to question near-term upside potential, especially after the stock had staged a dramatic recovery over recent months. The resulting profit-taking reflected a valuation reset as traders reassessed risk exposure against the company's leveraged balance sheet.
The pullback occurred despite constructive operational updates and supportive commentary from Wall Street analysts. Wall Street firms recently reiterated positive ratings based on Wayfair's market share gains, improved cash flow generation, and new marketing initiatives, including its national brand platform launch. Credit rating agencies have also noted progress in the company's credit metrics. However, in the immediate term, macro rate headwinds and insider selling concerns overshadowed these fundamental tailwinds, leading to heightened intraday volatility.
Technical Analysis of Wayfair Inc (W)
Technically, Wayfair Inc (W) shows a MACD (12,26,9) value of 0.060, indicating a buy signal. The RSI at 47.199 suggests neutral condition and the Williams %R at 74.091 suggests sell condition. Please monitor closely.
Fundamental Analysis of Wayfair Inc (W)
Wayfair Inc (W) is in the Retailers industry. Its latest annual revenue is $12.46B, ranking 12 in the industry. The net profit is $-313.00M, ranking 31 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $121.20, a high of $156.00, and a low of $63.00.
More details about Wayfair Inc (W)
Company Specific Risks:
- Substantial Insider Stock Liquidations: Recent SEC filings disclosed that Co-Founder and Co-Chairman Steven Conine along with CEO Niraj Shah combined to sell approximately $14 million in equity—including Conine liquidating nearly 19% of his direct holdings—creating significant market overhang and raising investor concern over executive confidence following the stock's recent run-up.
- Housing Market Stagnation and Interest Rate Exposure: Persistent high interest rates and depressed housing turnover present immediate top-line risks, direct curtailments on big-ticket furniture demand, and broader headwinds for consumer discretionary spending across online channels.
- Stretched Multiples Relative to Profitability and Debt Load: Trading at an elevated Price-to-Sales ratio near 1.0x, Wayfair remains vulnerable to valuation recalibration due to its low single-digit operating margins and substantial $3.52 billion total debt burden compared to higher-margin industry peers.
- High Customer Acquisition Costs in a Fragmented Sector: Operating in a highly competitive e-commerce landscape without strong consumer stickiness or moat protection, Wayfair faces potential margin compression if spending on advertising and customer acquisition accelerates to maintain volume.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.