


Grab Holdings Ltd Stock (GRAB) Moved Up by 7.90% on Sep 22: What Signal Does It Send?



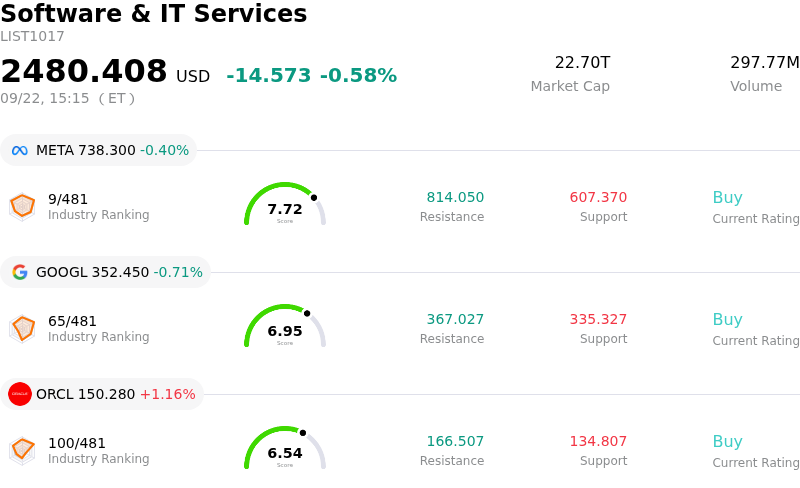
Grab Holdings Ltd (GRAB) moved up by 7.90%. The Software & IT Services sector is down by 0.58%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) down 0.40%; Alphabet Inc Class A (GOOGL) down 0.71%; Oracle Corp (ORCL) up 1.25%.
What is driving Grab Holdings Ltd (GRAB)’s stock price up today?
The primary catalyst driving the upward momentum in Grab Holdings shares is a substantial vote of confidence from top leadership. Recent regulatory filings revealed that Chief Executive Officer Anthony Tan executed a massive open-market purchase of over ten million shares, totaling nearly thirty million dollars. President and Chief Operating Officer Alexander Hungate also made notable open-market share purchases. Following a period of broader weakness for the stock, these sizeable personal financial commitments by senior management serve as a strong signal of insider confidence in the company's trajectory and underlying valuation, providing a strong psychological floor for the market.
Investor sentiment is further supported by Grab's strategic expansion in its financial services division and an upgraded medium-term outlook. The company announced an agreement to acquire a controlling majority stake in Atome Financial, a buy-now-pay-later and consumer lending platform in Southeast Asia. This transaction significantly enhances Grab's fintech footprint by expanding its consumer loan portfolio and merchant partner network. Following the deal, management raised its medium-term revenue growth target through 2028 and increased its group adjusted EBITDA expectations, convincing investors that its evolution into a comprehensive super-app can deliver profitable growth.
Underpinning these growth catalysts is a disciplined capital management policy backed by a robust balance sheet. Grab reiterated its intention to complete nine hundred million dollars in authorized share buybacks over the next twelve months, which will bring total cumulative repurchases to nearly two billion dollars since 2024. Coupled with steady revenue growth in its core ride-hailing and delivery businesses, the combination of aggressive insider buying, ongoing share repurchases, and strategic fintech consolidation provides institutional investors with renewed confidence in the company's valuation upside.
Technical Analysis of Grab Holdings Ltd (GRAB)
Technically, Grab Holdings Ltd (GRAB) shows a MACD (12,26,9) value of -0.031, indicating a sell signal. The RSI at 46.184 suggests neutral condition and the Williams %R at 50.307 suggests neutral condition. Please monitor closely.
Fundamental Analysis of Grab Holdings Ltd (GRAB)
Grab Holdings Ltd (GRAB) is in the Software & IT Services industry. Its latest annual revenue is $3.37B, ranking 85 in the industry. The net profit is $268.00M, ranking 94 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $5.79, a high of $8.00, and a low of $4.60.
More details about Grab Holdings Ltd (GRAB)
Company Specific Risks:
- M&A Integration and Credit Risk from Atome Deal: Grab's $1.49 billion cash acquisition of a 60% controlling stake in Atome Financial introduces severe execution and integration risk, exposing the company's financial services division to elevated consumer credit defaults and buy-now-pay-later loan exposure.
- Regulatory Probes and Driver Stoppages in Southeast Asia: Regulators, including Vietnam's National Competition Commission, have initiated formal reviews into Grab's platform commissions, hidden fees, and pricing practices following driver work stoppages over declining compensation.
- High Incentive Expenditures Dragging Profitability: Massive partner and customer incentive outlays—totaling over $700 million—continue to compress margins as Grab aggressively subsidizes rides and deliveries to hold market share against fierce regional rivals such as GoTo and Line Man.
- Wall Street Rating Downgrades and Technical Fragility: Recent analyst rating downgrades from firms including HSBC (Hold) and Weiss Ratings (Sell) highlight institutional skepticism regarding Grab's premium valuation multiple relative to lingering profitability deficits and multi-week stock weakness.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.