


Shopify Inc Stock (SHOP) Opened Up by 7.05% on Sep 22: What Signal Does It Send?



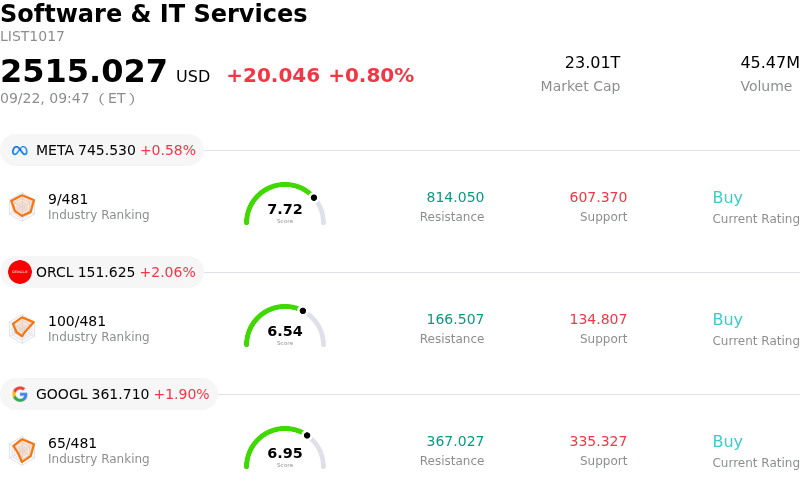
Shopify Inc (SHOP) opened up by 7.05%. The Software & IT Services sector is up by 0.80%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 0.69%; Oracle Corp (ORCL) up 2.06%; Alphabet Inc Class A (GOOGL) up 1.77%.
What is driving Shopify Inc (SHOP)’s stock price up today?
Shopify experienced significant upward momentum following the high-profile announcement of its strategic partnership with Meta Platforms. Under this collaboration, Meta's newly launched Muse AI assistant directly integrates Shopify's checkout engine, allowing consumers to discover products and seamlessly execute purchases via Shop Pay across millions of hosted merchant storefronts. This strategic move highlights Shopify's positioning as an open, developer-friendly ecosystem for agentic commerce, contrasting sharply with key marketplace competitors that have chosen to restrict third-party AI agents. Investors responded enthusiastically to the deal, recognizing that enabling autonomous AI-driven shopping experiences can unlock new channels of merchant gross merchandise volume and transaction revenues.
The rally was further amplified by broader strength in the technology sector and a market-wide appetite for high-growth software and digital commerce leaders. Institutional accumulation surged as market participants increasingly view Shopify as a prime infrastructure beneficiary of the artificial intelligence revolution. Beyond the Meta agreement, momentum has been building around Shopify's suite of proprietary AI tools, automated workflow features, and strategic distribution partnerships, including integrations for conversational product discovery. Easing macroeconomic yields and favorable monetary policy expectations have provided an additional tailwind for high-multiple growth equities, encouraging capital inflows into digital retail infrastructure.
Underpinning this price movement is Shopify's robust operational foundation, characterized by strong gross merchandise volume expansion, accelerating international revenue growth, and expanding operating margins. Wall Street sentiment remains constructive, with multiple sell-side firms reiterating buy ratings and raising price targets based on the firm's demonstrated operating leverage. Although short-term volatility remains present due to valuation metrics trading at a premium relative to traditional software peers, the combination of aggressive platform innovation, disciplined expense control, and leadership in agentic commerce continues to provide a strong structural growth thesis for long-term institutional investors.
Technical Analysis of Shopify Inc (SHOP)
Technically, Shopify Inc (SHOP) shows a MACD (12,26,9) value of 0.522, indicating a neutral signal. The RSI at 60.303 suggests neutral condition and the Williams %R at 2.505 suggests overbought condition. Please monitor closely.
Fundamental Analysis of Shopify Inc (SHOP)
Shopify Inc (SHOP) is in the Software & IT Services industry. Its latest annual revenue is $11.56B, ranking 32 in the industry. The net profit is $1.23B, ranking 40 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $172.92, a high of $220.00, and a low of $120.00.
More details about Shopify Inc (SHOP)
Company Specific Risks:
- Elevated Valuation and Vulnerability to Multiple Compression: Trading at a forward P/E ratio above 70x and a price-to-sales multiple near 9.4x—well above broad software and e-commerce industry averages—Shopify's premium pricing leaves minimal room for operational missteps, exposing the stock to intraday multiple compression on macro or earnings headwinds.
- Gross Margin Dilution from Revenue Mix Shift: Rapid expansion in lower-margin Merchant Solutions continues to outpace higher-margin Subscription Solutions, driving payment processing expenses higher and leading guidance for Q3 gross profit growth (mid-to-high 20% range) to lag total revenue growth expectations.
- Rising AI Compute Expenses and Unproven Direct Monetization: Platform-wide deployment of agentic AI tools and recent ecosystem acquisitions are escalating LLM infrastructure costs, lifting Q3 operating expense guidance to 33%–34% of revenue while AI features remain monetized through standard transaction economics rather than dedicated high-margin fees.
- Ecosystem Competition from Big Tech and E-Commerce Rivals: Institutional research highlights structural risks from Meta Platforms natively integrating AI commerce tools for small-and-medium businesses, alongside persistent competitive pressure from Amazon, posing potential threats to merchant retention and long-term same-store sales growth.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.