


Novo Nordisk A/S Stock (NVO) Moved Down by 7.86% on Sep 21: A Full Analysis



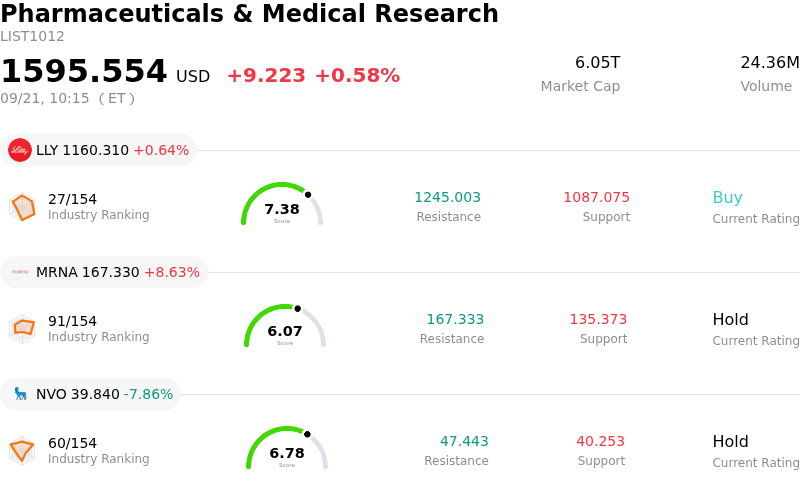
Novo Nordisk A/S (NVO) moved down by 7.86%. The Pharmaceuticals & Medical Research sector is up by 0.58%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) up 0.64%; Moderna Inc (MRNA) up 8.63%; Novo Nordisk A/S (NVO) down 7.86%.
What is driving Novo Nordisk A/S (NVO)’s stock price down today?
Novo Nordisk experienced significant downward pressure following its 2026 Capital Markets Day, where executive management presented updated long-term strategic targets. Although the company outlined plans to launch multiple multi-blockbuster therapies by 2030 and expand its pipeline revenue substantially by 2035, the updated targets failed to reignite investor enthusiasm. The market reacted coolly to the timeline, as many of the outlined growth drivers remain years away from commercialization, leaving investors concerned over the lack of concrete near-term catalysts to accelerate top-line expansion.
Compounding the negative sentiment is the growing competitive threat in the metabolic care and weight-loss space. Main rival Eli Lilly continues to capture market share, squeezing growth for Novo Nordisk's flagship semaglutide franchise. Furthermore, concentration risk remains high, with semaglutide-based treatments generating the vast majority of current revenue. With key patent expirations approaching in the early 2030s, Wall Street has expressed heightened concern over the company's ability to defend its market dominance against generic and branded alternatives, leading to recent institutional rating downgrades.
Even positive clinical updates failed to offset the prevailing risk-off mood. Novo Nordisk announced promising Phase 3 topline data for its next-generation weight management product, CagriSema, demonstrating robust efficacy in weight reduction and blood sugar control. However, market focus remained squarely on long-term market share erosion and execution uncertainty. While the company maintains an active share buyback program and a solid underlying balance sheet, investors opted to reduce exposure as they weigh near-term commercial hurdles against ambitious long-term targets.
Technical Analysis of Novo Nordisk A/S (NVO)
Technically, Novo Nordisk A/S (NVO) shows a MACD (12,26,9) value of -0.874, indicating a sell signal. The RSI at 31.412 suggests neutral condition and the Williams %R at 98.926 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Novo Nordisk A/S (NVO)
Novo Nordisk A/S (NVO) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $46.70B, ranking 12 in the industry. The net profit is $15.48B, ranking 4 in the industry. Company Profile
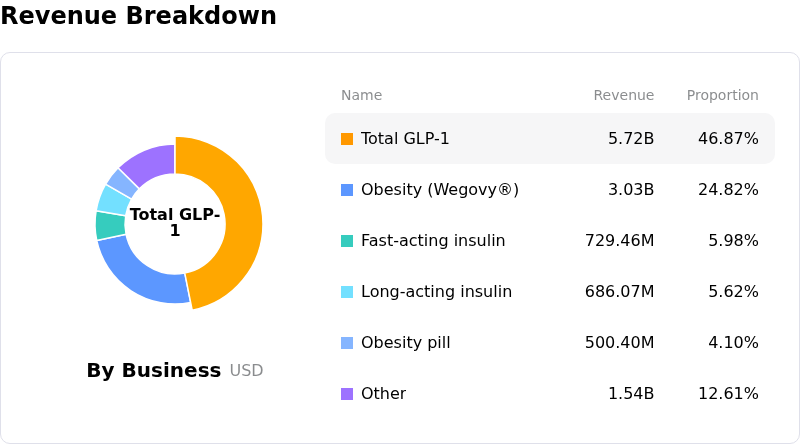
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $49.21, a high of $65.00, and a low of $40.00.
More details about Novo Nordisk A/S (NVO)
Company Specific Risks:
- Sluggish Long-Term Guidance from Capital Markets Day: Capital Markets Day targets project revenue growth from 2026 to 2030 to merely align with industry peers, confirming a significant deceleration from past high-growth trajectories and triggering immediate intraday selling pressure.
- Semaglutide Patent Expiry and Concentration Risk: Semaglutide-based therapies generate over 75% of total sales, exposing the company to major revenue cliff risks as leadership highlighted the 2032 U.S. patent expiration without presenting sufficient near-term pipeline catalysts.
- Market Share Erosion and Competitive Pressure from Eli Lilly: Rival GLP-1 treatments Zepbound and Mounjaro continue to aggressively capture U.S. market share, with Zepbound sales projected to outpace Wegovy by more than $7 billion this year.
- Institutional Analyst Downgrades and Valuation Re-ratings: Wall Street brokerages, including Morgan Stanley downgrading the stock to Underweight, cite muted medium-term growth prospects and pipeline lag, sparking ongoing institutional derisking.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles





Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.